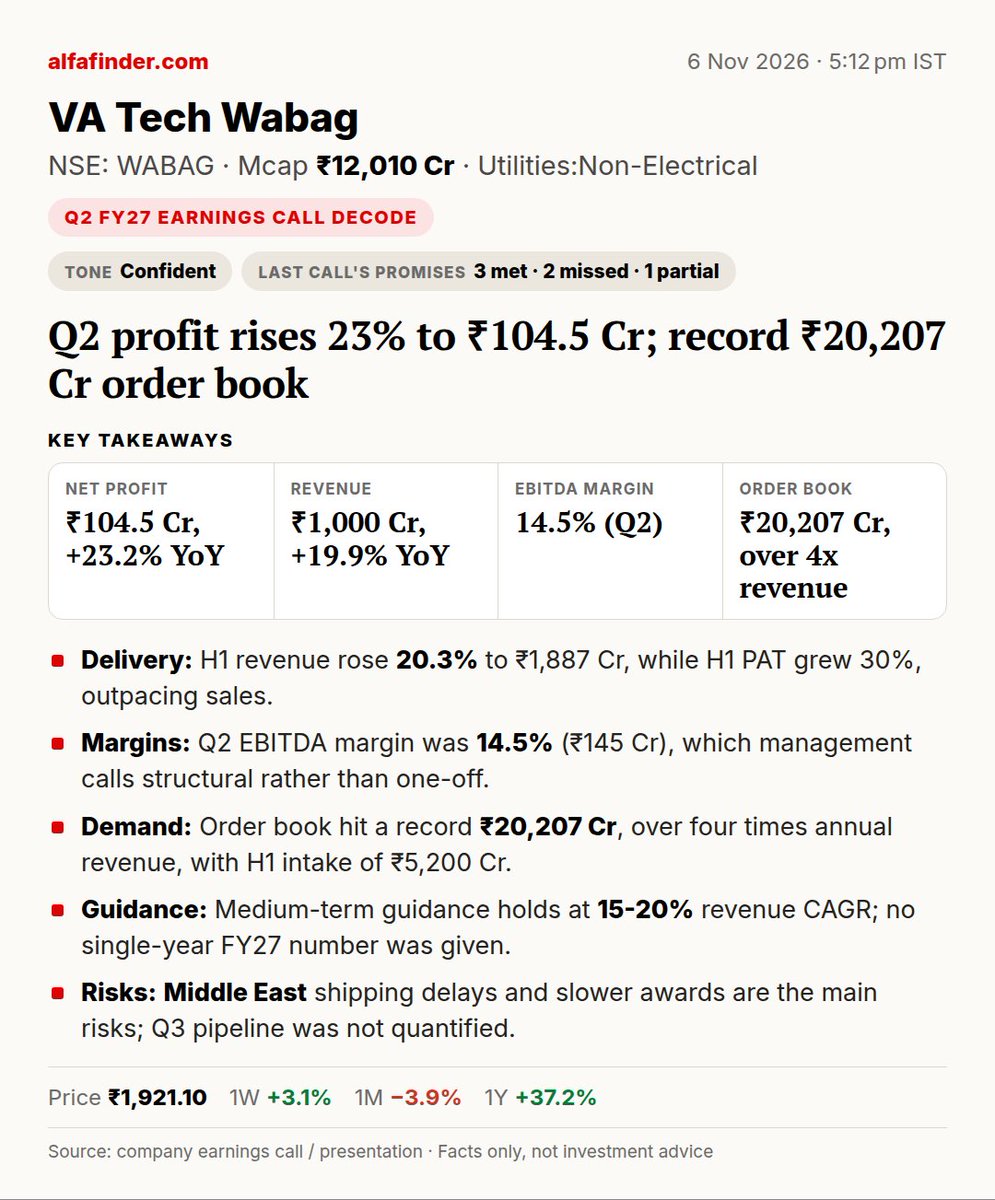
🎙️ VA Tech Wabag (WABAG) call just ended. Here is the decode ⬇️
VA Tech Wabag's Q2 FY27 revenue rose 19.9% to ₹1,000 Cr, and net profit grew 23.2% to ₹104.5 Cr. EBITDA was ₹145 Cr at a 14.5% margin, and H1 profit rose 30%, outpacing revenue. EPC made up 82% of H1 revenue, with O&M at 18%, and the order book reached a record ₹20,207 Cr. Management kept its medium-term guidance of 15-20% revenue CAGR and 13-15% EBITDA margin, and gave no single-year FY27 figure. Against earlier promises, revenue and order-book targets were beaten and the margin sits within the 13-15% band. However, the claim of no Middle East slowdown reversed within a quarter, as awards slowed and shipping delays emerged.
Growth triggers
• Doha SWRO desalination plant in Kuwait: ₹1,425 Cr order with a 36-month construction period, signed 25 Aug 2026.
• Reliance Jamnagar desalination and remineralisation plant: ₹1,000 Cr order executed in phases over 25 months, announced 27 Oct 2026.
• Medium-term outlook over 3-5 years: 15-20% revenue CAGR, 13-15% EBITDA margin and ROCE above 20%.
Blockers
• Middle East shipping delays and slower new-project awards, with Saudi caution, are the named risks.
• Commodity inflation is a named risk, and the Q3 pipeline remains unquantified.
#WABAG #EarningsCall #Q2FY27
After Wabag I'm expecting frontsp is going to post blockbuster results in based on their last concall they are online to achieve 500 crores gross revenue to achieve that Q2 they must post net sales around 110 to 120 crores
So, This quarter is going to be strong
#frontiersprings