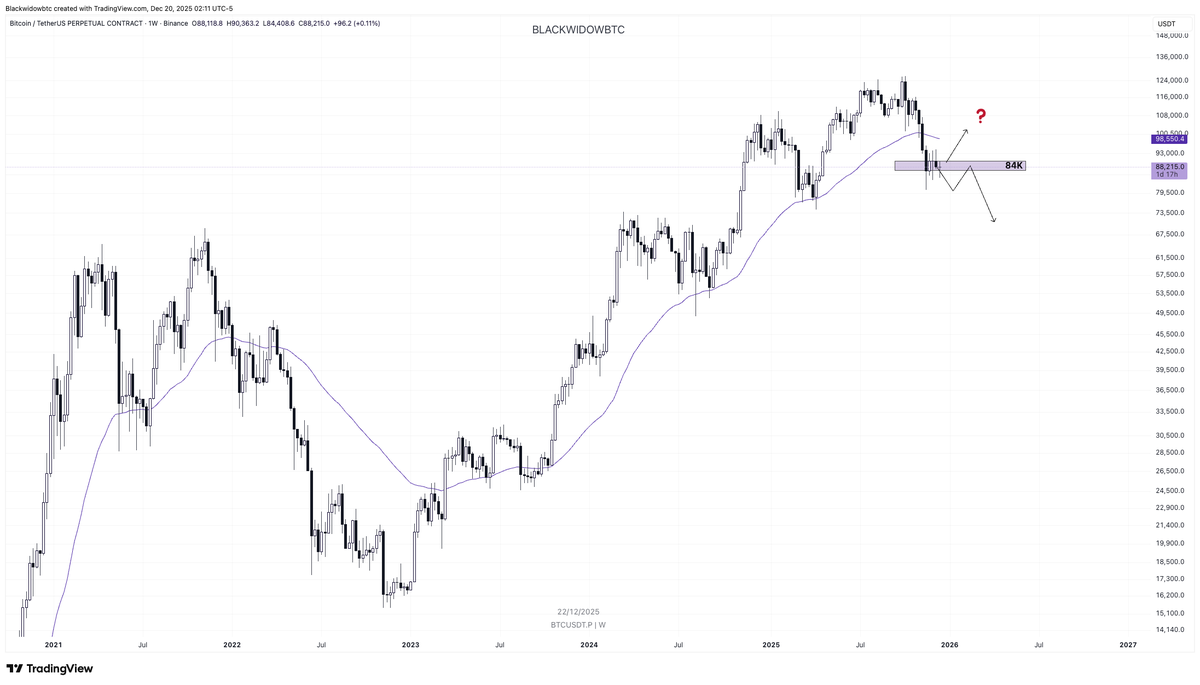
The bullish and bearish case for #Bitcoin and how I am positioned currently
What comes next depends on this 84K weekly/monthly block
I have the biggest cash position I have had all cycle since I scaled out and did not buy the top
So I have cash and crypto, and i'm waiting for the resolution here at this 84K HTF block to determine the next move
If Bitcoin reverses into a bull market and reclaims its 50 EMA - I want to play ALTS (because of Dom and ETH/BTC)
Another leg down strengthens the bear case
I am not scared of bull or bear.
Do your best.
Goodbye.
@blackwidowbtc I've seen this happen to everyone so it doesn't seem gender specific (although that can add another layer to this). As usual, do your thing and ignore the trolls
The K-Shaped Economy Crisis (KEC) Will Persist Unless There Is Structural Regime Change at the Fed
Watch this much-needed public service announcement from our November 1, 2025, Around the Horn if you want to better understand the advanced monetary dynamics contributing to the U.S.’s K-Shaped Economy Crisis (KEC).
It’s not too late to remedy the Fed’s failed, backward-looking monetary policy framework.
But reform must occur soon, and it will only come if the econ PhDs currently defending the institution’s legacy of policy failure demonstrate far more humility than they have recently.
Thank you for watching. God bless America!💜
@blackwidowbtc Don't let it get to you! There seems to be an unlimited supply of jerks out there. Keep doing your thing and the people who support you will have your back (like me and many of your other followers).
I think 0.053 is a good target for #ETH / #BTC, give or take.
If/when that happens, I'll probably re-assess.
Will likely get some pullbacks along the way, especially around the Sep-Oct timeframe.
BTC
time to pay attention here as we flipped and closed 1D above 110k which is quite bullish imo
it's been a nice summer vacation but time to get back in the trenches
higher
Good morning, and God bless, #Team42!
Today’s Key Macro Question(s): Will risk assets retest the lows?
Tech stocks dropped after the US cracked down on Nvidia $NVDA chip exports to China and ASML $ASML NA posted weak results, reigniting trade-war fears. NVDA and ASML are down -6% (premarket) and -5%, respectively, this morning.
China is holding out on trade talks until the Trump administration "shows more respect" by toning down its rhetoric, per a source familiar with Beijing’s stance. In our view, the Trump administration will show China more respect and negotiations will eventually occur because we believe the Trump administration is already in the “to de-escalate” phase of the “escalate to de-escalate” mantra from @realDonaldTrump's “art of the deal”.
We can clearly observe this via the 90-day pause on reciprocal tariffs, carve outs for consumer electronics and other sensitive items, and the evolution of @USTreasury@SecScottBessent to becoming the dominant mouthpiece of the administration. In just the past ~week alone, Secretary Bessent appeared on the following networks in longform interview format:
CNBC (4/8): https://t.co/MHsef4qxXa
Fox Business (4/9): https://t.co/lJxSYbVn5s
C-SPAN (4/9): https://t.co/95VpaYKDkJ
Bloomberg (4/14): https://t.co/WsuFAGCMM0
Yahoo Finance (4/15): https://t.co/wv2zOFvpCm
It cannot be stressed enough that the Treasury Secretary sitting down with Yahoo Finance (no disrespect) on Tax Day—the Treasury Department’s Super Bowl—to promote trade negotiations, tax cuts, and deregulation says a lot. There was a dramatically increased emphasis on these pro-growth, pro-markets policies in these recent interviews compared to his interviews over the past few months.
Moreover, Bessent’s pivot away from his prior guidance of an economic “detox period” and his prediction that it would become “Trump’s economy in 6–12 months” to taking credit for the resiliency of the economy in Q1 data suggests our data-driven view that the bond market activated the “Trump put” is likely correct. If so, then several of the key takeaways from our recent research reports are likely correct as well:
“We view the current meltdown in the Treasury market as part and parcel of the Fourth Turning polycrisis that we have been preparing 42 Macro clients for since the summer of 2023 when we first debuted our Investing During A Fourth Turning Regime presentation. One of the key takeaways from the presentation is our structural bearish bias on Treasury bonds and expectation that the US would have a cascading series of EM-style financial crises that require greater and greater monetary debasement and financial repression by the Fed to calm Treasury market dysfunction. We put this deeply researched view into action when we pivoted our systematic KISS Portfolio Construction Process permanently out of Treasuries and into Gold last fall. Ultimately, the Fed will be forced to go to unprecedented lengths to plug the growing, geopolitically driven supply-demand imbalance in the Treasury bond market once the world deems the US to be in fiscal crisis—an outcome we still anticipate by 2030.” –4/9 Leadoff Morning Note
“All told, the fact that the “Trump put” was exercised—or at a minimum rolled to July 9—due to stress in the Treasury bond market has both positive and negative implications. On the positive side, it clears the way for, at worst, a retest of the lows in the interim and, at best, a sustained uptrend from here. On the negative side, it is confirmation of the growing, geopolitically driven supply-demand imbalance we have been warning about in the Treasury bond market… [T]he distribution of probable economic outcomes is as wide as most investors have ever seen, so remain dispassionate and ready to pivot if/when KISS and Dr. Mo pivot. Odds are you’ll thank them later even if you/we do not trust or fully understand why in the moment. The market is smarter than we are, and someone always knows something (e.g., "THIS IS A GREAT TIME TO BUY!!! DJT” at 9:37am ET yesterday).” –4/10 Leadoff Morning Note
“Elsewhere, the House’s narrow 216-214 adoption of the Senate’s budget resolution advances Republican efforts to deliver up to $5.3tn in tax cuts over 10 years and raises the Debt Limit by $5tn in exchange for a minimum of $4bn in spending reductions. After weeks of hardball, House fiscal hawks gave up on demanding binding cuts and instead settled for a handshake deal with the Senate to balance out the cost of tax cuts. That deal erases a March win for House conservatives, who had raised the spending cut floor from $1.5tn to $2tn and included a provision to reduce the tax cut allowance if those offsets weren’t met. This erosion of fiscal restraint represents an incremental tailwind to the structural bear case for the US dollar and an incremental tailwind to the structural bull case for Gold. This vote followed Trump’s announcement of a 90-day pause on tariffs that had been rattling markets and recession fears and represents a concerted effort by the Trump administration to ameliorate the damage they have caused by their inauspicious rollout of tariff policy.” –4/11 Leadoff Morning Note
“In our view, this past week represents the most transformational week in asset markets since the Lehman Bros. bankruptcy catalyzed nearly two decades of fiscal and monetary policy largesse. Geopolitically driven stress in the Treasury market is accelerating the transition from “US exceptionalism” to the US being an emerging market in capital flight risk terms. President Trump may be operating under the assumption that the US is “too big to fail” and foreign creditors may check him on that. Markets thought Lehman was “too big to fail” too. This transition has several profound implications for asset markets: 1) the rest of the world has much more negotiating leverage than anyone in the Trump administration is willing to admit publicly, increasing the probability that reciprocal tariff rates are broadly lowered in deals that President Trump will celebrate as “wins”, but are likely less effective than the Phase One China trade deal and USMCA he negotiated during his first term—we wouldn't be here today if the “art of the deal” actually worked back then; 2) incremental dysfunction in the Treasury market will force the Fed to expand its balance sheet in support of its financial stability mandate; 3) incremental dysfunction in the Treasury market will force regulators to accelerate financial repression as well (e.g., removing the SLR for Treasury securities); and 4) the Fed may be forced to HIKE rates during future recessions to attract capital to the Treasury market.” –4/12 Around the Horn
“According to the White House, the exemption from the 145% China tariff and 10% global flat rate on consumer electronics is temporary and part of a longer-term plan, though the move signals Trump’s willingness to compromise and represents incremental confirmation of our view that the bond market activated the “Trump put” last week. China’s consistently firm tone indicates that it believes it has the upper hand in negotiations. At a minimum, President Xi’s historic consolidation of power means he will likely outlast President Trump’s second term. At a maximum, China understands and can weaponize the fact that the other side of a trade war is a capital war that the bloated US public sector can ill afford to lose.” –4/14 Leadoff Morning Note
“Yesterday we asked if Trump was losing his own trade war. Thus far, the answer is “yes,” and the answer may remain “yes” at the end of the process for all the Fourth Turning polycrisis reasons we detailed in our 4/10 Leadoff Morning Note, 4/11 Leadoff Morning Note, and 4/12 Around the Horn webcast. The chronic combination of overconsumption by US households, overinvestment by US businesses, overspending by the US government, and undertaxing by the US government have left the US economy and asset markets in a very unresilient state amid mounting geopolitical headwinds. All told, the US’ net national savings rate is simply too low for President Trump to bully his way into the “US exceptionalism” his policies ended—at least temporarily. The US is simply too reliant on foreign capital to grow our economy. For example, the US’ twin-deficit current account and sovereign fiscal balances total -11 percent of GDP and is at an all-time low non-war, non-recession value amid foreigners owning 30% of outstanding marketable Treasury securities. To the extent President Trump is still serious about facilitating the Fourth Turning-style transition Paradigm A to Paradigm B, the only path forward is to accept that the transition will be painful and deal with it. The constant flip-flopping and lack of clear guidance is little more than a sign of US weakness in global capital war terms.” –4/15 Leadoff Morning Note
Risk assets will likely retest the lows over the coming months as consensus GDP, sales, and earnings estimates are ratcheted down towards economic reality. If the US avoids an actual/NBER recession—and we think it will based on everything we can observe today across persistent leading indicators of the business cycle—that retest should hold or narrowly breach at worst.
Investors would be remiss not to buy the likely retest dip because it is likely President Trump has already lost the trade/capital war he started and has pivoted to the pro-growth, pro-markets phase of his economic agenda as a result. Consensus actual/NBER recession probabilities are currently in the 40-50% range according to our analysis of anecdotal data and conversations with institutional investors. They will likely peak in the 65-75% range in response to weak economic data and company guidance in Q3 and trend back towards the standard 15% range by year-end.
Please note this is a forecast based on everything we know today and we reserve the right to pivot based on new information—a right we’ve earned based on our world-beating track record in predicting and helping clients profit from this crisis with surgical precision since last fall.
If you found this note helpful, please like and share. Thank you!
Consistently making money and protecting gains in financial markets require a lot of time, expertise, and computational power. Investors partner with 42 Macro because we do the heavy lifting and answer the hard questions for them. See for yourself: https://t.co/LQvjX7i7qY.
Have a great day!
-Skipper