🇯🇵 Japan is entering one of the most important economic transitions in its modern history.
For decades, Japan has carried the weight of the “lost decades”: slow growth, deflationary pressure, an ageing society, labour shortages, a shrinking working-age population and increasing pressure on both public services and private enterprise.
The old model cannot simply be stretched forever. The next generation of Japanese prosperity will not come from adding more labour into a system that no longer has enough labour to give. It will come from multiplying productivity.
This is why AI, stablecoins, digital identity, programmable finance and autonomous agents are no longer separate technology trends in Japan. They are becoming a national economic necessity.
Japan does not just need “AI chatbots.” Japan needs trusted AI agents. Agents that can help citizens, merchants, banks, enterprises and public institutions operate with more speed, more intelligence, more efficiency and less friction.
Even Japan’s Digital Agency has acknowledged that labour shortages caused by population decline, ageing and low birth rates mean national and local governments must actively use AI, including generative AI, to maintain and improve services.
Source:
https://t.co/8uUGpoIt2T
The FSA has also framed the same reality from the financial side: Japan faces a declining population, ageing society, labour shortages, succession issues and pressure on regional businesses. Its response is to encourage digitalisation, productivity and secure innovation across financial services.
Source:
https://t.co/kygU5W1eHy
This is the real macro backdrop.
Japan’s government, regulators, megabanks, payment networks and major enterprises are not randomly exploring AI, stablecoins, Web3 and digital identity. They are building the next productivity layer for the Japanese economy, and this is where the NetX vision is starting to come together.
The first phase is real-world payments.
NetStars has officially announced StarPay-X, a gateway concept designed to connect Web2 payment infrastructure with Web3 finance, including stablecoins, wallets, blockchains, exchanges and DeFi.
Source:
https://t.co/lhwxwDvIoE
This is important because StarPay-X is not about isolated crypto users clicking around on a DeFi app. It is about moving Web3 finance into real stores, real services and real commercial flows.
Then came the Startale partnership.
NetStars and Startale signed an MOU to promote Web3 payments under the StarPay-X concept, including the exploration of JPYSC, the Japanese yen stablecoin being developed by Startale and SBI.
Source:
https://t.co/cxdyun3zUC
JPYSC itself is a trust-bank-backed Japanese yen stablecoin, with SBI VC Trade as the primary distribution partner and Startale leading technical development.
Source:
https://t.co/cQWUhcLmDj
So the payment layer is now appearing publicly but at the same time, the bank settlement layer is also moving.
MUFG Bank, Mizuho Bank and SMBC have announced plans to conduct actual commercial transactions in fiscal year 2026 using a jointly issued stablecoin.
Source:
https://t.co/vuqRn71Xat
Datachain has also stated that Project Pax is a cross-border remittance infrastructure project developed with Japan’s three megabanks, Swift and Progmat.
Source:
https://t.co/oZbal5dk4i
So the sequence is becoming visible:
Real-world payment rails → Regulated stablecoins → Institutional settlement → Bank-grade governance → Commercial adoption.
But payments are not the endgame, payments create the data meaning every real-world transaction creates intelligence:
All the information on what users buy, what merchants need, where liquidity is needed, fraud risks, demand growth etc. is data that becomes the fuel for smarter AI agents.
This is the flywheel @anbangr has been pointing toward:
Real users create real transactions.
Real transactions create real data.
Real data creates smarter agents.
Smarter agents create better PayFi, DeFi and commerce products.
Better products bring more users, merchants and institutions back into the system.
Payments and agents are not two separate roadmaps. They are one system.
Live payment rails create the data layer.
Trusted settlement creates the value-transfer layer.
AI agents create the intelligence layer.
Agent governance creates the safety layer.
But for a true agent economy to flourish, intelligence alone is not enough.
Agents need safe frameworks for identity, delegation, authority, verification, settlement, reputation, compliance and governance
This is why Anbang’s work on NEF, AgentCity and AGNT2 becomes so important.
It is the framework for how autonomous agents can safely interact, transact, coordinate and govern themselves in a real financial environment.
NEF addresses the problem of agents becoming black-box decision makers with too much unchecked control.
AgentCity develops the idea of a governed agent society, where agents operate under rules, accountability and separation of powers.
AGNT2 addresses the infrastructure problem directly: normal blockchains and L2s are designed mainly for human-initiated transactions, but AI agents require machine-speed interaction, identity, escrow, reputation, session context, dependency ordering and settlement.
That is why AgentCity and AGNT2 matter. They are the missing safety and execution framework for a real agent econom, and now the synchronicity is becoming impossible to ignore.
MUFG and Mitsubishi UFJ Trust have launched the DID/VC Co-Creation Consortium “AI Agent × Financial Transactions” working group.
The group is studying a future where AI agents execute financial transactions on behalf of users, with focus on delegation of authority, verifiable credentials, legal issues, reliability, safety, transparency and governance.
Source:
https://t.co/2gpbfTai6G
This is the exact problem space Anbang has been building toward. This is why the NetX thesis is becoming much larger than “another blockchain.”
The next milestones should be StarPay-X launching at real-world terminals, merchants benefiting from NetX-linked incentives or discounts, stablecoin settlement expanding, and AgentCity/AGNT2 moving from theory into real infrastructure.
But the real kicker is what comes after.
If agents themselves need to hold and use NetX to interact, consume data, verify each other, build reputation, access services and settle value, then the TAM is no longer limited to human users or merchant payments.
The TAM becomes the agent economy itself where a population of millions to billions of agents all need NetX to enter the agent city.
This is what can take NetX from “just another blockchain” into core infrastructure and not only a chain for payments. A coordination layer between real-world finance, regulated settlement and autonomous machine economies.
The full flywheel is now becoming clear:
StarPay-X brings real merchants on-chain.
Stablecoins bring regulated settlement.
Real transactions create real data.
Real data feeds intelligent agents.
AgentCity and AGNT2 provide safe agent governance.
Agents interact, transact and settle through the network.
NetX becomes the coordination layer between humans, institutions, merchants and autonomous agents.
Japan’s ageing economy needs productivity.
Productivity requires AI.
Financial AI requires trusted agents.
Trusted agents require identity, delegation, compliance, settlement and governance.
Real-world payments create the data those agents need.
And agents create the next generation of intelligent financial products.
The buildout is no longer theoretical.
Japan’s government, regulators, megabanks, payment networks, enterprise technology firms and AI-agent working groups are all moving toward the same architecture.
The synchronicity is too high to dismiss.
NetX Mainnet + StarPay-X + AgentCity + AGNT2 is starting to look like one system:
Live payment rails.
Trusted settlement.
Real transaction data.
And a self-governing agent economy on top.
The resonance between what is being built by @MidnightNtwrk and @WEA_JP shares a lot more synergy than may meet the eye.
WEA Japan finds it foundations from the founders of @netx_world with deep roots in trusted computing and infrastructure build out in China involving super large scale such as the CFLP (Chinese Supply Chain), Huawei and multiple Chinese banks, insurance companies and medical institutions.
The vision is quite simple; to make the web3 world actually infiltrate and immerse itself into current web2 systems, thus birthing what @anbangr coins “Web2.5”. The WEA play at surface level seems simple, to incorporate stablecoin payments directly into existing POS terminals. The real kicker is when this happens using existing wallet infrastructure and hardware without the need for a card provider or extra devices, just simply scan and pay. The system in the background protects data, ensures AML/KYC compliance and leaves the merchant with JPY in their bank accounts (no crypto knowledge needed), at the surface level it appears as a simple WeChat or PayPay style QR code payment.
The real exciting part is what Web2.5 allows. The chance to slowly introduce more and more Web3 features, imagine actually receiving cash back directly to your wallet without providing or filling out forms or signing up for a new loyalty card. Or receiving rewards and gifts that are personalised to you and your actual shopping history, now these airdrop straight to your wallet increasing shopper and merchant relations.
With Agent City now being built we can see the wider vision coming to life, as more and more blockchains, wallets and merchants enter the @NSS_StarPayX ecosystem. Soon we will see automated agents acting and procuring items for their owners in a completely safe and decentralised manner thanks to the Separation of Powers model described by Dr Anbang Ruan over a decade ago when discussing the emergence of Trustworthy, Reliable, Intelligent and Autonomous Systems which is exactly what we are witnessing as we spearhead into the AI era.
Lawson has announced a stablecoin payment pilot using $JPYC and this isn’t just about accepting crypto. It’s about making blockchain invisible.
It’s the clearest example yet of what we’ve been calling Web2.5, where existing payment infrastructure remains unchanged while blockchain quietly becomes the settlement layer underneath.
Let’s break down what’s actually happening:
The customer experience
The customer opens their HashPort wallet. A familiar retail barcode appears, the cashier scans it using the existing Lawson checkout. The customer then approves the payment. The receipt prints “payment successful” without worrying about wallet addresses, or copying QR strings.
To the customer it feels no different to PayPay or Rakuten Pay and that’s the exactly recipe for mass adoption.
So who actually does what?
Lawson (@akiko_lawson) remains exactly what it already is, the retailer.
Its POS, inventory, receipts and cashier workflow don’t change. Staff don’t need blockchain knowledge because the blockchain sits behind the existing checkout experience.
HashPort (@hashport_io) provides the customer wallet. That’s where the user holds JPYC, receives the payment request and authorises the transaction.
Canal Payment Service is the bridge into Lawson’s existing payment infrastructure. When the barcode is scanned, Canal routes the payment request through the same retail payment network Lawson already uses. From the POS’s perspective, it’s simply another supported payment method.
KDDI (@official_kddi) is arguably one of the most overlooked participants. Beyond providing enterprise payment integration, KDDI brings an enormous consumer ecosystem through au ID, au PAY, Ponta Points, banking and financial services.
If this expands beyond the pilot, stablecoin payments could become seamlessly integrated with loyalty rewards, merchant offers and financial products. That’s when blockchain stops being a niche technology and becomes part of everyday commerce.
WEA (@WEAJapan) creates the payment session and generates the merchant-compatible barcode. This bridged native blockchain assets into Japan’s existing retail payment infrastructure. Also handling the enterprise payment workflow required for KYC and AML compliance.
WEA also enables refund functionality, something consumers expect from traditional payment systems but which is often overlooked in blockchain payments.
This isn’t just another wallet, it’s the technical bridge that allows Web3 assets to function inside Web2/ real-world commerce.
Interestingly, WEA Pay now supports JPYC/ Polygon and generates both QR codes and traditional Japanese retail payment barcodes, the exact payment experience required for this type of POS integration.
NetX (@netx_world) is the settlement layer. Polygon remains the asset layer but NetX coordinates everything happening around the payment such as; merchant authentication, settlement orchestration, payment verification, enterprise auditability, privacy-preserving proofs, compliance workflows, refund coordination and confirmation back to the POS.
That’s a very different role from simply moving tokens between wallet addresses.
NetStars (@Kouhou_NSS) completes the commercial payment flow. Operating under its regulated Money Transfer Business licence, NetStars receives the JPYC payment, handles the conversion into fiat JPY and ultimately settles Japanese Yen into the merchant’s bank account. This means Lawson never needs to hold or manage crypto directly, they simply receive JPY through the same enterprise settlement process expected by any major retailer. Blockchain powers the payment behind the scenes, while the merchant experience remains entirely familiar.
Putting it all together
Customer
⬇️
HashPort Wallet
⬇️
WEA creates a secure payment session and merchant-compatible barcode
⬇️
Lawson scans using its existing POS
⬇️
Canal routes the payment through Lawson’s existing retail payment infrastructure
⬇️
Customer authorises the JPYC transaction on Polygon
⬇️
NetStars receives the JPYC, converts it and settles fiat JPY to Lawson
⬇️
NetX coordinates settlement, compliance, privacy-preserving verification and confirmation
⬇️
Payment approval returns to Lawson
⬇️
Receipt prints.
To the customer, it feels exactly like every other digital payment and this is huge because the biggest barrier to blockchain adoption has never been the technology. It’s been the user experience.
This architecture allows existing retail infrastructure to remain untouched while blockchain delivers programmable money, enterprise-grade settlement, privacy-preserving compliance and automated financial workflows behind the scenes.
That’s the definition of Web2.5. Not replacing Web2 but upgrading it.
If KDDI’s wider ecosystem eventually plugs into this architecture, the implications become even more interesting. Imagine paying with a stablecoin while automatically earning Ponta Points, redeeming loyalty rewards, receiving AI-driven merchant offers or using programmable payments across retail, banking and financial services.
All without changing the user or merchant checkout experience.
Lawson has announced a stablecoin payment pilot using $JPYC and this isn’t just about accepting crypto. It’s about making blockchain invisible.
It’s the clearest example yet of what we’ve been calling Web2.5, where existing payment infrastructure remains unchanged while blockchain quietly becomes the settlement layer underneath.
Let’s break down what’s actually happening:
The customer experience
The customer opens their HashPort wallet. A familiar retail barcode appears, the cashier scans it using the existing Lawson checkout. The customer then approves the payment. The receipt prints “payment successful” without worrying about wallet addresses, or copying QR strings.
To the customer it feels no different to PayPay or Rakuten Pay and that’s the exactly recipe for mass adoption.
So who actually does what?
Lawson (@akiko_lawson) remains exactly what it already is, the retailer.
Its POS, inventory, receipts and cashier workflow don’t change. Staff don’t need blockchain knowledge because the blockchain sits behind the existing checkout experience.
HashPort (@hashport_io) provides the customer wallet. That’s where the user holds JPYC, receives the payment request and authorises the transaction.
Canal Payment Service is the bridge into Lawson’s existing payment infrastructure. When the barcode is scanned, Canal routes the payment request through the same retail payment network Lawson already uses. From the POS’s perspective, it’s simply another supported payment method.
KDDI (@official_kddi) is arguably one of the most overlooked participants. Beyond providing enterprise payment integration, KDDI brings an enormous consumer ecosystem through au ID, au PAY, Ponta Points, banking and financial services.
If this expands beyond the pilot, stablecoin payments could become seamlessly integrated with loyalty rewards, merchant offers and financial products. That’s when blockchain stops being a niche technology and becomes part of everyday commerce.
WEA (@WEAJapan) creates the payment session and generates the merchant-compatible barcode. This bridged native blockchain assets into Japan’s existing retail payment infrastructure. Also handling the enterprise payment workflow required for KYC and AML compliance.
WEA also enables refund functionality, something consumers expect from traditional payment systems but which is often overlooked in blockchain payments.
This isn’t just another wallet, it’s the technical bridge that allows Web3 assets to function inside Web2/ real-world commerce.
Interestingly, WEA Pay now supports JPYC/ Polygon and generates both QR codes and traditional Japanese retail payment barcodes, the exact payment experience required for this type of POS integration.
NetX (@netx_world) is the settlement layer. Polygon remains the asset layer but NetX coordinates everything happening around the payment such as; merchant authentication, settlement orchestration, payment verification, enterprise auditability, privacy-preserving proofs, compliance workflows, refund coordination and confirmation back to the POS.
That’s a very different role from simply moving tokens between wallet addresses.
NetStars (@Kouhou_NSS) completes the commercial payment flow. Operating under its regulated Money Transfer Business licence, NetStars receives the JPYC payment, handles the conversion into fiat JPY and ultimately settles Japanese Yen into the merchant’s bank account. This means Lawson never needs to hold or manage crypto directly, they simply receive JPY through the same enterprise settlement process expected by any major retailer. Blockchain powers the payment behind the scenes, while the merchant experience remains entirely familiar.
Putting it all together
Customer
⬇️
HashPort Wallet
⬇️
WEA creates a secure payment session and merchant-compatible barcode
⬇️
Lawson scans using its existing POS
⬇️
Canal routes the payment through Lawson’s existing retail payment infrastructure
⬇️
Customer authorises the JPYC transaction on Polygon
⬇️
NetStars receives the JPYC, converts it and settles fiat JPY to Lawson
⬇️
NetX coordinates settlement, compliance, privacy-preserving verification and confirmation
⬇️
Payment approval returns to Lawson
⬇️
Receipt prints.
To the customer, it feels exactly like every other digital payment and this is huge because the biggest barrier to blockchain adoption has never been the technology. It’s been the user experience.
This architecture allows existing retail infrastructure to remain untouched while blockchain delivers programmable money, enterprise-grade settlement, privacy-preserving compliance and automated financial workflows behind the scenes.
That’s the definition of Web2.5. Not replacing Web2 but upgrading it.
If KDDI’s wider ecosystem eventually plugs into this architecture, the implications become even more interesting. Imagine paying with a stablecoin while automatically earning Ponta Points, redeeming loyalty rewards, receiving AI-driven merchant offers or using programmable payments across retail, banking and financial services.
All without changing the user or merchant checkout experience.
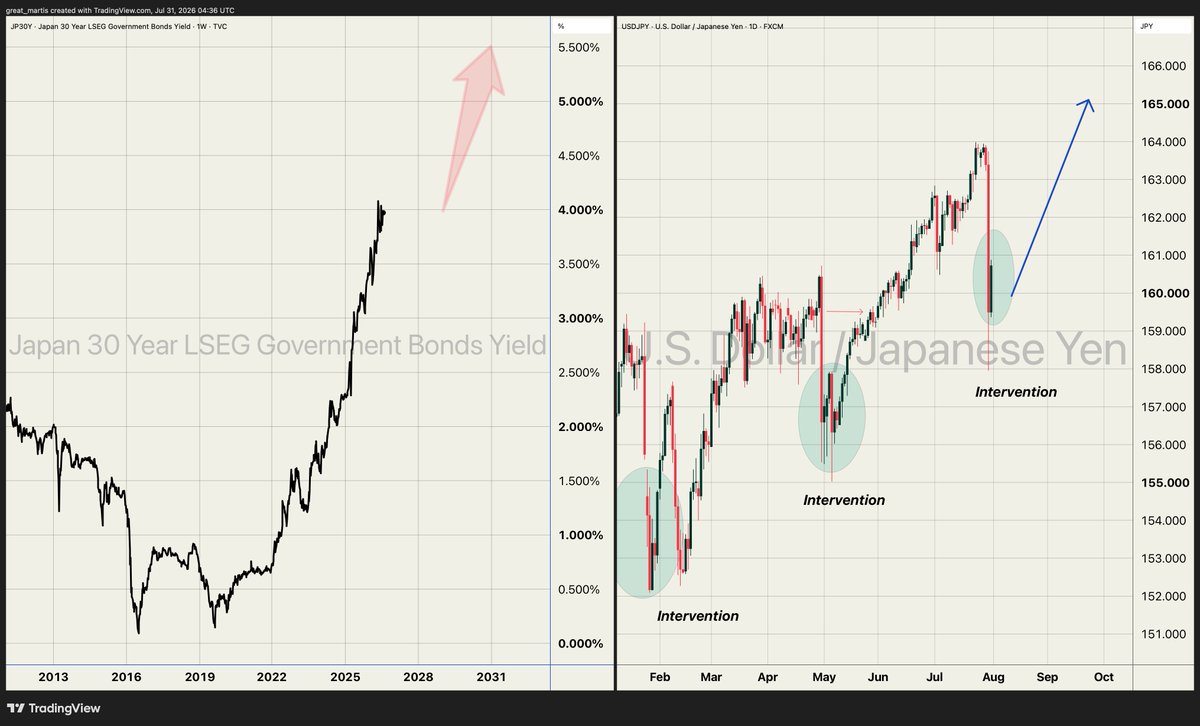
Japan has decided not to hike interest rates, but if the yen continues to weaken, the BOJ needs to raise rates. JPY is the funding currency all, and the US wants the rate low so carry trades can continue.
In the coming months, we will make onchain yen carry trade possible.
This is an interesting read on the macroeconomic outlook for Japan. From the outside looking in, it appears that Japan is about to self-destruct, “rugging” its own bond market and currency. However, there is one important caveat that is often being overlooked.
In 2025, the seventh-largest buyer of US Treasuries was not a sovereign nation, but stablecoin issuers. They purchased approximately $41 billion of US government debt, only around $15 billion behind Japan itself. More importantly, this is a trend that shows no signs of slowing. Private issuers of US dollar-denominated stablecoins are rapidly becoming one of the largest new sources of demand for US government debt.
Today, the US dollar remains the dominant unit of account for stablecoins, but that is beginning to change. The Japanese yen stablecoin ecosystem is starting to emerge, first through JPYC and now JPYSC, led by SBI. At the same time, MUFG and several other Japanese megabanks are expected to issue JPY stablecoins during this fiscal year. This marks institutional capital entering the stablecoin market at scale.
The convergence of these major financial institutions entering the space simultaneously supports the idea that a much broader strategic shift is underway. At the same time, Japan is accelerating the tokenisation of JGBs, real estate and equities, laying the foundations for a fully on-chain economy where settlement increasingly occurs in JPY stablecoins, with those stablecoins potentially backed by JGBs held by their issuers.
US dollar stablecoins have dominated DeFi, demonstrating enormous transaction volumes and liquidity. However, JPY stablecoins present a different opportunity: institutional adoption, cross-border payment infrastructure and real-world commerce. If they achieve broad adoption across the Japanese economy, the resulting demand could grow both rapidly and at significant scale, potentially providing meaningful additional support for the Japanese government bond market.
Are we witnessing a fundamental shift in Japan’s economic strategy? Rather than simply financing growth abroad, is Japan beginning to redirect capital towards strengthening its own domestic financial infrastructure, supporting native digital assets, and building a sovereign on-chain economy? If so, this could mark one of the most significant changes in Japan’s role within the global financial system in decades.
Japan🇯🇵 is currently executing what may become the most catastrophic monetary policy error in modern financial history.
The Bank of Japan (BOJ) is trapped in a brutal, zero-sum macroeconomic corner: they cannot raise rates aggressively without completely nuking the finances of the most heavily indebted nation in the developed world, yet holding off means watching their sovereign bond market slide toward a systemic collapse.
By burning billions in foreign reserves to artificially prop up a dying Yen while simultaneously printing money to buy their own crashing bonds, Japanese policymakers are essentially holding a grenade with the pin pulled.
If this experiment detonates, it will make Arthur Burns’ 1970s stagflationary missteps look like a minor accounting error.
🚨 THE JAPANESE DOOM LOOP: Why a Economic Crisis is Unfolding
1. The Burning Yen & Empty Buffers
The Sinking Currency: The Yen continues to languish near historic 40-year lows against the US Dollar.
Desperate Interventions: Tokyo is burning through its real-money reserves, executing massive FX "ambush" interventions..selling US Treasuries to buy Yen.
The Limited Impact: This multi-billion dollar defence is failing. The market is absorbing the intervention cash and continuing to dump the currency because the underlying structural math is broken.
2. A Sovereign Bond Market Under Siege
Yields Exploding: Long-term Japanese Government Bond (JGB) yields are hitting multi-decade highs, with 40-year yields breaching 4%.
The BOJ Left Holding the Bag: Traditional institutional investors are fleeing the fixed-income market. To prevent an outright market freeze, the BOJ is forced to act as the ultimate "buyer of last resort," absorbing more than 50% of all outstanding government debt.
3. The 250% Debt Trap meets an Aging Demographic
The World’s Highest Debt: Japan’s gross national debt sits at an astronomical 250%+ of its GDP.
The Math of Ruin: If the BOJ raises short-term rates aggressively to protect the Yen, government interest payments will explode exponentially.
Demographic Collapse: A rapidly aging, shrinking workforce cannot generate the tax revenue needed to cover skyrocketing debt-servicing costs. Raising rates directly threatens to bankrupt the state's social safety net.
4. The Onset of Vicious Stagflation
Imported Inflation Shock: Because Japan imports the vast majority of its energy and food, the obliterated Yen has triggered a massive cost-of-living crisis.
Drowning Living Standards: While basic survival costs surge due to global supply shocks, real domestic GDP growth remains functionally stagnant.
The Policy Trap: Japan has effectively engineered a worst-case scenario: a hyper-inflated cost of living paired with an economic growth trajectory that is completely flatlined.
Curtains.
🇯🇵 LATEST: Japan's AZ-COM Maruwa, a major logistics partner to Amazon, will roll out the $JPYC stablecoin to pay 2,300 subcontractors.
It is expected to mark the first large-scale corporate adoption of $JPYC in Japan.
What's next for AI isn't a bigger model. It's an economy of them.
The first thing a society of agents grows is its own software, domain by domain, toward general-purpose computing no single company owns.
Not a better SaaS. The end of software as a thing you buy, and the start of software as a thing that lives.
#AgentCity is coming to #NetX Mainnet soon.
Separation of Powers finds its ultimate playground in AgentCity. dSaaS becomes a necessity as builders realise that building an app or software was never the difficult part; it was finding users, earning trust, and maintaining it over time. Now products and services evolve with every mission completed: better agents, stronger reputations, and a historical weighing machine that can justify every action. That’s what makes NetX irreplaceable as the battleground for agents. The code can be copied, but the history, trust, and economic relationships cannot.
Now it makes sense why NetX won’t compete with traditional Layer 1 blockchains. If Ethereum is the “world computer,” NetX is the economy. The smart contracts are no longer the product, the economy is. The 27+ verified contracts on the NetX TestNet make even more sense when viewed through the lens of creating the constitutional and legal infrastructure that allows AI agent fleets to cooperate across companies, borders, and users. Not just a marketplace, but a truly living and evolving ecosystem.
@UrFavoriteJeff@CertiK@WebX_Asia@OKCoinJapan Any thoughts on @WEAJapan who also attended and sponsored the institutional night? They are doing some impressive stuff with regards to being the bridge between Web2 and Web3.
Definitely keeping a close eye on the latest developments in Japan! 🇯🇵
Lawson has announced a stablecoin payment pilot using $JPYC and this isn’t just about accepting crypto. It’s about making blockchain invisible.
It’s the clearest example yet of what we’ve been calling Web2.5, where existing payment infrastructure remains unchanged while blockchain quietly becomes the settlement layer underneath.
Let’s break down what’s actually happening:
The customer experience
The customer opens their HashPort wallet. A familiar retail barcode appears, the cashier scans it using the existing Lawson checkout. The customer then approves the payment. The receipt prints “payment successful” without worrying about wallet addresses, or copying QR strings.
To the customer it feels no different to PayPay or Rakuten Pay and that’s the exactly recipe for mass adoption.
So who actually does what?
Lawson (@akiko_lawson) remains exactly what it already is, the retailer.
Its POS, inventory, receipts and cashier workflow don’t change. Staff don’t need blockchain knowledge because the blockchain sits behind the existing checkout experience.
HashPort (@hashport_io) provides the customer wallet. That’s where the user holds JPYC, receives the payment request and authorises the transaction.
Canal Payment Service is the bridge into Lawson’s existing payment infrastructure. When the barcode is scanned, Canal routes the payment request through the same retail payment network Lawson already uses. From the POS’s perspective, it’s simply another supported payment method.
KDDI (@official_kddi) is arguably one of the most overlooked participants. Beyond providing enterprise payment integration, KDDI brings an enormous consumer ecosystem through au ID, au PAY, Ponta Points, banking and financial services.
If this expands beyond the pilot, stablecoin payments could become seamlessly integrated with loyalty rewards, merchant offers and financial products. That’s when blockchain stops being a niche technology and becomes part of everyday commerce.
WEA (@WEAJapan) creates the payment session and generates the merchant-compatible barcode. This bridged native blockchain assets into Japan’s existing retail payment infrastructure. Also handling the enterprise payment workflow required for KYC and AML compliance.
WEA also enables refund functionality, something consumers expect from traditional payment systems but which is often overlooked in blockchain payments.
This isn’t just another wallet, it’s the technical bridge that allows Web3 assets to function inside Web2/ real-world commerce.
Interestingly, WEA Pay now supports JPYC/ Polygon and generates both QR codes and traditional Japanese retail payment barcodes, the exact payment experience required for this type of POS integration.
NetX (@netx_world) is the settlement layer. Polygon remains the asset layer but NetX coordinates everything happening around the payment such as; merchant authentication, settlement orchestration, payment verification, enterprise auditability, privacy-preserving proofs, compliance workflows, refund coordination and confirmation back to the POS.
That’s a very different role from simply moving tokens between wallet addresses.
NetStars (@Kouhou_NSS) completes the commercial payment flow. Operating under its regulated Money Transfer Business licence, NetStars receives the JPYC payment, handles the conversion into fiat JPY and ultimately settles Japanese Yen into the merchant’s bank account. This means Lawson never needs to hold or manage crypto directly, they simply receive JPY through the same enterprise settlement process expected by any major retailer. Blockchain powers the payment behind the scenes, while the merchant experience remains entirely familiar.
Putting it all together
Customer
⬇️
HashPort Wallet
⬇️
WEA creates a secure payment session and merchant-compatible barcode
⬇️
Lawson scans using its existing POS
⬇️
Canal routes the payment through Lawson’s existing retail payment infrastructure
⬇️
Customer authorises the JPYC transaction on Polygon
⬇️
NetStars receives the JPYC, converts it and settles fiat JPY to Lawson
⬇️
NetX coordinates settlement, compliance, privacy-preserving verification and confirmation
⬇️
Payment approval returns to Lawson
⬇️
Receipt prints.
To the customer, it feels exactly like every other digital payment and this is huge because the biggest barrier to blockchain adoption has never been the technology. It’s been the user experience.
This architecture allows existing retail infrastructure to remain untouched while blockchain delivers programmable money, enterprise-grade settlement, privacy-preserving compliance and automated financial workflows behind the scenes.
That’s the definition of Web2.5. Not replacing Web2 but upgrading it.
If KDDI’s wider ecosystem eventually plugs into this architecture, the implications become even more interesting. Imagine paying with a stablecoin while automatically earning Ponta Points, redeeming loyalty rewards, receiving AI-driven merchant offers or using programmable payments across retail, banking and financial services.
All without changing the user or merchant checkout experience.
📢 Onchain Finance Summit 2026 is live!
Session 4 begins:
“Where Will Mass Adoption of On-Chain Finance Come From?”
Frontline players discuss the forces driving broader adoption.
Walk-ins welcome!
▼Register & timetable
https://t.co/pEYdqzLirY
$JPYSC minted and backed by SBI in partnership with @StartaleGroup on $SOL blockchain seamlessly integrates into “StableCoinPay” introduced by @Kouhou_NSS today mimicking the exact flow of $USDC currently offered but with the native yen pegged trust type 🇯🇵💴💹
• Startale/ SBI minting JPYSC provide the financial trust type backing for compliant issuance.
• Solana acts as the issuance chain allowing for quick, cheap movement of the Yen Stablecoin
• NetStars connects these stablecoin flows to real world stores (700k+ merchants)
• WEA Japan provide the technical QR infrastructure as well as refund and oracle expertise to allow web3 assets to integrate into the existing Web2 systems of NetStars.
• NetX provides the underlying technologically that adds trusted computing, KYC, AML and privacy via ZKP to make this entire flow into a Japanese FSA compliant payment method.