First of all, remove surcharges (aka MDR) on Fuel and accept it on your side. Then we'll see how fake this hate for MDR becomes.
Don't be a hypocrite!!
Claim
A message is going viral on social media claiming that petrol pump owners in Madhya Pradesh have announced that UPI payments exceeding ₹2,000 will not be accepted in protest against merchant fees and that a “No-UPI Day” will be observed in Indore on September 23, 2026.
Fact
The viral message is fake and misleading. No such restriction on UPI payments exceeding ₹2,000 has been announced by petrol pump owners in Madhya Pradesh. Some individuals who are not even petroleum dealers themselves have made such baseless claims.
In fact, petroleum dealers’ associations have been in regular touch with Ministry officials, and no such “No-UPI Day” strike has been announced or informed. Petrol pump dealers have been at the forefront of promoting digital payments.
#FactCheck #FakeNews #UPI #DigitalPayments #MadhyaPradesh
@HardeepSPuri@PetroleumMin@Secretary_MoPNG@neerajmittalias@sahneyas@ChairmanIOCL
NOT ENOUGH AT ALL.
Classify basis ITR or Proof of Income calculation sheet with monthly income of ₹3L in tier 1 cities, ₹2L in tier 2 and ₹1L in tier 3.
This is same as maximum profit margin of 30% in tier 1 cities, 20% on tier 2 and 10% on tier 3 on ₹10L monthly turnover.
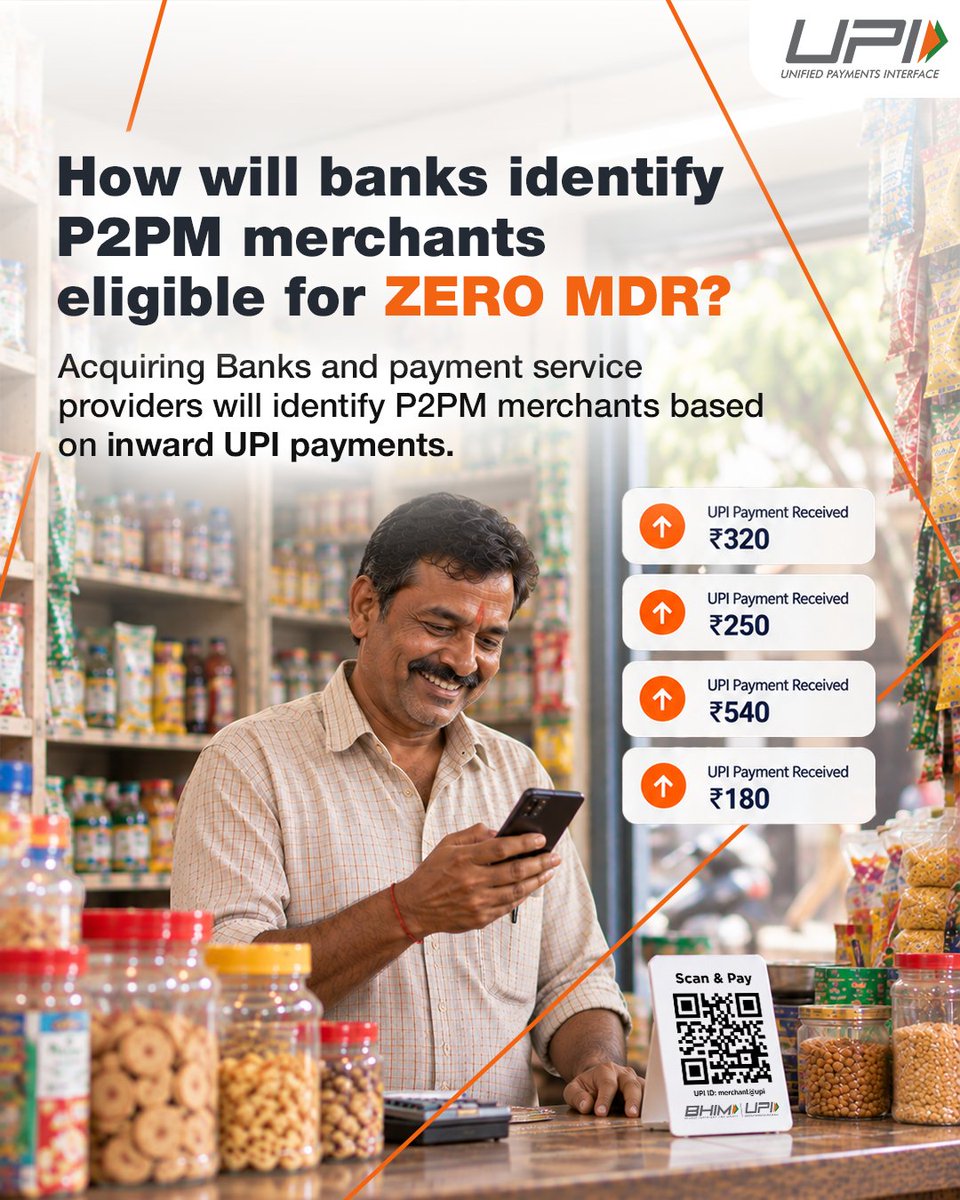
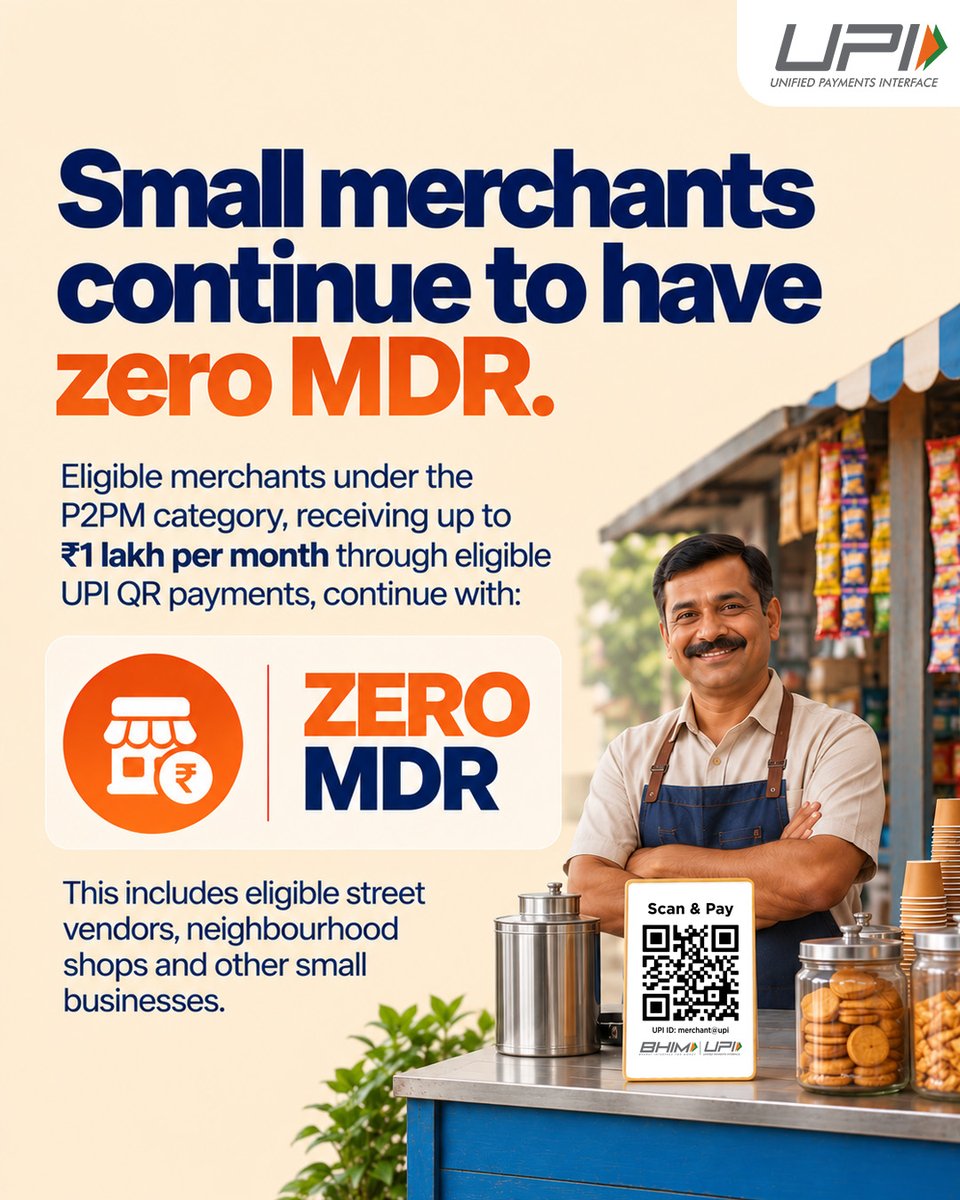
With ZERO MDR for eligible P2PM merchants, how is eligibility determined?
Banks and payment service providers will identify P2PM merchants based on their inward UPI payments.
Merchants receiving up to ₹1 lakh per month remain under P2PM. If inward UPI payments exceed ₹1 lakh per month for 3 consecutive months, the merchant is formally transitioned to the P2M category.
#UPI #UPIChalega #MDR #DigitalPayments
Next, move to usage-based periodic itemized billing like Mobile Postpaid basis volumetric and valuemetric usage instead of charging fees per transaction.
As MDR varies for each transaction, use it only for what it actually represents—discounts, cashbacks, rewards and 0% EMIs.
You guys are nuts if public is going to accept this. For small merchants with 5% to 10% profit margins, you are taking 2% to 4% cost. That's not a small fee.
If Government itself spreads mis-information, I don't know where would I get the cold hard truths and facts.
What does UPI MDR look like in numbers?
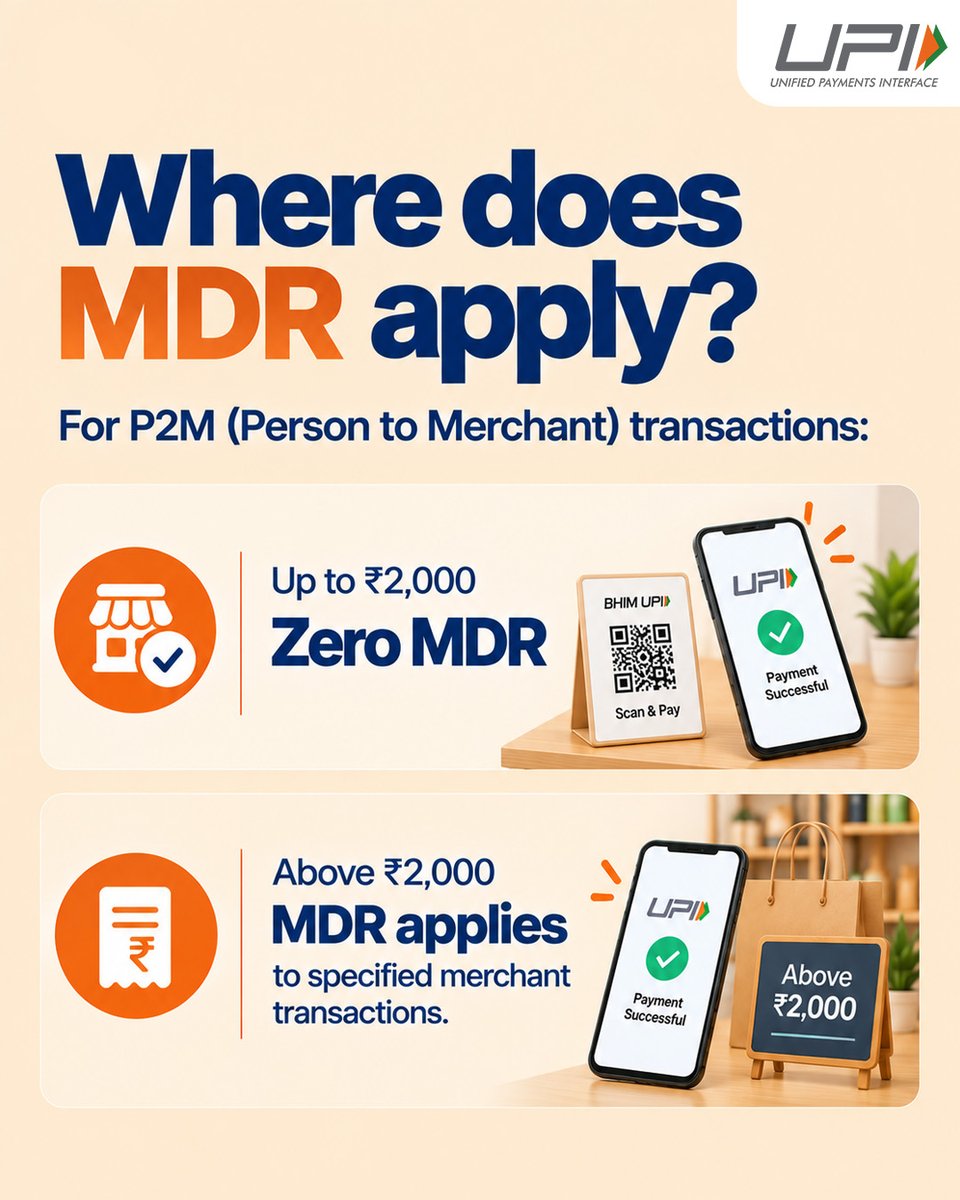
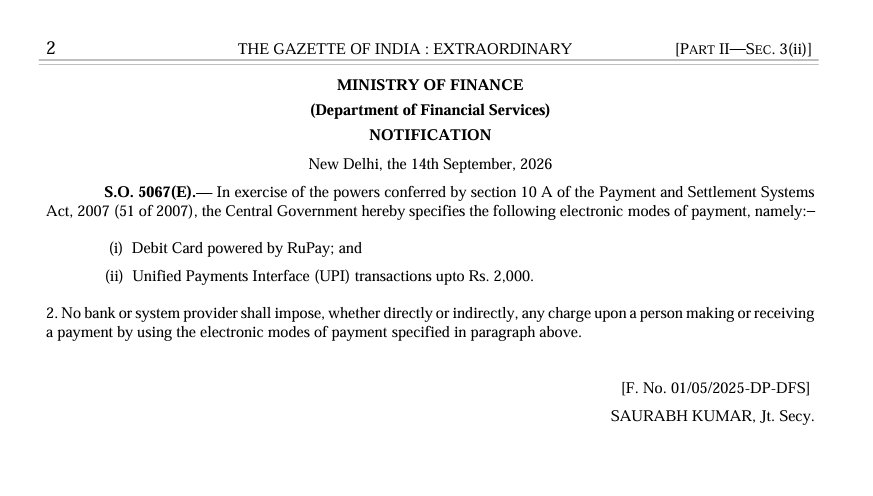
For transactions up to ₹2,000, there is zero MDR — covering around 96% of UPI transactions. For transactions above ₹2,000, UPI MDR is 0.4%, capped at ₹300.
#UPI#UPIChalega#DigitalPayments
What I recommend:
First, waive of all charges for verified small merchants with profit margin less than 10% and monthly turnover less than 10L or yearly less than 1 Crore.
This lets the cash-only economy participate in the digital payments without taking a hit to their wallet.
Don't know why he's so embarrassed to admit China has dictatorship.
It's not that bad. They had awesome economic growth. Great infrastructure. Their Geographies are preserved well.
There are bad things too! Rights violations. Genocide.
But who doesn't? Democracy has it too!!
@Nis_verse@cadburysilk Too much Sugar Syrup (usually Corn Syrup—high in Fructose) and Hydrogenated Vegetable Fat (usually Palm Oil or mixed Edible Oils).
These two ingredients give these foods a proper name: Junk Food. And they burn like plastic-to-charcoal.
Remember Kurkure fiasco. Exactly that.
You can still have per transaction MDR for truly what the name represents: Discounts.
Like instant discounts, cashbacks, rewards and Interest Free EMIs where a certain dynamic percentage cost is added against original transaction to avail these value added services.
It doesn't matter. MDR itself is a borrowed concept from capitalism. It doesn't work well here.
That's why many nations eliminated MDR on their public payments networks.
Move to a usage-based periodic billing like Mobile Postpaid instead.
Few allegations are in the media that the MDR has been introduced because of external pressure. They are giving reference to US Trade Representative (USTR) report of 2026. The USTR report has raised the following two issues:
(i) Inability of US electronic payment services suppliers to participate in the UPI ecosystem, including credit transactions on UPI, on a level playing field with RuPay.
✅ Reality:
The NPCI circular of 15.9.2026 does not allow credit transactions of UPI by any other credit card other than RuPay credit card. There is a clear policy of only allowing RuPay credit card on UPI to enable RuPay credit card to become the preferred choice of credit card amongst users in India.
(ii) NPCI market-share limitation of 30 per cent for third-party application providers (announced November 2020; enforcement date December 2026)
✅ Reality:
Although, NPCI had mandated market share limitation of 30 per cent for third-party application providers in November 2020, however, this mandate could not be implemented because companies other than the market leaders could not compete in absence of self-sustaining revenue model. Introduction of MDR on select high-value transactions will provide a self-sustaining revenue model to smaller companies to compete for higher share in the UPI ecosystem. Thus introduction of MDR has been done with the intention of allowing more domestic companies to expand their operations.
2.Contrary to misleading claims made that MDR has been introduced under external pressure, introduction of MDR on select high-value transactions will enable more domestic companies to operate under UPI. Thus, the action of introduction of MDR is a step in protecting India’s sovereignty in Electronic payment ecosystem.
3.Government of India has promoted RuPay credit and debit cards to show that people have a strong domestic alternative. In order that the RuPay credit cards continue to grow, the debit card has been kept free of MDR.
The allegation that MDR has been introduced under any external influence is patently false and misleading.
#UPI
Remove the MDR altogether. It's not that difficult. I keep saying again and again—MDR is a borrowed concept from capitalism that doesn't work well here.
See the outrage. People already hate it.
MDR on UPI? Let’s clear the air. 🔍
P2P payments remain free. For P2M transactions, zero MDR continues up to ₹2,000, while MDR is applicable to specified merchant transactions above ₹2,000.
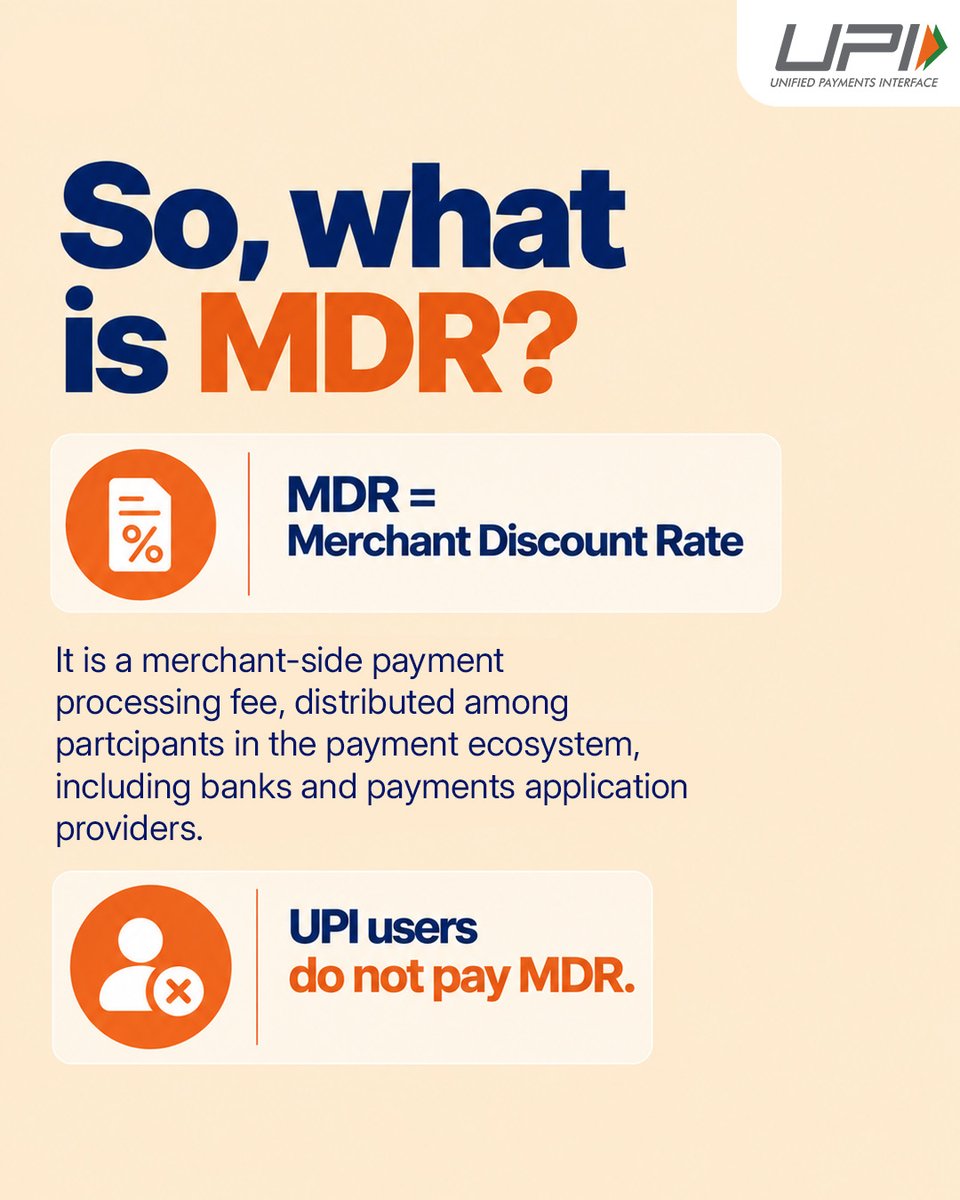
And importantly, MDR is a merchant-side charge — UPI users are not charged MDR.
Swipe through to understand what’s changing, what’s not, and where MDR is applicable. →
#UPI #MDR #DigitalPayments
Then people can attach their preffered operator to their number and purchase their services on top.
- Postpaid or Prepaid.
- Personal or Business.
- Individual, Entity, Family or CUG.
Whatever regular paid services they need.
This lets people keep mobile numbers longer.
That periodic renewal must include a low cost base plan (max ₹1/day) common across all networks to access essential services (government, toll-free, finance and banking) through all modes of communication (Calls, Messages and Data).
What about Postpaid users? Government services and Banking nowadays require Calls, Messages and Data for verification.
First change ownership of mobile numbers from private networks to Individuals with periodic renewals like domain names or IP addresses. This reduces churning...
Need only calling and SMS, without data? Choose a recharge that matches what you actually need.
Find Voice & SMS-only packs in 3 simple steps — open your telecom provider’s app or website, search for Voice-only or without-data packs, and select the option that suits you.
@TRAI These data less packs are more expensive than the regular data bundled packs. Since Banking requires SMS, operators charge exorbitant prices on SMS bundled packs.
The services are subpar. Customer service ignore the Network and billing complaints. Escalation does not respond.
I'm very concerned. Sure it seems like a good deal on the surface, I assure you, the devil is in the details.
Why not remove the MDR altogether and move to usage-based periodic itemized billing like Mobile Postpaid?
This would eliminate the concerns regarding digital payments.
Your UPI Payments Stay Free!
UPI continues to stay free for person-to-person transfers and everyday users, while small merchants remain protected.
Under the updated MDR framework, 96% of merchant UPI transactions remain unaffected, with MDR limited to certain larger merchant payments not charged to customers.
So, the next time you hear “UPI isn’t free anymore,” remember the facts that everyday UPI payments remain simple, seamless and free for users.
#UPI
I'm very concerned. Sure it seems like a good deal on the surface, I assure you, the devil is in the details.
Why not remove the MDR altogether and move to usage-based periodic itemized billing like Mobile Postpaid?
This would eliminate the concerns regarding digital payments.
Small merchants with monthly turnover less than 10L or annual turnover less than 1 Crore should be excluded.
Charging merchants irrespective of their capability to absorb the MDR is stupid. They are going to disable UPI or charge customers which is illegal. It's going to be bad.