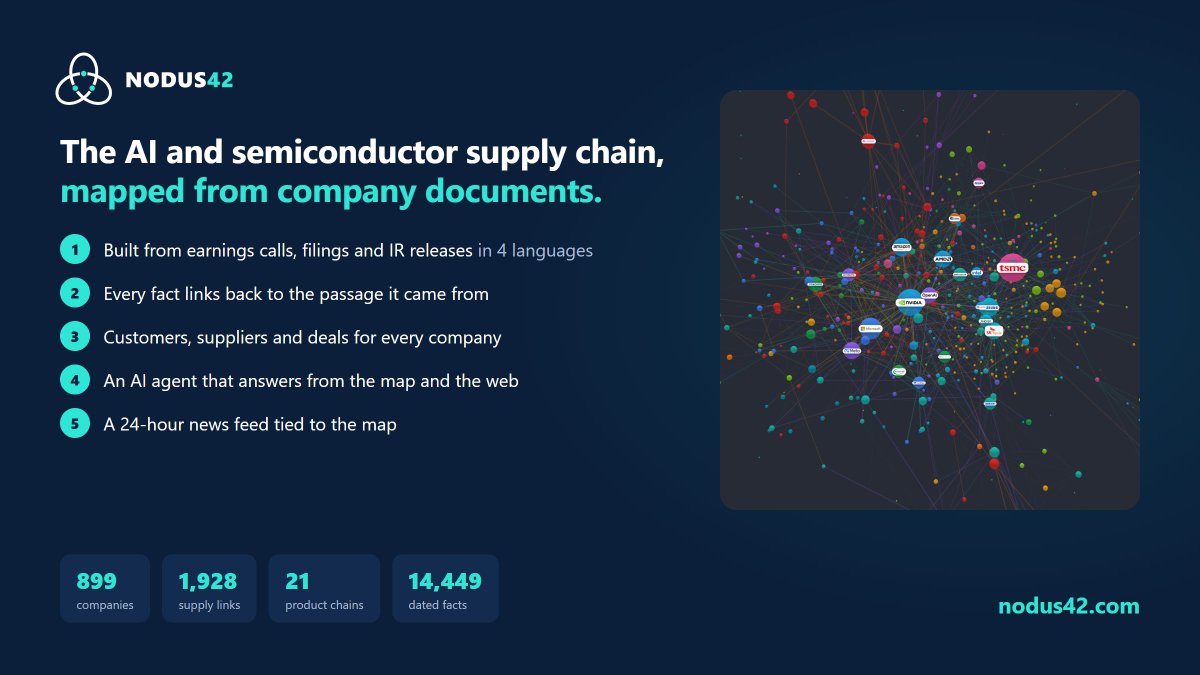
I am happy to showcase my first long-term project: https://t.co/WJD7vbsq1S!
This spring I started mapping the AI and semiconductor supply chain. What it does so far:
1. Built only from company documents: earnings calls, SEC and DART filings, Japanese and Taiwanese exchange disclosures, IR decks and press releases.
2. 899 companies and 1,928 supply links across 21 product chains, with 14,449 dated facts. Every number links back to the passage it came from.
3. Click any company to see its customers, suppliers and the deals on each link, plus which suppliers gain or drop out between chip generations, like Blackwell to Rubin.
4. Ask a question and an AI agent answers from the map and the web, citing its sources.
5. A 24-hour news feed matches headlines to the companies on the map.
Over about six months of building and running it, I've burned through roughly 30 billion tokens.
I'll post what I find in the map here.
https://t.co/YRhz2E8PWP
#Nodus42 #AI #Agent #QQQ #SPY #Semi #Soxx
#Stock #NVDA #AVGO #LITE #COHR #MU #INTC #GEV #MRVL
EMCOR $EME calls itself "the largest specialty subcontractor doing data center work." Data center backlog just doubled to $8.74B... and it's picking customers: "We have more data center constructors that want to work with us than we can serve."
Mostly hyperscalers: "We're not very much into the neocloud market and sort of the speculative of building of data centers."
$EME Q3'26 EARNINGS
Revenue: $5.54B (Est. $5.19B) ; +29% Y/Y, +25.5% organic
Adj. EPS: $9.60 (Est. $8.35) ; +46% Y/Y
FY26 guide raised: revenue $20.6B to $21.0B (Est. $20.35B) ; adj. EPS $34.50 to $35.50, was $32.00 to $33.25 (Est. $33.48)
RPO: record $18.57B, +47% Y/Y ; data centers $8.74B, more than 2x
Data center revenue: mechanical ~+130% (cooling), electrical +68%
Stock: +1.1% today, was +6.5% at the high
1. AI is still the minority
- "today we're probably 65%-70% cloud and 30% AI. That'll probably get to more 50/50 in the future"
- adding "a couple fab shops" in the next two quarters; "the opportunity with a couple of the hyperscalers to build modules"
2. Demand isn't the problem
- Loudoun County: "it's booked for the next two or three years anyway"
- semis: "the first quarter in a while where we actually saw the semiconductor revenues increase"
3. The catch
- mechanical margin 12.1%, -80bp: more GMP and cost-plus jobs, "the contracting method of choice for one of the big customers"
- ~$128M deal amortization in 2027, and no 2027 guide: "You'll figure it out."
→ $FIX last week: backlog $17.8B, +90%. "the governor's really just labor"
→ $TT this morning: tracking 1,700 projects, "over 90% of those are data centers"
My take: the fade from +6.5% is the missing 2027 number. I'd watch the mix: AI only ~30% of the data center work, mostly hyperscalers, and EMCOR still turning customers away.
Everyone's debating the AI capex bubble... and two-thirds of EMCOR's data center work is still plain cloud.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
MYR Group $MYRG says its C&I customers now want crews and material locked in years ahead: "They want to make sure that they have the labor secured to do those projects. And the material is also available."
Some of those projects "go out into 29, 30."
$MYRG Q3'26 EARNINGS
Revenue: $1.26B (Est. $1.15B) ; +32% Y/Y
EPS: $3.82 (Est. $2.98) ; +86% Y/Y
2027 (call): revenue +15% to 18% (Street FY27: +15.5%) ; C&I +18% to 22%, T&D +10% to 13%
Backlog: record $3.68B, +38% Y/Y (incl. the Valley + Comet deals)
C&I revenue: record $704M, +58% ; T&D $555M, +10%
Gross margin: 13.6%, was 11.8%
Stock: +1.0% today
1. Customers are booking ahead
- data center awards in Colorado and California, but "it's not just data centers"
- "I would anticipate some larger projects coming into our backlog" by year-end or the end of Q1
2. Big transmission is a 2028 story
- "that primary build-out will probably start in the 28 timeframe"
- "you'll see a lot more growth in '28 and beyond as it relates to large projects"
3. The catch
- FCF $9M vs $65M a year ago
- "we are seeing payment terms being part of our conversations with customers and contract negotiations more than we were a few years ago"
→ $XEL: two transmission jobs for MYR worth over $200M (July). This morning: a "$70 billion five-year capital investment program"
→ $PWR in July: the big 765kV jobs show up "in the field next year". MYR says the build-out starts in '28
→ $STRL this morning: "we got more opportunity than we have capacity right now"
My take: part of the margin beat is job closeouts, so I wouldn't extrapolate 13.6%. The line that matters is customers reserving labor for 2029-30. That's the electrician shortage showing up in contracts, and MYR sees +15-18% for 2027 before the big transmission jobs even start.
You can't fab an electrician... and customers are reserving them for 2030.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Allegro $ALGM beat, guided above seasonal, bookings +45%... and it's -10% today.
What the call showed: data center grew 4% Q/Q after +32% last quarter. CEO Mike Doogue: "the push out seemed to be related to the delay of some 800 volt programs with the hyperscalers."
$ALGM FQ2'27 EARNINGS
Revenue: $276.9M (Est. $270.9M) ; +29% Y/Y
Adj. EPS: $0.26 (Est. $0.24) ; 2x Y/Y
FQ3 guide: $278M to $288M, +23% Y/Y mid ; EPS $0.25 to $0.29
Data center: record $46M, 150%+ Y/Y, +4% Q/Q
Bookings +45% Y/Y ; adj. GM 51.5%
Stock: -10.4% today
1. The push-out
- "those big programs were pushed out by a quarter or two"
- "These big programs are on the come, and they will happen in the very near future."
- data center still "on track to more than double in FY 2027"
- current sensors: "more than 10 design wins with top Taiwanese power supply providers", incl. "wins across new 800 volt architectures"
2. Same clock at Vertiv yesterday
- $VRT CEO Gio Albertazzi: "2027 being the validation phase, customer validation phase of the full native 800-volt DC and then the deployment into the market in '28"
→ $NVDA 800V DC partners on the map: $POWI (PowiGaN), $STM, $ETN. $MPWR reports tonight
3. Prices go up Jan 1
- "the majority of auto contract renewals and price increases effective January 1st"
- costs too: "wafer supply contracts also begin on January 1. There's some increases there."
- bottleneck: "some constraint at back-end, particularly in test"
→ foundries on file (10-K): $UMC, Tower $TSEM, $TSM. UMC said yesterday 2027 blended ASP is "about 10% year-over-year increase"
My take: nothing here says demand broke. Design wins at a post-IPO record, auto customers at "very low single digit weeks of inventory". The 800V slip is a timing problem and Vertiv is saying the same timeline. The market sold the quarter that didn't show up.
800V is coming... just a quarter or two later than the slides said.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Carrier $CARR data center orders +300% Y/Y. Year to date: more than $3B of data center orders, up ~350%.
And this month it signed one hyperscaler for "more than $3 billion, with a significant portion of that covered by a minimum volume commitment"... which isn't even counted in the $8.5B backlog.
Stock is red anyway.
$CARR Q3'26 EARNINGS
Revenue: $6.26B (Est. $6.10B) ; +12% Y/Y, +15% organic
Adj. EPS: $0.87 (Est. $0.77) ; ~$0.10 of it tariff refunds
FY26 sales guide: $23.8B to $24.0B, was ~$23B (Est. $23.33B)
FY26 adj. EPS guide: $2.85 to $2.90, was ~$2.90 (Est. $2.88)
Orders +35% ; commercial HVAC +60% ; backlog >$8.5B, +60% Y/Y
GAAP EPS -$3.16 on a $3.1B Europe goodwill impairment
Stock: -3.0% today
1. Data centers
- Q3 data center sales >$550M, "exceeding our target"
- 2-3 MW chillers + CDUs. "Effectively a CDU is a mini chiller." Already booking the 5 MW unit
- a few years ago a hyperscaler asked "Are we in the chiller market?" Now two call Carrier "amongst, if not their favorite partner across their entire supply chain"
2. The bottleneck is factory space
- new Fort Worth site will "effectively more than double our capacity in the Americas", first deliveries late summer 2027
- until then Carrier has been "constraining ourselves" on other work like semiconductor fabs
3. Same product, same week (pulled from nodus42)
→ $VRT: Q3 orders "more than 100% up year on year, organically"
→ $JCI: orders +44%, "Backlog grew 43% to a record $23 billion"
→ $TT today: applied bookings "up over 40%", backlog $12.5B
My take: the market is trading the resi miss (price realized "low single-digits", CSA margin guide cut to ~19%) and a refund-driven beat. Fair. But the data center book is LTA-backed, margin accretive and capacity-short, with $3B+ sitting outside backlog.
Chips get the headlines. Every rack still needs a chiller... and Carrier says it can't build them fast enough.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Mastercard $MA on how AI agents should pay: "We are not supporting solutions that take a one-time VCNs out there as you're fronting a transaction."
So no one-time virtual cards in the middle of an agent checkout. It wants agent payments "fully tokenized all the way through". And this quarter it signed a broad partnership with OpenAI that "includes the use of Agent Pay and goes well beyond."
$MA Q3'26 EARNINGS
Revenue: $9.81B (Est. $9.66B) ; +14% Y/Y
Adj. EPS: $5.31 (Est. $5.17) ; +21% Y/Y
FY26 guide: net revenue growth at "the high end of low double digits" (currency-neutral), unchanged
Value-added services +19% ; payment network +11%
GDV +7% ; cross-border +11% ; switched transactions +9%
Stock: +4.3% today
1. Agentic commerce
- agentic transactions "ramping up at impressive weekly growth rates", but "the numbers are not yet significant in the grand scheme"
- the bigger prize per CEO Michael Miebach: "an entirely new addressable market of micro-transactions"
2. The fine print
- some of the beat is timing: services projects and "the signing of deals moving from Q4 to Q3". CFO: "You will see a similar offset in Q4."
- cross-border card-not-present ex travel: 15%, was 20% in Q2
3. On file (pulled from nodus42)
→ Mastercard → OpenAI: Agent Pay plus "joint services growth, and AI transformation"
→ Mastercard → $SHOP: Agent Pay + network tokens in Shop Pay
→ $NET's CFO in Sept named $V and Mastercard among its agentic payment partners
→ July: Agent Pay for Machines lets AI agents buy "APIs, compute, data, content at machine speed"
My take: for the AI map Mastercard sits on the spending side, not the build. Agentic is still small... but ruling out VCNs now is about setting the rails before the volume shows up. Agents paying per API call and per GPU hour is the micro-transaction market it means.
Agents are going to need a way to pay. Mastercard is writing the rules early.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
AI is now squeezing the defense supply chain...
$LHX on why its radio + EW segment grew just 3%: PCB laminates "2 or 3 tiers down in the supply chain" were "capacity constrained largely because of the pull on AI and data centers for microelectronics." The Department of War called those suppliers to get L3Harris priority.
$LHX Q3'26 EARNINGS
Revenue: $6.06B (Est. $5.94B) ; +7% Y/Y, +9% organic
EPS: $3.28 (Est. $2.95) ; +33% Y/Y
FY26 EPS guide: $12.25 to $12.35, was $11.80 to $12.00 (Est. $11.90)
Orders: $19.3B ; book-to-bill 3.2x (missiles 11.8x)
Backlog: $53.2B, was $36.3B a year ago
Stock: +7.4% today
1. Missiles booked $11B in one quarter
- THAAD $6.3B + PAC-3 MSE $4.7B propulsion, seven years each
- "we plan to triple our THAAD solid rocket motor deliveries in 2027 as compared to 2026"
→ $LMT is the prime on both; L3Harris makes all THAAD motors (per nodus42)
2. AI took the materials (and the crews)
- July: comms would "ramp up in the second half". Q3: +3%, so Q4 carries it
- CFO Ken Sharp in Sept: "the people that are buying all the stuff for AI are now impacting your radio capability"
- Even crews: "we have to go work someplace else because it's a data center"
- Fixed now, they say: no "material impact" in Q4
→ $TTMI last week: CCL / T-glass lead times "sometimes 24 weeks", and "the customers will take these price increases"
→ $AVGO: "We were early in being able to lock up T-glass"
→ AI-board laminate makers on file: Elite Material (TW 2383), Panasonic (6752.T) → $TTMI
3. What to watch
- 2028 FCF framework cut to $3B from $3.5B
- $12.3B of the $20.0B missile backlog is unfunded
My take: missiles are the headline, the laminate line is the one I'd keep. When the Pentagon has to phone laminate suppliers for priority, the CCL / T-glass squeeze is real.
Military radios waiting behind AI servers for laminate... what a crazy bottleneck that's unfolding.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Sterling $STRL raised its FY26 guide for the 3rd time this year: adj. EPS now $21.70 to $21.96, was $13.45 to $14.05 in February.
Signed backlog slipped Q/Q. CEO Joe Cutillo: "I wish somehow we could get out of backlog altogether because it is really a meaningless number for us."
$STRL Q3'26 EARNINGS
Revenue: $1.56B (Est. $1.19B) ; +127% Y/Y, 70% organic
Adj. EPS: $7.58 (Est. $6.17) ; +118% Y/Y
FY26 revenue guide: $4.63B to $4.73B, was $4.00B to $4.15B (Est. $4.12B)
FY26 adj. EPS guide: $21.70 to $21.96, was $19.70 to $20.30 (Est. $20.03)
E-Infrastructure (data centers, fabs): $1.30B, +212%
Signed backlog: $4.14B, was $4.33B ; scoped work ~$8B (+~90%)
Stock: opened -8.7%, now +2.0%
1. Why backlog undersells it
- "I could theoretically book a billion-dollar project and put $10 million in backlog"
- "thousands of acres of land that is permitted, powered, and ready to go" ... "over five years of work for us"
2. The bottleneck is Sterling's own capacity
- "we got more opportunity than we have capacity right now"
- electricians: "we were hiring roughly 80 a week, just in the state of Texas"
- "We're passing on the pharma plants right now just because we don't have the capacity to go after them."
3. When a hyperscaler borrows
- "I look at that as that's more money they're going to spend on us to build more stuff"
→ $META: the Pacific Northwest move started as "a pilot with Meta" (May call)
→ $MU: "We got pulled into the Micron plant" in Idaho after running months ahead on the New York fab job
→ $PWR and $WCC reported the same build this morning: backlog +$10.3B, +80%
My take: the market grades Sterling on signed backlog. Management says it's the wrong number. Guide up ~59% at the midpoint since February, and the CEO is turning down work for lack of crews. The constraint is labor, not demand.
Site work is the first shovel on every campus... Sterling is short on shovels.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Wesco $WCC backlog growth, last four quarters: +19%, +22%, +60%, +80% Y/Y. Its data center-heavy CSS unit: backlog up ~140%.
And CEO John Engel says the hyperscaler capex headlines reach Wesco late: "where we play in the value chain there is a meaningful time delay."
$WCC Q3'26 EARNINGS
Revenue: $7.23B (Est. $6.87B) ; +17% Y/Y
Adj. EPS: $5.77 (Est. $4.69) ; +47% Y/Y
FY26 sales guide: $26.8B to $27.0B, was $25.9B to $26.3B (Est. $26.18B)
FY26 adj. EPS guide: $18.00 to $18.50, was $16.00 to $17.50 (Est. $16.91)
Data center sales: $1.8B, +55% Y/Y ; ~$6B TTM, ~23% of sales
October sales per workday: up high teens Y/Y
Stock: +4.7% today
1. Where Wesco sits in the build
- Engel: "we're not doing Nvidia chips" ... "We're doing everything else wrapped around it."
- "The first thing that has to be done is the overall power solution. And then as the construction build cycle progresses, it's gray space moving to white space."
- Slide: time to power 3-5 years, then 1-2 years of construction. Backlog "can be a year to two years out"
2. Not just hyperscalers
- Data center solutions +~40%, led by hyperscale and MTDC. EES data center sales +100%+
- "enterprise AI investment is expanding well beyond the hyperscalers"
3. The grid side
- Utility + broadband backlog +~90%. "utilities become a secular growth industry"
→ Hyosung Heavy (KR 298040): its H1 filing lists Wesco at 7% of its US transformer plant's end sales, next to $AEP and Eversource $ES
→ $PWR this morning: +$10.3B of backlog in one quarter, $63.7B total
My take: backlog +80% on sales +17% is the line. That's work that ships over the next year or two, in Engel's order: power first, then gray space, then white space. Wesco sells into all of it except the chips.
Headlines price the GPUs. Wesco books everything wrapped around them... a year later.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
$TT is tracking 1,700 megaprojects, up from 1,400 last quarter... and "over 90% of those are data centers". Over $8B of its $12.5B backlog ships in 2027 or later.
Stock still -4.4%. Americas commercial bookings slowed to "up low double digits" after +50% in Q2.
$TT Q3'26 EARNINGS
Revenue: $6.76B (Est. $6.50B) ; +18% Y/Y, +16% organic
Adj. EPS: $4.86 (Est. $4.74) ; +25% Y/Y, incl. ~$0.10 tax timing
FY26 guide: organic revenue ~+11%, was ~+9% ; adj. EPS $15.20 to $15.30 reaffirmed (Est. $15.29)
Bookings: $7.25B, +20% organic ; book-to-bill 107%
Backlog: $12.5B, +73% Y/Y (Q2: $12.1B)
Stock: -4.4% today
1. Data centers, years out
- 2028 backlog is already building and "could be over $1 billion"
- Applied revenue growth "exceeding 60%" in the Americas
- Stellar (modular chiller plants): "Stellar today is predominantly almost 100% data centers"
2. Why it's down
- CEO Dave Regnery: "We're not concerned about orders slowing. And in fact, the pipeline continues to grow."
- Organic leverage guide cut to "low 20s" from 25%+: lighter price, and suppliers of "fans, coils, heat exchangers" are stretched
- A Tier 4 capacitor supplier hit by the UFLPA list left 3 or 4 plants short of drives + motors for a couple weeks
3. Read-through (pulled from nodus42)
→ cooling peers this week: $VRT Q3 orders "more than 100% up year on year, organically". $CARR: "Data center orders increased 300%". $JCI: "Orders increased 44%"
→ Trane is buying Cancoil, a coil supplier where "We represented roughly 40% of the volume"
→ $DUOT: "Trane builds our chiller plant, which is a closed loop system"
My take: the order slowdown is lumpy data center jobs against a +50% Q2 comp. 1,700 megaprojects and $8B+ booked for 2027+ don't read like demand rolling over. The constraint is supply, and Trane is literally buying its coil maker to fix it.
The chiller isn't the bottleneck... the coil inside it is.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Merck $MRK +5% today... and the CEO says the $70B mid-2030s revenue target is going UP: "we expect now to be raising that number"
Not in that $70B yet: the Terns deal and the PD-1 VEGF. The Keytruda cliff, per the CFO, is "more of a hill".
$MRK Q3'26 EARNINGS
Revenue: $18.09B (Est. $17.33B) ; +5% Y/Y
EPS: $2.49 (Est. $2.09), incl. a $0.12 SciBrunch charge
FY26 revenue guide: $66.8B to $67.3B, was $66.3B to $67.3B (Est. $67.04B)
FY26 EPS guide: $2.77 to $2.82, was $2.66 to $2.76 (Est. $2.65), after $6.05/sh of one-time deal charges
Keytruda $8.60B, +6% ; Winrevair $694M, +93%
Stock: +5.2% today
1. The cliff
- CFO Caroline Litchfield: "we see the KEYTRUDA LOE as really more of a hill on the overall revenues of our company"
- 2027: "moderate top-line growth" with "more than $2 billion of headwinds" from generics
- the beat is flattered: $550M of Q3 sales was purchase timing, tax rate 10.9%
2. The cancer vaccine supply chain (pulled from nodus42)
- ESMO: intismeran + Keytruda, "the first Phase 3 validation of a therapeutic cancer vaccine"
→ $MRNA designs and makes every dose, "50-50 cost in for everything"
→ Moderna CEO Stéphane Bancel: "It's not a scale up like you have in traditional medicine. It's a scale out"
→ his bottleneck: "I think the biggest bottleneck is going to be the hospital."
→ $TEM runs tumor sample logistics + sequencing for each patient's vaccine (Oct 7)
3. Compute
- unlike $LLY and $BMY, nodus42 has no compute deal on file for Merck yet. Jensen did put "Merck" on his Sept list next to Lilly and BMS
My take: Q3 is noise (timing + tax). The stock is trading the post-Keytruda story, and the vaccine is the piece I'd watch: one batch per patient, sequenced, designed and made to order. That's a logistics chain, not a plant.
Keytruda was one drug for millions. Intismeran is one batch per person... a whole new supply chain to map.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
$CAT's backlog is a record $78B, about 2x a year ago. Large engines and turbines are now booked "into late 2028, into 2029", some turbine orders into 2030.
CEO Joe Creed on the call: "there is no slack in the system."
The stock is down 8%.
$CAT Q3'26 EARNINGS
Revenue: $20.68B (Est. $20.69B) ; +17% Y/Y
Adj. EPS: $7.20 (Est. $7.03) ; +45% Y/Y
FY26 guide: sales up "mid to high teens", unchanged (Est. +18%)
Backlog: $78B, +96% Y/Y (Q2: $72B)
Power & Energy: $8.78B, +18% ; 24.4% margin
Power gen sales to users: +75% Y/Y
Stock: -8.1% today
1. Booked out for years
- "we're now taking some large reciprocating orders as far out as 2029 and turbine orders into 2030"
- "Typically, we have only had 12 months or less line of sight to our backlog"
- "What we are hearing from our customers is they still want more from us if we can get them more power."
- Large engine capacity going to "nearly three times the 2024 level by 2030"
2. So why is it down?
- Q4 guide is "moderate sales growth", and Power & Energy "is really paced by capacity and timing of customer deliveries"
- "We had a test cell go down for a little bit in the third quarter"
- Backlog adds this year: +$12B, +$9B, then +$6B. Creed: "you cannot just look at one metric like backlog growth in a quarter or book-to-bill in a quarter"
3. Read-through (pulled from nodus42)
→ $GEV yesterday: "we shipped 5 GW while signing 11 GW of orders and slot reservation agreements"
→ $VRT's 10-K names a Caterpillar partnership in distributed power + backup
→ Range Intelligent Computing (SZ 300442) says the gensets at all its data center parks are mainly Caterpillar
My take: a sold-out business priced like a cyclical. The tape is trading a soft Q4 comp and a smaller backlog add, while the cap on CAT's power growth is its own factories, not demand.
When a $78B backlog is limited by test cells... demand isn't the problem.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Entegris $ENTG backlog: +35% in one quarter, more than 2x a year ago. Adj. gross margin 48.9%, the highest in 25+ years.
And CEO Dave Reeder: "These strong results are independent of any material pricing benefit."
$ENTG Q3'26 EARNINGS
Revenue: $1.006B (Est. $925M) ; +25% Y/Y
Adj. EPS: $1.23 (Est. $1.02) ; +71% Y/Y
Q4 guide: $1,025M to $1,055M ; adj. EPS $1.32 to $1.40
FY26 at the guide: $3.73B to $3.76B (Est. $3.58B)
Adj. GM: 48.9%, +530 bps Y/Y
APS (filtration + purity) $605M, +31% ; MS (materials) $404M, +16%
Stock: +1.8% today
1. The backlog
- "book-to-bill remains significantly above one, with backlog up more than 35% sequentially and more than doubling compared to last year"
- capex-tied revenue went "from a modest decline at the beginning of the year to more than 35% growth in the third quarter"
- unit-driven revenue "accelerated from approximately 6% in the first quarter to 20% in the third quarter"
2. Price comes later
- CFO Sukhi Nagesh: "To the extent there's any pricing actions, it'll be on new orders, but not on existing backlog."
- wins: "a significant EUV filtration application at 2 nm" + "multiple CMP plans of record in the quarter with leading memory providers"
→ $TSM was 16% of 2025 sales (10-K). Taiwan +41% Y/Y in Q3
3. Pinch points
- "If there's an area where I wish we had a bit more capacity, it is pads."
- mainstream is capped: "memory's incredibly tight", "until more capacity comes online for memory"
- on the cycle: "the biggest part of units are more like 2028, 2029, not 2027"
→ CMP peers on the map: Fuso Chemical (4368.T) silica adopted for TSMC N2, Dongjin Semichem (005290.KQ) slurry for Samsung (005930.KS)
My take: the backlog doubled at old prices, and new prices only hit new orders. So the 25+ year high margin came before any pricing, not because of it.
Best margin in 25+ years... and they haven't even started pricing.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Linde $LIN, the gas company that builds the plants next to fabs, said today it is "a bit more selective around some of the memory projects"
Why: memory "historically has been on a shorter cycle", which doesn't fit "the long-term contracts that we prefer". The focus is logic. Electronics was still its fastest-growing end market, +15% Y/Y.
$LIN Q3'26 EARNINGS
Revenue: $9.40B (Est. $9.16B) ; +9% Y/Y
Adj. EPS: $4.59 (Est. $4.52) ; +9% Y/Y
FY26 adj. EPS guide: $17.82 to $17.92, was $17.70 to $17.90 (Est. $17.88)
Q4 adj. EPS guide: $4.40 to $4.50, +5% to 7% Y/Y
Project backlog $11B ; sale-of-gas $7.9B (record $8.1B in Q2)
GAAP EPS $3.66 (-11%) after a $425M restructuring charge
Stock: -1.2% today
1. Fabs carry the print
- Electronics +15%, was +10% in Q1 and +18% in Q2
- ~$2B of electronics projects under construction in the U.S., Korea and China, "staggered startups over the course of the next two, three years"
- pipeline "including with TSMC here in the U.S."
- U.S. packaged gas up low teens "from construction and data center activity"
- helium: "there are not enough tanks in the system" to reroute Qatar's supply around Hormuz
2. On file (pulled from nodus42)
→ Linde plants feed $TSM Arizona: "Fab 1 fully utilized. Fab 2 kind of ramping up." (Feb call)
→ NAND fab gases for $MU, Samsung (KS 005930), SK Hynix (KS 000660)
→ peer $APD in July: "close to two-thirds of our opportunities or more than that are in the electronic space"
My take: ex-electronics this is a slow industrial with flat margins, a Lincare cleanup and "absolutely no catalyst" in Europe. The memory line is the tell. The company that signs a long contract before it pours concrete next to a fab still doesn't trust memory's cycle... while Samsung calls 2027 tighter than 2026. Logic gets the plants first.
Every new fab needs a gas plant next door. Linde has ~$2B of them under construction.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
$XEL says the 4 GW of data centers it plans to sign by the end of 2027 would need "somewhere in the neighborhood of 10 to 12 gigawatts of generation"... and none of it is in the new $70B capex plan.
That plan was $34B three years ago. And it "does not depend on contracting any new data center customers."
$XEL Q3'26 EARNINGS
Revenue: $4.17B (Est. $4.30B) ; +6.6% Y/Y
Ongoing EPS: $1.52 (Est. $1.39) ; +23% Y/Y
FY26 EPS guide: narrowed to $4.10 to $4.16 (Est. $4.13)
FY27 EPS guide: $4.48 to $4.62 (Est. $4.54)
5-yr capex: $70B for 2027-31, was $60B for 2026-30
2027 electric sales: ~+5% weather-normalized, vs ~3% in 2026
Stock: +2.3% today
1. The data center math
- 1 GW to sign by end of 2026, 3 GW more by end of 2027. Already in "active ESA negotiations right now with a large counterparty"
- 10 to 12 GW of generation for 4 GW of load is 2.5x to 3x, "because we bring a clean energy portfolio to serve them"
2. SPS (Texas / New Mexico) is the hot spot
- $25.8B of the $70B, the most of Xcel's four utilities
- "We already have three contracts with hyperscalers down there"
- "over $8 billion of transmission spend in SPS", driven by 765kV lines
3. Who's on file (pulled from nodus42)
→ HD Hyundai Electric (KS 267260): 765kV transformers + reactors for Xcel, KRW 173.0B, through Aug 2029
→ $GEV turbine alliance. In Feb Xcel had "24 gas CTs on order across our vendors"
→ $PWR (10-K customer), $MYRG (two Xcel transmission jobs, over $200M)
→ $GOOGL's Minnesota data center; Fermi $FRMI's Project Matador sits on SPS
My take: the base plan already runs ~11% rate base growth with zero new data centers in it. Every GW signed adds 2.5 to 3 GW of generation that nobody has modeled yet.
The utility is the slowest part of the AI buildout... and it just told you the next leg isn't in the numbers yet.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
From the call... the line I'd watch is how $MSFT pays for all this. Amy Hood: "There is a form of financing called leasing, and we have been using that one as a vehicle." On debt: "we have not yet, I would say, tapped that."
And from her script: "we will access additional sources of funding when we believe it is attractive to do so."
Also new:
- "Roughly three quarters of our CapEx was for short-lived assets, primarily CPUs and GPUs, including higher memory and storage costs"
- Dock-to-live times down "about 20% quarter-over-quarter for new GB300s" in its biggest regions ($NVDA)
- RPO due beyond 12 months "increased 98%", helped by "a large Azure commitment this quarter"
- Satya on selling bulk capacity: "four customers who buy a lot of capacity from you, and you can show a few quarters of growth, and that is not a business as far as I am concerned." But "As long as the pricing is right, we may sell them some."
- Copilot daily users "up nearly 50% quarter-over-quarter and over 5x year-over-year". No seat count this time
- Windows OEM -27%, "Inventory levels remain elevated"
Leases carried the build so far... and Hood just put the bond market on the table.
$MSFT guided capex "over $50 billion". It spent $45.2B... because "some third party capacity deliveries we expected in Q1 were delayed."
Azure still grew 48% on a ~45% guide. And December is guided to 49-50%: "Customer demand continues to exceed available supply."
$MSFT FQ1'27 EARNINGS (Sep qtr)
Revenue: $92.3B (Est. $90.7B) ; +19% Y/Y
EPS: $4.89 (Est. $4.73)
Azure: $33.2B (Est. $32.3B) ; +48% Y/Y
Capex incl. leases: $45.2B (Est. $50.7B)
Commercial RPO: $677B ; +73% Y/Y, flat vs June
Dec-qtr guide: $96.0B to $97.1B (Est. $95.6B) ; Azure +49-50% cc (Est. 45.1%)
Stock: +3% after hours
1. Azure accelerated on the fleet it already had
- CFO Amy Hood: 48% "even with the 3P capacity delays noted earlier, driven by Foundry and improved CPU monetization"
- "We had higher token pricing than we expected in the quarter"
- 24 new data centers this quarter, and "We have docked our first NVIDIA Vera Rubin GPUs"
2. The capex moved, it didn't shrink
- Calendar 2026 capex now ~$170B, was ~$175B in July, "due to the 3P capacity delays"
- Dec quarter "over $50 billion", then H2 accelerates from CPUs "inclusive of higher memory and storage costs", GPUs and "the 3P capacity deliveries that shifted to H2"
3. OpenAI, from the 10-Q
- $10.0B of revenue from OpenAI in one quarter, ~11% of the total. All of FY26 was $24.1B
4. Third-party capacity on file (pulled from nodus42). Microsoft didn't say who slipped
→ Nscale: up to ~$43.8B through 2033, 66K+ Vera Rubin GPUs at Sines from late 2027
→ $NBIS: up to $17.4B, says every Microsoft tranche was delivered by August
→ $IREN: $9.7B over 5 years, Horizons 2-4 at Childress targeted for calendar Q4
→ $CRWV: Microsoft was ~67% of its 2025 revenue
→ Anthropic: its S-1 commits at least $44.9B to Microsoft, Nov 2026 to May 2033
My take: the Azure beat came from squeezing more out of the existing fleet, and the capex miss is timing. The neocloud GPUs were late, not cancelled, so that spend lands in Jan-Jun 2027 on top of a memory bill Hood now names out loud.
Capex $5B light because the GPUs showed up late, and Azure still accelerated... so much for the AI slowdown.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Bristol Myers $BMY is buying the whole AI stack: $NVDA Vera Rubin NVL72 racks, Claude across the company, $137.5M of $TEM oncology data. Today the CEO put targets on it: "cutting in half the time from drug target selection to lead molecule identification"
Beat, raise... stock flat.
$BMY Q3'26 EARNINGS
Revenue: $13.07B (Est. $12.73B) ; +7% Y/Y
EPS: $1.35 (Est. $1.22), incl. a $0.58 IPRD hit
FY26 revenue guide: $49.75B to $50.25B, was $49.0B to $50.0B (Est. $49.90B)
FY26 EPS guide: $6.35 to $6.55 (Est. $6.54), incl. $0.60 of IPRD
Growth Portfolio $7.66B, +12% ; Eliquis $4.69B, +25%
Gross margin 68.4%, was 72.9%
Stock: flat today
1. The AI stack (pulled from nodus42)
→ NVIDIA, July: "Vera Rubin NVL72, for running predictive models at scale and training large AI models on BMS's own data"
→ Anthropic, May: Claude across research, clinical, manufacturing, commercial and corporate
→ Tempus, Oct 14: $137.5M data deal through 2031, used with Pathos AI's Foundry
→ $SDGR: Bunsen deployed across BMS research
- July call, CEO Chris Boerner: "demand for compute has grown alongside the scale and maturity of our AI capabilities"
2. Today's call
- Boerner's targets: "a 20%-30% reduction in drug testing timelines"
- CMO Cristian Massacesi on AI: "This is now a concrete factor that we can start to measure."
- "eight growth portfolio medicines, each annualizing over $1 billion based on Q3 sales"
3. The overhang
- Eliquis LOE in Europe hits Q4. CFO David Elkins: "we anticipate that $1.5 billion-$2 billion step down in 2027"
My take: the print is fine, the stock is waiting on 2027 (Eliquis cliff, milvexian AFib in Q1). The AI spend is the part nobody prices yet. If those targets show up as faster INDs, BMY is a pharma with a compute moat... that's a different multiple.
Hyperscalers, neoclouds, sovereigns... and now a drug company buying NVL72 racks.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Silicon Motion $SIMO CEO on today's call: "in semiconductor industry today, everything is in shortage, right? From substrate, from material, from wafer, from NAND, from memory, from even test capacity."
Next line: "We secured our 2027 wafer with TSMC primarily." Plus test, assembly and substrate. Then 2027 revenue guided up at least 40%.
$SIMO Q3'26 EARNINGS
Revenue: $560.2M (Est. $529.1M) ; +131% Y/Y
EPS: $4.35 non-GAAP (Est. $3.33), was $1.00
Q4 guide: $588M to $616M, +111% to 121% Y/Y
FY26 at the guide: $1.94B to $1.97B (Est. $1.87B)
GM: 53.7%, was 48.7%
Ferri + boot drives +75% to 80% Q/Q, >40% of revenue
Stock: +4.7% today
1. 2027
- CFO: "Our strong backlog across all of our businesses gives us confidence that we can grow revenue by at least 40% next year"
- that's $2.7B+. Street FY27 was $2.43B
2. NAND makers walking away
- release: they're "pulling back from certain consumer-oriented segments, including PCs, mobile devices, IoT, automotive and enterprise boot drives"
- near-CPU boot drives with DRAM: "a very, very big gap of shortage supply for 2027", ramp 2H27
→ on file (20-F): Kioxia (285A.T) 12% of 2025 revenue, $MU 10%
3. AI boot drives
- $NVDA Rubin, per IR in Sept: "BlueField-4 is integrated. You have to buy it, so it's 100% attached". BlueField-3 was ~20-30%
- customers now "more than just GPU customer and our TPU customer"
→ $TSM primary foundry. Assembly + test at $ASX, Powertech (https://t.co/JKAGW7u0fU), KYEC (https://t.co/mq5hb2VX4V)
4. The catch
- "We see the Q3, Q4 NAND pricing are rather similar."
- eMMC + UFS -10% to 15% Q/Q, SSD controllers "flat to slightly down" in Q4
→ $SNDK reports tonight
My take: the shortage is squeezing the phone + PC half and feeding the enterprise half... and enterprise is winning. NAND makers chasing 8TB and 16TB SSDs are leaving the 1TB boot drives to Silicon Motion.
Everything is short... so whoever booked 2027 wafers early gets to say 40%.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
Eli Lilly $LLY just sold $16.1B of Mounjaro + Zepbound in ONE quarter... and the CFO says they're still only reaching about 1 in 10 of the US patients they could.
$1.8B over the Street, guide raised $5.5B at the midpoint.
$LLY Q3'26 EARNINGS
Revenue: $24.40B (Est. $22.62B) ; +39% Y/Y
EPS: $7.48 (Est. $6.61) incl. a $4.57 IPR&D charge. Ex that: $12.05, +56% Y/Y
FY26 revenue guide: $91B to $92B, was $85B to $87B (Est. $88.74B)
FY26 EPS guide: $35 to $36 (Est. $34.46)
Mounjaro $10.72B (+65%) ; Zepbound $5.35B (+49%)
Volume +53%, price -15%
Stock: +6.3% today
1. Volume is eating price
- CFO: "Excluding these adjustments, US price declined 10%."
- CFO again: "You look at the US, and we're talking about 1 out of 10 patients that we are reaching nowadays"
- CEO Ricks: "we're in the middle of the largest new category expansion in the history of the pharmaceutical industry. And Lilly's leading that."
2. Medicare Bridge
- "more than half a million people have filled a prescription for a Lilly medicine through this program"
- 7 in 10 new Bridge patients pick Lilly, and "about 80% of the people getting treatment under Bridge are naive"
3. Where the cash goes (pulled from nodus42)
- $6.5B Houston + $5B Richmond plants broke ground, part of a "more than $50 billion push"
→ $D CEO on the Richmond site: "large load, lots of jobs, aggressive time schedule, which we were able to meet"
→ $NVDA CFO in August: "a fast follow to the Roche and Lilly build-outs as drug R&D timelines compress from years to months"
→ TuneLab data partners: $TWST, Ginkgo $DNA
My take: the beat is volume, price keeps sliding, and Lilly pours the cash into plants and compute. Ricks: "we're beating on the up. That's better than missing on the down." Catch: ~$2B of 2026 revenue (~$900M in Q3) was one-time, so 2027 laps a tougher base.
The biggest category expansion in pharma history is also a grid customer and a GPU buyer... still early.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
From the call... $PWR says it can't take most of the data center work it's offered. Duke Austin:
"we can't even get to 25%-30% of what they have in front of us, and we're having to basically look out five years"
- Inbounds are "moving at a faster pace than it's ever moved in my career"
- Already doing behind-the-meter generation and balance of plant for data center clients: "We just didn't press release it"
- His rough math on a ~$15M per MW build: Quanta got $3M to $4M a MW a year ago, can get $5M to $7M now, and "that'll be $7 million-$10 million"
- 765kV still isn't in backlog: "really good bookings, call it first half of 2027, and even some starts", Texas and Ohio first
- $AEP: "we're doing some supply agreements" ; $NI: "I expect us to book more there"
The constraint moved from crews to gear: "I don't think labor is going to be the issue. I think it'll be supply chain." And "Our growth will be dependent on the OEMs." They bought a pole maker this quarter, and Quanta is a "top five buyer of HV equipment."
The hedge: if data center work were "cut in half", "we do not fall off a cliff."
Poles, transformers, breakers, copper... that's where the waiting is now.
Quanta $PWR just added $10.3B of backlog in one quarter... about 2x what it added in each of the three quarters before. Total backlog: $63.7B, was $39.2B a year ago.
In July, CEO Duke Austin said the big 765kV and generation projects weren't even in backlog yet: "it will start to show up in backlog this year and in the field next year."
$PWR Q3'26 EARNINGS
Revenue: $12.01B (Est. $10.98B) ; +57% Y/Y
Adj. EPS: $6.06 (Est. $5.03) ; +82% Y/Y
FY26 revenue guide: $41.3B to $41.6B, was $39.3B to $39.7B (Est. $39.58B)
FY26 adj. EPS guide: $17.90 to $18.30, was $16.45 to $16.95 (Est. $16.75)
RPO (signed work): $41.8B, 2x a year ago
FCF: $1.2B in the quarter
Stock: +4.4% pre-market
1. Electric is the whole story
- Electric revenue $9.80B, +59% Y/Y, 82% of the total
- Electric backlog $51.9B, was $32.6B a year ago ; electric RPO $37.4B, was $19.1B
- Austin: "we are pacing ahead of the multi-year growth targets we outlined at our 2026 Investor Day"
- 2027: "We believe there is opportunity to deliver strong double-digit adjusted EPS growth in 2027"
2. What July said
- On generation: "I would say 95% of it is not in backlog either."
- Tech is "call it 15% to 20%" of the business, "a spectrum from chips to everything, not just data centers"
- On a data center build: "call it, 80% of what a data center build is, maybe 90%", Quanta can self-perform
- The bottleneck: "It takes about four years to make a craftsman and a journeyman."
3. Who's on file (pulled from nodus42)
→ 765kV transmission design-build for $AEP
→ customers named in its 10-K: $DUK, $NEE, $SO, $EXC, $ETR, $XEL, $NI, $WMB
→ EPC partner for Cipher Digital $CIFR (Black Pearl, Barber Lake)
→ US gas breaker JV with Hyosung Heavy (KR 298040)
My take: the EPS beat is nice, but RPO doubling is the line. That's contracted work, not MSA estimates, and July said the biggest transmission + generation jobs were still mostly in engineering. If this quarter is the first of them landing, the "compounding" Austin talked about has started. $XEL and $WEC report today too.
Chips ramp in quarters. Wires, substations and turbines ramp in years... and $63.7B is what a few of those years look like.
Pulled from nodus42, the AI supply chain mapped from company filings and calls. Image below.
@StockSavvyShay And $AAPL is still eating part of it. Cook in July: "we reluctantly raised prices" in "a 100-year flood on the memory pricing." Gross margin still slides from 49.3% in March to a 46.5% Sept-quarter guide, which the CFO said is "really driven by memory." They report Monday.