DNBC out w/3Q prev, so no active mandate there. "Interim CEO has been cleaning out legacy problems and setting a new org structure, suggesting business impr. potential at a low valuation. Reiterate BUY, lower TP to SEK24. 7.8x EV/EBITA and 3.8x NIBD/EBITDA at 26E at a 3.8% EBIT%.
Johan Nordström dumping all his shares in Green Landscaping $GREEN as a last goodbye to the company? Share down >5% on the news that he sold 800k y'day. Still no updates/previews from Pareto or DNBC, and no share purchases from the largest owners... Something's going on?
Re: Green Landscaping's $GREEN recent PW. No updates from the 2 most bullish sell side shops (DNB Carnegie and Pareto), while SEB (who's been lukewarm & right) have voiced their view. 0 reference to leeway vs bank covenants in the PW notice --> Equity issuance to be announced?
Woah Green Landscaping $GREEN trading like they need to issue equity. c6.9x 2026E EBITA and 3x NIBD/EBITDA on SEB’s estimates. But before we see 3Q numbers, “debt is high and conviction low.” Wouldn’t be surprised if the largest owners make a bid for the company.
Green’s past weak governance (write-downs, poor cash flow, police reports). Clein is actively cleaning house, which is positive long-term. However, today’s news signals a delayed turnaround and pushes back the expected H2 EBITA recovery.
Green Landscaping $Green out with a PW for 3Q27 inc cSEK80m in "1 offs", of wh. SEK65m relating to project writedowns (i.e loss from poor core ops in SWE and GER). Have clearly been too "hands off" + acquired poor businesses historically.. P.f c11x trailing EBITA including 1 offs
Idag gratulerar vi Warren Buffett som fyller 96 år. Han har lärt oss att vara långsiktiga värdeinvesterare. Retwitta så lottar jag ut några x av min bok på svenska om hans historik och framgångsformel.
Niche banks executing well, but shares aren't moving. Don't really need multiple expansion to do well from here. NOBA $NOBA, Enity $Enity, Morrow $MOBA all also look interesting. If I had to pick 1, I'd probably lean towards Enity due to its somewhat defensive product portfolio
Can’t really remember the last time I’ve heard New Wave $NEWA Torsten this optimistic in his CEO letter. Strong growth and healthy margins in 2Q26 despite ongoing IT/ERP investments.
As expected, SEB hike their price target on Brødrene A&O Johansen $AOJ to 142 DKK/sh (up from 125) after conservatively including the numbers for Elektroimportøren in their estimates. EBITDA up 30%, EPS up 11% (financing cost and D&A increased). Target based on 12x 2027E PE.
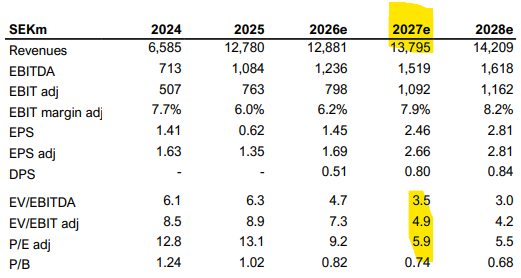
Implied in the 2027 estimates from DNBC is a 7% sales growth and a 1.4%p margin expansion on EBIT from 5.7% to 7.1% (synergies). Note that D&A due to HMY acquisition is sizable, so FCF yield sits at c12% on 2027E
ITAB Group $ITAB making a comeback? Large block y'day probably means that WQZ INVESTMENTS GROUP is out after selling continously for a while now. Leverage manageable at c2.0x NIBD/EBITDA year end, trading at c8.8x 2026E EV/EBIT and 6x 2027E (27E PE below 7x). Interesting setup.