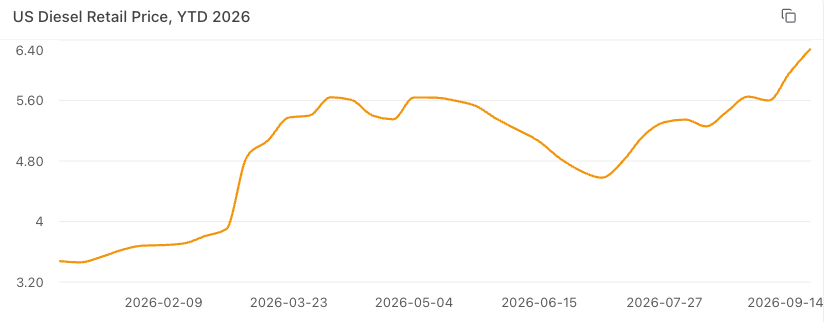
Diesel deserves more attention in the inflation debate and the pressure is global.
Supply losses in the Middle East, Russia and China are tightening the market. In the US, refineries are slowing down for maintenance just as farmers need more fuel for harvest, leaving less diesel in storage.
Even if crude oil gets cheaper, moving goods and growing food could stay expensive for a long time.
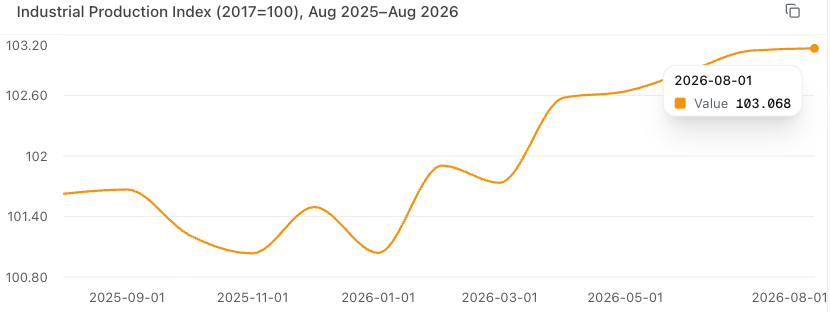
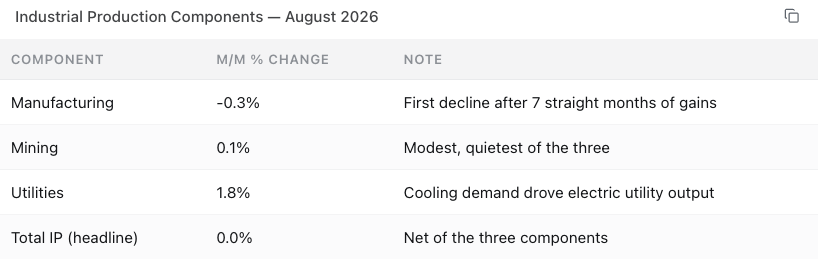
August industrial output was flat, but manufacturing fell 0.3% after seven monthly gains. Utilities rose 1.8%, masking the softer factory picture. If that weakness persists, it complicates the case for more tightening.
The price of uncertainty is hiding inside “priced-in hikes”.
The BoE’s September minutes describe a UK short-rate curve reaching around 4.9% by end-2027. They attribute much of its upward slope beyond the near term to risk premia: compensation for uncertainty.
The implication: forward rates can fall as that premium fades, even without a big change in expected policy. Counting every basis point as another hike misses that distinction.
A rate hike tomorrow could still send bond yields lower.
What matters is how much tightening the Fed signals after this meeting, relative to what investors already expect.
A 25bp hike paired with room to pause sends a very different message from a hike paired with a faster, higher rate path.
I’ll be watching the new dots, the conditions for another move, and whether the initial reaction survives the press conference.
The decision changes today’s rate. The guidance can change the valuation of the whole path ahead.
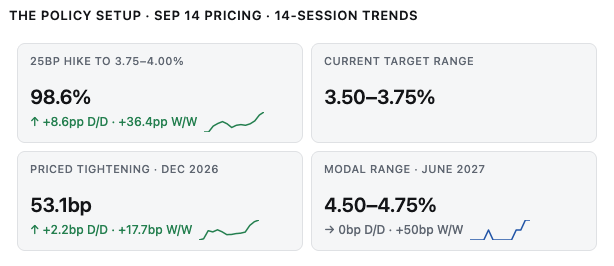
The past two weeks have put Fed hikes firmly in focus.
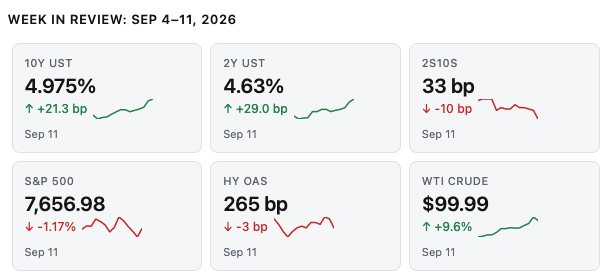
The repricing started with August payrolls: +162K against ~53K expected. Last week’s firm core CPI and nearly 10% oil surge added to the pressure heading into the Fed.
Bonds led last week’s reaction: the 2Y yield jumped 29bp, the curve flattened, and rates volatility rose sharply.
Credit barely flinched. Equities fell, with small caps and health care taking a bigger hit than the S&P headline suggests.
The tension heading into the decision: a sharp repricing of rates, with limited spillover into credit so far.
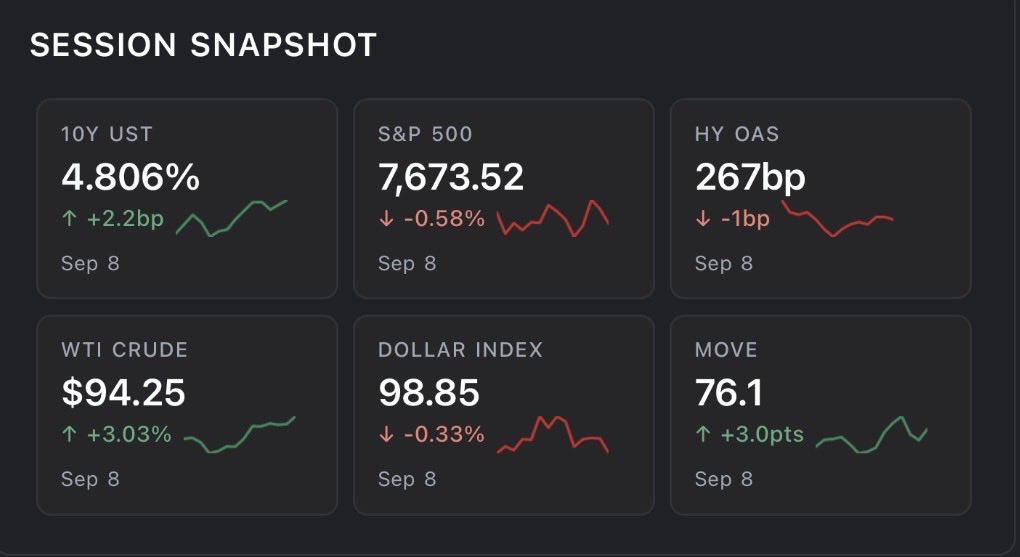
Quick market update from yesterday’s volatile trading day:
An oil shock did the damage. WTI ripped +3.0% to $94.25 on Houthi strikes against Saudi energy infrastructure, and equities sold off broadly into it (S&P -0.58%, Dow -1.18%) with the curve drifting 2bp higher across the strip. The Dow's underperformance was idiosyncratic, not macro — Amgen's ~10% collapse on the Novartis pelacarsen failure took health care down -2.5% and dragged the price-weighted index. The Fed is the live risk into next week: 60% of the Sept 16 meeting is now priced for a hike to 3.75-4.00%, with an energy-driven CPI print landing Friday.