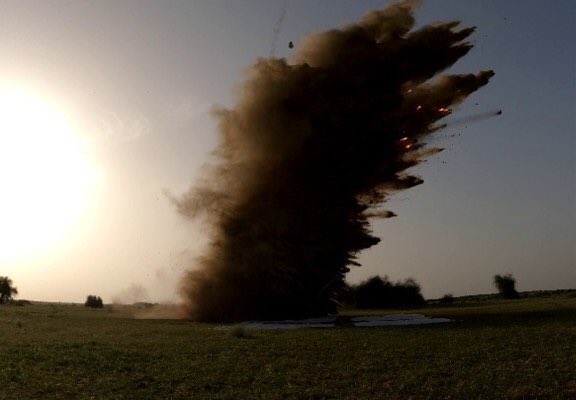
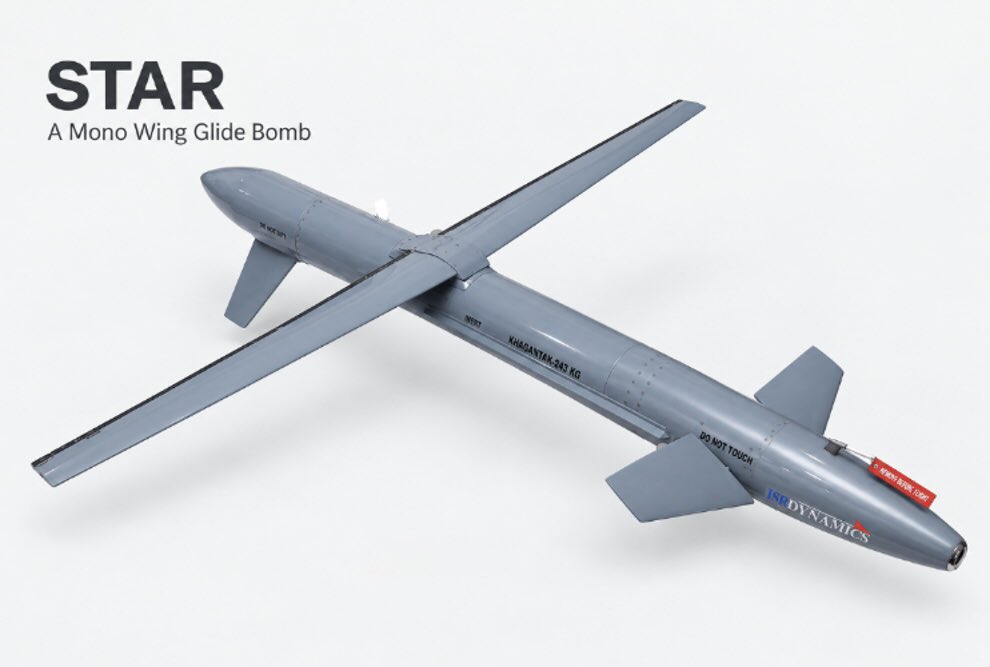
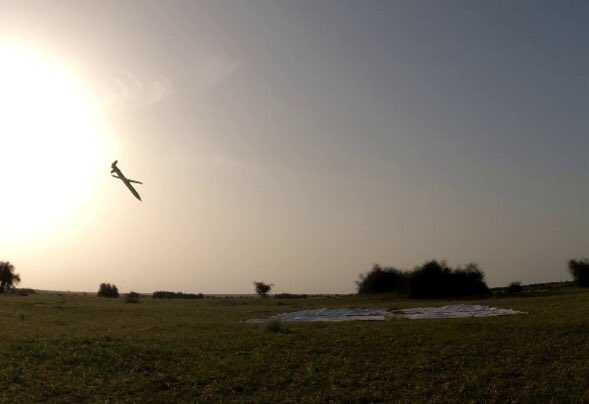
It all started with “STAR”, a mono wing glide bomb. In 2021, Khagantak design was frozen, now fully integrated and launched from Su-30Mkl.
Proven: CFD | Design | GNC | MCU Software
Accuracy 36% and range 80% more than specified.
World’s Longest Range Glide Bomb - Khagantak:243
🚨 BIG MOVE BY LIC!
LIC gets RBI approval to increase its stake in ICICI Bank to up to 9.99%. 🏦🔥
• Current stake: ~4.35%
• Permitted stake: Up to 9.99%
• RBI approval valid for 1 year
• LIC can potentially more than double its holding
Important: This is an approval to increase the stake — NOT confirmation that LIC will immediately buy the entire additional stake.
Still, this is a BIG vote of confidence in ICICI Bank.
The purpose of appointing a market maker in an SME IPO is to provide genuine two-way liquidity by continuously offering both buy and sell quotes, thereby facilitating fair price discovery.
In the case of Millworks, however, the trading pattern raises serious questions. For an extended period, the market maker, PACE Stock Broking Services, appears to have been predominantly buying shares rather than providing meaningful two-way quotes. If the market maker is largely accumulating shares instead of actively selling as well, can this still be considered true market making?
Based on publicly available data, brokers have collectively accumulated approximately 17.2 lakh shares, while the designated market maker reportedly holds around 12 lakh shares. This means that nearly 21 lakh shares are concentrated with brokers and the market maker.
This creates a significant concern for retail investors. If such a large inventory is accumulated at lower prices and is eventually released into the market after valuations have risen substantially, retail participants could effectively become the exit liquidity by purchasing those shares at much higher prices.
This raises several important questions:
Where is the "two-way" quoting that market makers are expected to provide?
Is prolonged one-sided accumulation by a market maker consistent with the spirit and objective of the SME market-making framework?
How does this contribute to fair and efficient price discovery?
What safeguards exist to ensure that retail investors are not disadvantaged by such trading patterns?
These are legitimate questions that deserve clear answers from the exchange and the regulator. Investor confidence depends not only on compliance with the letter of the rules but also on adherence to the principles of transparency, fairness, and orderly markets. If market making effectively becomes prolonged accumulation followed by distribution at significantly higher prices, it risks undermining confidence in the integrity of the SME market.
Now suddenly on one fine day everything will be given to normal retail at higher valiations
@SEBI_India @BSEIndia@NSEIndia@PMOIndia
#millworks
After investing a significant amount, I expected reliability and long-term performance, but instead faced inconvenience and regret. Overall, it has been a poor value-for-money experience for me. The company continues to promote annual maintenance contracts, adding further expense
Respected @nsitharaman ji and @FinMinIndia,
Suggestion 3 of 3 for strengthening India's capital markets:
Securities Transaction Tax (STT) should be abolished.
STT was introduced as a simplified transaction tax to facilitate easier collection of taxes from capital market transactions. However, over time, it has effectively become an additional layer of taxation alongside other market-related levies.
A simplification measure should not evolve into permanent duplication.
In addition to brokerage, investors already bear multiple statutory and regulatory charges including exchange transaction charges, GST on transaction-related charges, SEBI turnover fees, stamp duty and STT.
Unlike income tax, STT is payable irrespective of whether an investor makes a profit or a loss. The investor pays the tax simply for participating in the market.
Capital markets play a vital role in channeling household savings into productive enterprises, supporting entrepreneurship, generating employment and strengthening India's economic growth. Transaction costs and multiple layers of taxation discourage participation, particularly among long-term retail investors.
India's equity markets have matured significantly since the introduction of STT. The time has come to review its original purpose and reconsider its continued relevance.
Abolishing STT would simplify market taxation, improve capital market efficiency and encourage greater participation in India's growth story.
Respectfully submitted.
Respected @nsitharaman ji and @FinMinIndia,
Suggestion 2 of 3 for strengthening India's capital markets:
Dividend income on listed equities should not be subjected to double taxation.
A business can raise capital in only two ways: debt or equity.
When a company raises debt, the interest paid to lenders is treated as a business expense and deducted before tax. The lender may then pay tax on the interest received.
However, when a company raises equity capital, dividends are paid out of profits that have already suffered corporate tax. The shareholder is then taxed again on the same stream of income.
More importantly, equity capital bears far greater risk than debt capital. A lender has a contractual right to interest and principal repayment. A shareholder has no such guarantee. Dividends are discretionary, capital is fully at risk, and the shareholder stands last in line if a business fails.
If debt providers receive tax-deductible compensation despite bearing lower risk, there is a strong case for more favourable treatment of equity providers who supply the permanent capital that fuels entrepreneurship, innovation, employment and economic growth.
India needs to encourage long-term risk capital and greater participation in equity markets. Tax policy should reward those who provide patient equity capital to Indian enterprises rather than place them at a relative disadvantage compared to debt capital.
Respectfully submitted.