Is it 2008-2009 all over again for commercial real estate and multifamily?
Not exactly. Everyone loves to compare today to the GFC. And while today's challenges are very real, the GFC comparisons remain a stretch.
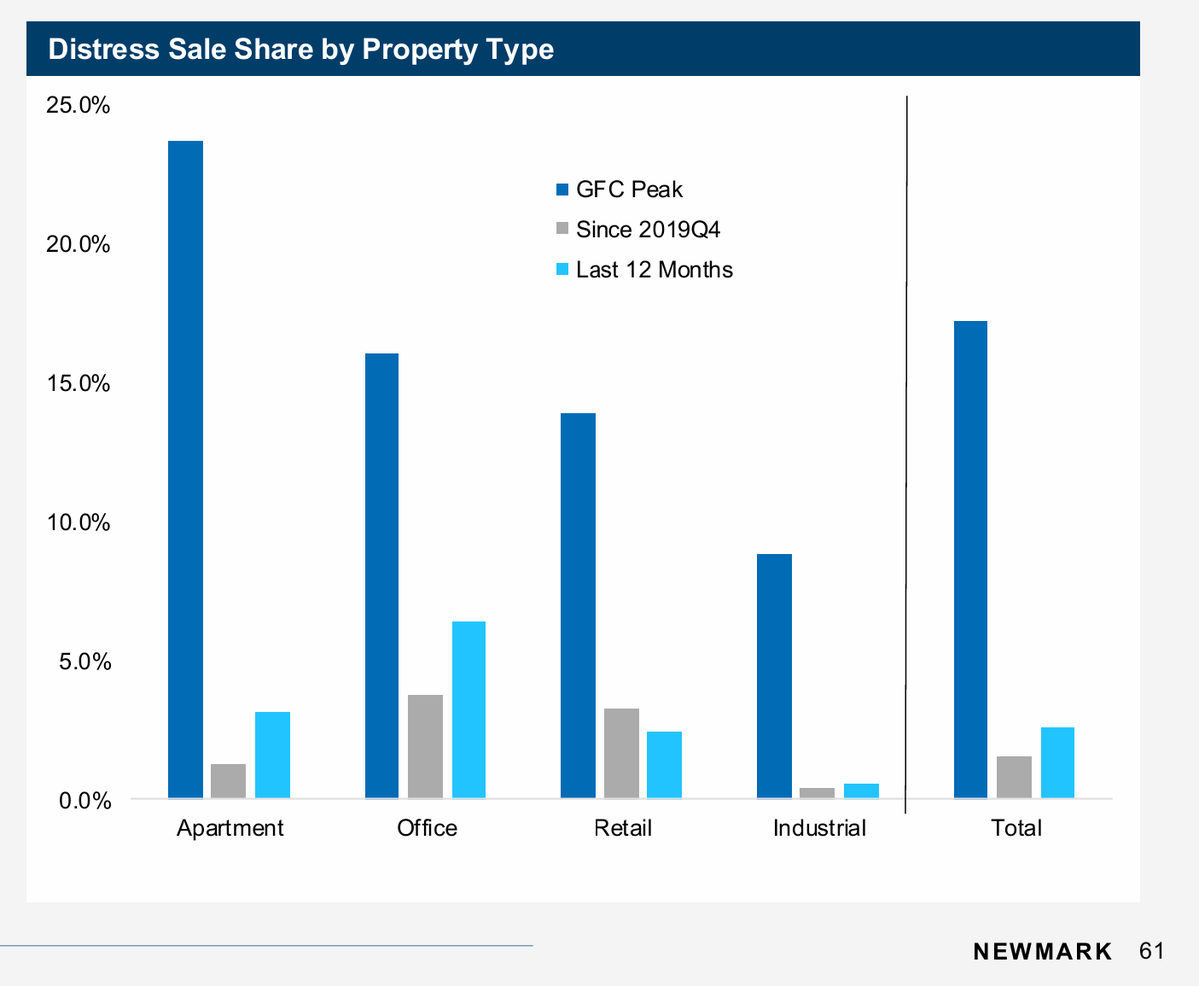
For multifamily, distress sales still represent <5% of all sales today versus nearly 25% during GFC, according to analysis from Newmark.
If you don't see the connection between high interest rates and reduced housing supply, here is Exhibit 192: Camden just canceled two big apartment development projects because the math no longer works.
CEO Alex Jessett on recent earnings call: "We were hoping that we'd find ways to make it so that they did work. And the reality is we just couldn't get there."
One was in Nashville, the other Denver. In Nashville, it was an urban site in the Gulch. Camden ended up buying an existing apartment property next-door to its development site. That acquisition cost $370k per unit compared to development that would cost $600k per unit.
In fairness, the build-vs-buy gap isn't that large everywhere (especially in low-density areas). But Camden's story reflects a harsh reality for developers today, as they confront the realities of rate hikes:
1) Debt costs are going up, and builders rely on debt.
2) Higher rates = lesser value. Apartment values are down about 5% due to rate hike. As a developer, your costs are going up at the same time the value of what you're building is going down. That's a formula that hurts development.
Apartment construction starts are already down 50% from peak, and I'm increasingly of the view that they'll decline further here in Q4 and into 2027.
Just a brutal environment for apartment developers these days with high interest rates, frozen equity capital and some construction cost increases -- outweighing improved occupancy/rent trends in most cases.
No one is immune to math.
If you are relying on Census building permits for multifamily construction trends, you are blissfully unaware of realities on the ground.
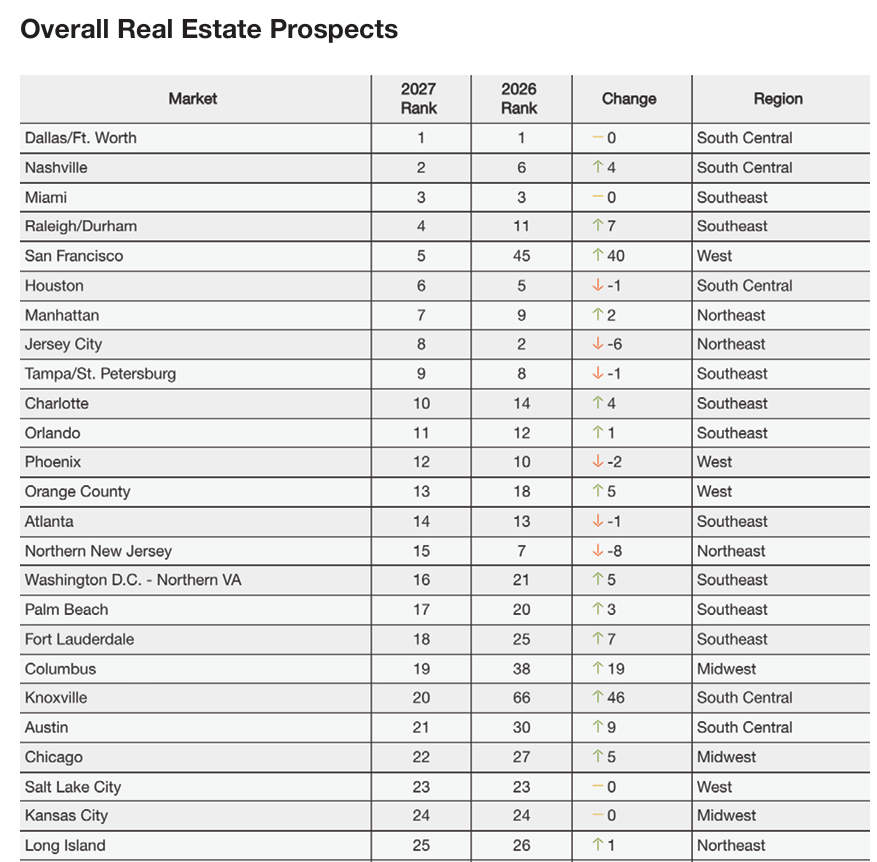
Here are the top 20 markets for real estate investment in 2027, according to ULI's annual Emerging Trends Report just released this week. Quick thoughts on multifamily market in each:
DFW stays No. 1, not a surprise. Been steadier than other Sun Belt markets. Still supply to work through, but still attractive and very liquid.
San Francisco ranks No. 5, up 40 spots from last year, and would probably rank No. 1 if not for the fact that many survey respondents would probably never invest in San Francisco regardless how it is. Same for Manhattan, where policy risk questions dampen some enthusiasm and redirect capital elsewhere.
Interesting to see DC's Northern Virginia suburbs rank high, yet its Maryland suburbs rank dead last and the District is in the bottom 5. But that's the reality of the DMV, and its just governance issues-- with the District and Montgomery County competing for the crown of most conspiratorial anti-business market while Northern Virginia gladly benefits from it.
Austin and Boise both rank outside the top 20, but I'd be bet on both being in top 20 next year. ULI's list is supposed to be forward-looking, but this is example of how in reality it's still very much a present-day lens... just like San Francisco ranking No. 45 last year.
Knoxville ranks as highest tertiary market, coming in at No. 20 overall. Good market but surprised it's so high.
ULI's survey respondents put Norfolk and Milwaukee in the bottom 10, but I think they're just saying they don't know these markets. Both are very steady and interesting, low supply.
@RonnieBrewerJr This is what you Coach and the rest of Cal's staff had to tell him. Stay the course ..we know what you can do...they will soon find out (in the League)...Awesome to see!!