Klaviyo's heavy MCP users generated roughly 16% more platform usage in Q1. MCP lets outside AI agents access Klaviyo's marketing tools, so work started in an external interface can still run through the platform. Analysts estimate that greater agent activity could increase the number of customer profiles Klaviyo handles, along with the volume of messages and campaigns it runs.
Klaviyo charges primarily by contact, so a larger contact base gives it a way to earn more from an existing account. The next comparison is whether heavy MCP users also expand what they buy from Klaviyo. Account expansion would show whether customers doing more work on the platform are buying more from it, while paid AI use would capture spending on the agent activity itself.
#Software #Salesforce #Meta
Report date: 2026-11-20
Palo Alto Networks' net-new next-generation security annual recurring revenue (NGS ARR) grew 133.3% YoY in fiscal Q1 2027 as customers consolidated security tools. The company added $630mn of NGS ARR and completed about 170 net-new platformizations, more than in its prior two fiscal first quarters combined. Customers that adopted its integrated platforms now account for two-thirds of NGS ARR and have 120% net retention. Revenue growth accelerated from the prior quarter across all three platforms.
Palo Alto Networks ended the quarter with $9.73bn of NGS ARR against its $9.55bn guidance midpoint. The company raised its FY27 revenue and NGS ARR guidance by more than the respective Q1 beats, just 3.5 months into the fiscal year. One analyst team kept its Buy rating and raised its DCF-based target price estimate to $440. A separate analyst team kept its market-perform rating, citing elevated cybersecurity multiples.
#Networking #Earnings
Report date: 2026-11-19
NetApp's dividend payout ratio falls to 17.0% in FY29 in analysts' estimates as earnings per share rise and the annual dividend stays flat. NetApp paid $2.08 per share in FY26, equivalent to 25.6% of earnings. Analysts estimate it will keep that annual dividend through FY29 as adjusted EPS rises from $8.13 in FY26 to $12.20 in FY29. After NetApp ended FY26 with $412mn in net debt, analysts estimate it will reach $203mn in net cash at the end of FY28 and $1,227mn at the end of FY29.
Analysts estimate cash and equivalents will reach $3,465mn at the end of FY29, up from $2,075mn at the end of FY26. Channel checks pointed to solid storage demand ahead of the October-quarter results. The risk to the earnings estimates is how customers respond when storage vendors pass through higher memory costs. Most vendors are assuming little effect on demand from those price increases, according to analysts. They warn that customers could cut purchases by more than the industry expects, putting pressure on the earnings growth behind the lower payout ratio.
#Networking #HPE #Dell #NVIDIA #Hardware
Report date: 2026-11-19
Seagate ($STX) is projected by analysts to grow revenue 65.2% YoY in FY27 as growth in hard drive exabytes slows. In FY26, revenue grew 34.1% and HDD exabytes rose 32.6%. Analysts estimate exabyte growth will slow to 22.2% in FY27. They estimate that both rates will ease in FY28, with revenue up 46.3% and exabytes up 19.3%. The fiscal years end in June. Revenue covers the whole company, while the exabyte figures measure the amount of storage Seagate ships in its hard drives.
Analysts flag stronger pricing power as upside to their estimates and a greater-than-expected normalization in prices as downside. Their bear case assumes HDD makers begin expanding capacity, weakening the supply discipline they credit for the industry's improved profitability. The two growth rates cover different parts of the business, so the exact contribution from pricing still needs to be measured separately. Seagate's selling prices and exabyte shipments together can show whether sales are tracking the analysts' estimates as shipment growth slows in their model.
#MarketStrategy #Investing
Report date: 2026-11-17
Nebius increased its contracted power from 2,000 MW in 4Q25 to about 4,000 MW in 3Q26, with a gap in local generation holding back its rollout for Microsoft. At Vineland, New Jersey, temporary generation was withdrawn faster than management expected while Bloom generation was still ramping up. Nebius continued delivering capacity to Microsoft during 3Q26, and management said all affected capacity remained in the rollout. The colocation delays pushed some planned capacity into 2027.
Management narrowed its FY26 revenue guidance to an estimated $3.0bn–$3.2bn from $3.0bn–$3.4bn and moved its target for more than $7bn in annual recurring revenue to February 2027. Separate checks with an on-site power supplier found growing interest among customers in agreements spanning multiple projects. At Vineland, the immediate test was specific to the site. In its November update, Nebius management expected further Microsoft deliveries in November and December as power became available.
#Telecom #IREN #NVIDIA #CoreWeave #Crypto
Report date: 2026-11-19
Himax Technologies' wafer-level optics for co-packaged optics (CPO) account for 11% of its 2027 revenue in the analysts' estimate. The analysts see Himax as the sole supplier for FOCI's fiber-array unit, tying those optics sales to the CPO rollout. Their base case also counts liquid crystal on silicon (LCOS) and WiseEye among the products driving growth outside display driver chips.
The analysts estimate non-driver IC revenue rises from US$314mn in 2027 to US$627mn in 2028, overtaking small and medium display driver IC revenue, which they estimate at US$553mn in 2028. For the wafer-level optics business, the milestone is when CPO is introduced. The analysts see a faster-than-expected introduction as upside for Himax and a slower-than-expected introduction as downside.
#Semiconductors #Apple
Report date: 2026-11-20
Novatek has few options for cheaper wafers as UMC ($UMC) negotiates specialty-node price increases of around 20%, according to analyst checks. UMC also notified customers of a 10%+ first-round increase effective in 1Q27, and analysts expected final pricing to be confirmed in December. Analysts covering chip distributors cite normalizing memory prices as one reason for cutting their estimates. For Novatek's wafer orders, analysts say UMC, VIS and SMIC are all running at full utilization and raising prices, leaving little room to save by switching among them.
Analysts believe Novatek plans to move some wafer orders from VIS to Nexchip, which offers better pricing. Novatek is also shifting some packaging and test orders to Chinese providers that its Chinese customers prefer. Chipbond and ChipMOS raised prices in May, and analysts estimate they could raise them again by roughly the same amount in 4Q26 or 1Q27. For RAM-less display driver chips used in Chinese smartphones, Novatek is considering Nexchip's 40nm process once yields stabilize.
#Semiconductors #Investing
Report date: 2026-11-20
Intuit ($INTU) cut its FY27 Credit Karma revenue growth guidance to 3–7% from 11–13%, putting pressure on the returns from bringing new filers into TurboTax at lower prices. Management said persistently high rates weighed on consumer demand and partner spending late in fiscal Q1. It also said people shifted toward large language models for discovery faster than expected and that Credit Karma can regain visibility there. Credit Karma drove the entire cut to Intuit’s FY27 revenue growth guidance, now 8–9% versus 9–10% previously. The company kept its full-year operating income and EPS guidance.
Lower-priced DIY TurboTax brings in less revenue per customer upfront. Intuit’s plan relies on earning more from some of those filers over time through Credit Karma and Money. The company now guides to 2–4% FY27 Consumer revenue growth and has kept its three-year compound annual growth guidance of 4–8%. That puts more weight on gaining share in Assisted Tax. During the February–April tax season, the first signal is whether lower DIY prices and Credit Karma Tax help win back e-file share. The next is how soon new filers start generating revenue through other Intuit products.
#Intuit #Software
Report date: 2026-11-20
Salesforce ($CRM) had seen only about 5% of Sales and Service knowledge workers upgrade to higher-end editions, the tiers required for its headless AI features. For customers on standard editions, the upgrade lets employees start a task in an external AI assistant and still use Salesforce data, workflows and permissions to get it done. The disclosed upgrade rate gives Salesforce a baseline for how widely it has sold those editions within the Sales and Service workforce as more customers gain access to its software through outside agents.
Salesforce also sees a chance to reach knowledge workers who would otherwise have no Salesforce seat. The tools those employees already use can call Salesforce in the background to retrieve data or carry out a task. Within the Sales and Service group, a rising share of workers on upgraded editions would show that more customers are paying for access to premium features. Analysts estimate that customers may need clearer evidence of labor savings before they agree to increase their overall spending with Salesforce.
#Software #Salesforce #Meta
Report date: 2026-11-20
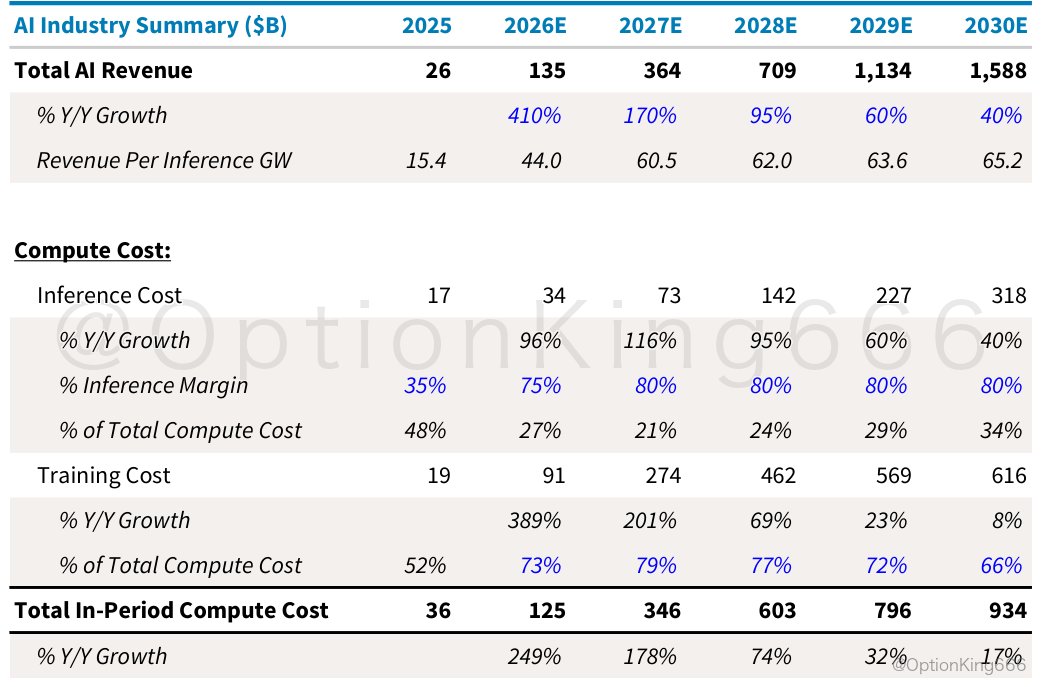
Amazon ($AMZN) is unlikely to face a destructive cloud price war comparable to its 2014 period of up to 80% EC2 and S3 reductions, as analysts estimate blended AI inference margins will remain resilient at 80% through 2028. While recent frontier API token cuts have raised fears of severe margin compression across cloud providers, sell-side models project that overall AI industry revenue will double to $364bn in 2027 and reach $709bn in 2028, supported by inference costs rising from $73bn to $142bn. Individual product margins range from 65% to 95%, with API margins tracking substantially higher than subscription offerings. Analysts interpret current token price reductions as labs testing demand elasticity to expand volume and capture gross profit dollars as compute capacity expands, rather than structural price degradation.
Recent revenue deceleration across platform providers largely stems from a one-time crackdown on model distillation alongside token price adjustments, rather than deteriorating end-market demand. Analysts project that software engineering will hand off monetization momentum to general knowledge work around 2028, expanding the enterprise addressable market beyond early coding agents. However, analysts caution that native AI startups still account for a meaningful portion of industry revenue, creating the risk of a temporary demand air pocket if venture capital financing dries up before enterprise knowledge work diffusion matures. Industry compute expansion remains substantial, with sell-side estimates projecting 48.6 GW of total online capacity in 2028, including 11.3 GW dedicated to paid inference workloads.
#Software #Cadence
Report date: 2026-11-20
Hewlett Packard Enterprise ($HPE) could bring net debt down from 3.0x adjusted EBITDA in FY25 to 0.4x in FY28, analysts estimate, as repayments and earnings growth reduce leverage after the Juniper acquisition. Analysts estimate net debt repayments of $2,140mn in FY27 and $2,850mn in FY28. They project FY28 net debt of $4,833mn, down from $16,592mn in FY25.
Analysts estimate cash and cash equivalents will rise from $5,773mn in FY25 to $13,155mn in FY28, while adjusted EBITDA rises from $5,579mn to $11,823mn over the same period. HPE needs to remove overlapping functions and combine sales and engineering teams to capture the savings it targeted in the Juniper deal. Analysts warn that delays could leave margins and cash flow weaker than the deal assumes. The balance sheet test is whether cash builds as HPE makes those net debt repayments.
#Networking #HPE #Dell #NVIDIA #Hardware
Report date: 2026-11-19
SanDisk ($SNDK) revenue would fall from $58.340bn in FY28 to $45.818bn in FY29 under analyst estimates. That would also put sales below analysts’ $50.258bn estimate for FY27. All three fiscal years end in June. Analysts estimate FY29 non-GAAP gross margin would ease to 81.1%, still above its FY26 level, and non-GAAP EPS would fall to $217.74. The model gives back the sales gains before it gives back the gains in gross margin.
Analysts estimate through-cycle earnings of $62.50 per share, below their $72 estimate for average EPS from CY22 to CY27. They flag slower AI investment as a risk to NAND industry growth and see upside if SanDisk improves its position in data-center SSDs. The pace of AI spending matters for how much demand reaches the NAND market, while SanDisk’s position in data-center SSDs matters for how much of that demand it can capture.
#MarketStrategy #Investing
Report date: 2026-11-17
Android smartphone shipments fall 9% YoY in House B's 2027 base-case estimate, leaving display driver chipmakers less room to pass on higher wafer and packaging costs. House B cut its Android shipment estimate to 768mn units from 875mn and estimates Apple ($AAPL) iPhone shipments will rise 7% YoY to 270mn in the same base case. Higher memory costs are squeezing handset makers' budgets for displays, touch controllers and sensors. Himax's LCD touch and display drivers go into entry-level and midrange phones, where pressure to cut component costs is greatest.
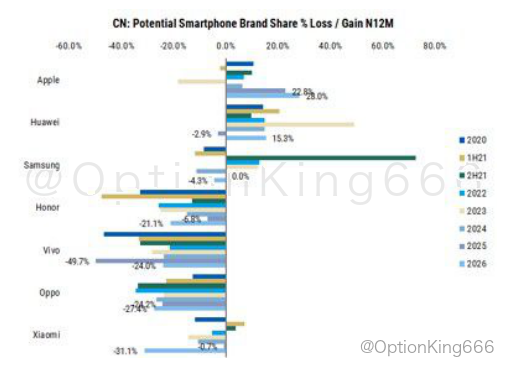
In a 2026 survey across the US, China, the UK and Germany, 41% of smartphone owners said they were extremely likely to upgrade within 12 months, down 2 percentage points YoY. In China, Apple led net switching intentions at +28% of its installed base. House B analysts expect some new OLED programs to lift chip content per phone, but see weaker Android demand limiting suppliers' pricing power. If more buyers follow through on switching to iPhone, the analysts expect component demand at several Android brands to weaken further. Actual brand switching and cuts to Android display and touch specs will show where that pressure reaches suppliers.
#Semiconductors #Apple
Rockwell Automation set a long-term target of roughly 100% free cash flow conversion at its investor day. That gives investors a benchmark for how closely the cash left after capital spending tracks earnings as the automation business grows.
Management paired the cash goal with long-term targets for return on invested capital above 20% and leverage of 2x. When Rockwell reports results, investors can track whether earnings are turning into cash while checking how much the company earns on the capital it deploys and where leverage stands against management's goal.
#AIAgents #AI
Report date: 2026-11-20
Novatek has released two test chips at TSMC, and analysts believe it is still awaiting a meaningful 4nm ASIC project win. Since signing a licensing agreement with Arm ($ARM), Novatek has made progress on chip IP and become more familiar with CoWoS packaging. Analysts put Novatek's capability at 4–5nm and say mainstream data center ASICs at cloud providers already use 3nm or more advanced nodes. Given that gap, analysts estimate Novatek is unlikely to win work on those providers' main data center chips.
Novatek is in discussions with hardware companies and US fabless chipmakers. Analysts say the talks with US fabless firms focus mainly on outsourced work or products that complement those firms' existing chip portfolios. They see custom silicon as a sound long-term strategy for Novatek and estimate that a meaningful revenue contribution is still distant. The milestone to watch is a project award from an AI customer. Analysts estimate that such a win would likely prompt a rerating of Novatek's shares.
#Semiconductors #Investing
Report date: 2026-11-20
Salesforce ($CRM) saw agentic platform usage through MCP and Claude-related calls rise 6x in Q2 FY27. The company disclosed nearly 1 trillion API calls and 4.5mn MCP calls for Q1 FY27. Claudeforce extends external agents' access to Salesforce data, workflows and permissions, so the platform can handle more requests that start in other interfaces.
Under Salesforce's announced Headless Toolkit design, each external agent gets its own platform identity. Admins can give agents narrower permissions than human users. Every successful call by a registered agent is to count as a Headless Platform Interaction and draw against Flex Credits, whether it comes through MCP or a direct API. Salesforce's approach illustrates a wider shift in enterprise software toward charging for the work agents do alongside subscriptions. Salesforce says interaction counts depend on how each third-party agent is built and prompted. Analysts had yet to see a price per interaction. The number of billable calls and the effective charge per call will show how much this new access can add to revenue.
#Software #Salesforce #Meta
Report date: 2026-11-20
Shin-Etsu Chemical's photoresist sales will rise 46% YoY in the fiscal year ending March 2027, analysts estimate, on strong demand for multilayer and EUV resists used in advanced logic and memory chips. Analysts raised their electronic materials operating profit estimate from ¥437.0bn to ¥460.0bn for the year, implying 34% YoY growth. Rare earth magnet sales for cars and hard disk drives have also been strong, and the analysts' profit estimate includes a lift from product price revisions.
Shin-Etsu's group operating profit guidance for the same year is ¥700.0bn. Analysts raised their group estimate from ¥716.0bn to ¥773.0bn, up 22% YoY, with electronic materials driving most of the growth they expect. For the fiscal year ending March 2028, analysts estimate electronic materials operating profit of ¥525.0bn, up 14% YoY, on strong demand for wafers, photoresists and magnets and a modest benefit from price revisions.
#Chemicals #Materials
Report date: 2026-11-19
Wolters Kluwer is bringing its proprietary legal content into AI-powered drafting and workflow tools through its integration of Libra. At the 2026 TMT conference, the integration illustrated how a software vendor can take on a larger role in its customers' daily work. The same legal material that customers consult for information can now be used in the tools that help them prepare documents.
Early adoption in routine drafting and related tasks would help show whether legal teams are making Libra part of their day-to-day work. For Wolters Kluwer, the opportunity is to make its content useful at the point where customers produce a document. The commercial test is whether customers' use of those features brings in incremental software revenue.
#AIAgents #SAP
Report date: 2026-11-20
Meta Platforms ($META) ranks among 4 of the 8 largest constituents in the S&P 500 whose free cash flow trends look far more favorable than buyside expectations if the overall AI build-out slows, according to analyst estimates. As the market transitions from infrastructure hardware toward platform operators, analysts estimate that hyperscalers now represent over 70% of incremental industry capacity, allowing scaled platforms to easily absorb troubled projects from smaller neoclouds that account for only a mid-teens percentage of capacity. In open-weight AI architectures, analysts project Western initiatives from Meta and NVIDIA ($NVDA) will gain market share as export and leasing restrictions on advanced compute widen the performance gap against lower-tier competitors.
The key financial catalyst hinges on potential domestic infrastructure bottlenecks, where analysts estimate that newly elected Democratic governor states account for over 35% of planned 2028 incremental U.S. gigawatts. If scrutinized local permitting and power constraints compress planned U.S. additions, analyst models project hyperscaler capital expenditure growth would flatten or decline year-over-year while industry AI revenues nearly double, adding almost $100bn in incremental sector EBIT at mid-30% operating margins. This capital flattening would pull forward positive free cash flow inflections for scaled operators. However, the primary operational risk remains a demand air pocket across native startups if venture financing tightens before enterprise knowledge-work adoption fully scales.
#Software #Cadence
Report date: 2026-11-20