The marriage penalty isn’t the only disastrous flaw in Washington State’s incoming 9.9% income tax (SB 6346). The legislation is drafted so poorly that it creates an absurd tax cliff—triggering an effective marginal tax rate of over 1,300% on people who realize just a tiny amount of taxable capital gains.
While modeling WA’s 9.9% tax on income over $1M (scheduled for 2028), a bizarre edge case emerged in how the new income tax interacts with Washington’s existing capital gains excise tax.
Here is the breakdown:
The Background
The Existing Capital Gains Tax (RCW 82.87):
0% on the first ~$278k of long-term capital gains (standard deduction, indexed for inflation).
7% on gains above ~$278k up to $1M.
9.9% on gains above $1M.
The Incoming Income Tax (SB 6346):
9.9% on Washington taxable income exceeding $1M (derived from federal AGI).
To prevent double-taxing capital gains, the bill establishes an adjustment mechanism in Section 302:
Sec. 302(1): First, you deduct all long-term capital gains from your federal AGI.
Sec. 302(3): Then, you add back the WA-taxed gain plus the standard deduction (~$278k) to fold capital gains back into your Washington base income.
The Statutory Glitch:
The critical drafting flaw lies in the final sentence of Section 302(3):
"This subsection (3) applies only to taxpayers owing tax under chapter 82.87 RCW for that taxable year."
Because the add-back only triggers if you actually owe capital gains tax, it creates two wildly divergent outcomes for high earners:
Gain under ~$278k: You owe $0 under RCW 82.87. Because you owe no capital gains tax, Sec. 302(3) does not apply. Your capital gains were stripped out in Sec. 302(1) and never added back. Your capital gains completely escape the 9.9% income tax.
Gain $1 over ~$278k: You now owe capital gains tax under RCW 82.87. Suddenly, Sec. 302(3) triggers. The statute forces you to add back the taxable gain plus the entire ~$278k standard deduction. The whole gain is thrown back into your income tax base.
The Math: A $27,600 Penalty for Making $2,000 More
Consider a single filer earning $1.2M in W-2 wages (using the ~$278k deduction threshold):
Scenario A: $277,000 Long-Term Gain
Capital Gains Tax (RCW 82.87): $0 (under the deduction)
Sec. 302(3) Add-Back: Does not apply.
Income Tax Base: $1,200,000 (gains remain fully excluded)
Taxable Income over $1M: $200,000
9.9% WA Income Tax: $19,800
Total WA Tax: $19,800
Scenario B: $279,000 Long-Term Gain (Just $2,000 more)
Capital Gains Tax (RCW 82.87): 7% on $1,000 = $70
Sec. 302(3) Add-Back: Triggers because $70 of tax is owed. The full $279,000 is added back into base income.
Income Tax Base: $1,479,000
Taxable Income over $1M: $479,000
9.9% WA Income Tax: $47,421
Total WA Tax: $47,491
The Takeaway
By realizing an extra $2,000 in capital gains, this taxpayer’s total state tax liability jumps by $27,691 ($70 in capital gains tax + $27,621 in new income tax).
That is an effective marginal tax rate of 1,384% on that $2,000.
This cliff affects anyone whose other income (wages, business income, RSUs) already puts them over $1M—such as dual-income tech households or startup employees experiencing a liquidity event. Crossing the capital gains exemption line by even a single dollar unexpectedly exposes the first ~$278,000 of previously exempt gains to a 9.9% tax penalty.
Whether this was an intentional trap or simply careless drafting, it underscores how poorly structured this legislation really is.
Seattle is about to have the highest tax rate in America, above New York City. The people who work for a living are carrying it.
Seattle Is Killing Small Business.
https://t.co/4NKFIc7ba8
For decades, Kaziranga lost rhinos to men who knew the ground better than the rangers chasing them. Then someone changed the odds. In 2022, for the first time in 45 years, it went a full year without losing one. Read on.
1/12
Washington just did something it spent nearly a century telling voters it could not do.
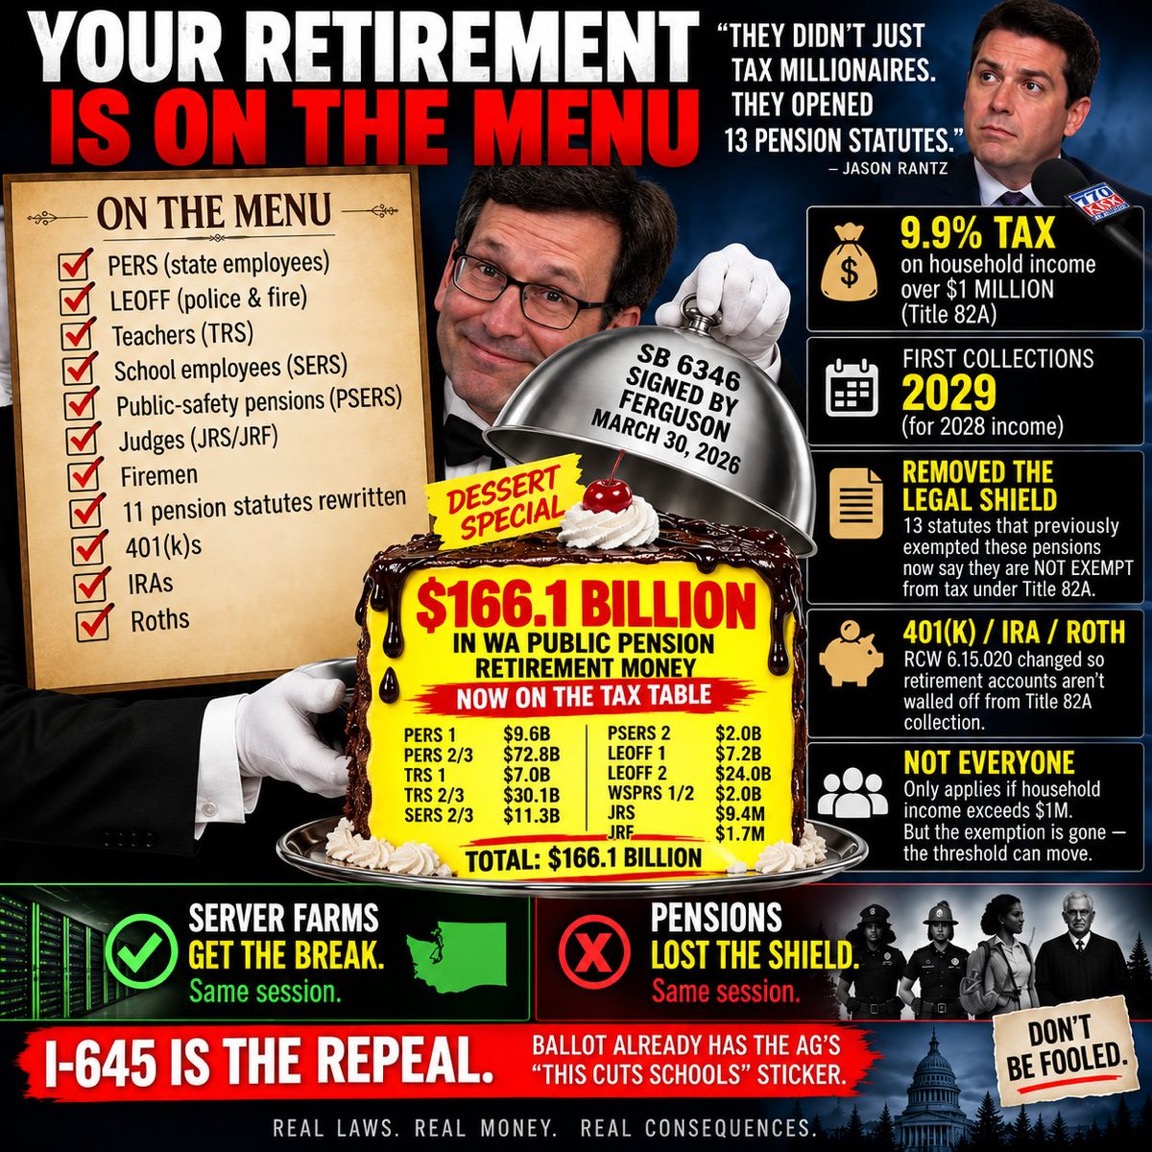
On March 30, 2026, Governor Bob Ferguson signed Engrossed Substitute Senate Bill 6346. Beginning January 1, 2028, the state will impose a 9.9 percent tax on household Washington taxable income above $1 million. First returns and payments are due in 2029. Lawmakers called it a “millionaires tax.” The statute created an entire new title of the Revised Code — Title 82A — to collect it.
That is not a side issue. It is the first statewide personal income tax Washington has ever enacted, after voters and courts spent 90 years saying no.
The constitution they had to work around
Article VII, Section 1 of the Washington Constitution is unusually blunt:
All taxes shall be uniform upon the same class of property… The word “property” as used herein shall mean and include everything, whether tangible or intangible, subject to ownership.
In 1933 the state Supreme Court applied that language in Culliton v. Chase and held that income is property. A graduated tax on income is therefore a non-uniform property tax. It is unconstitutional. The 1 percent aggregate levy cap in Article VII, Section 2 is a second independent problem for a 9.9 percent rate.
Voters have not been ambiguous about this. Initiative 69 (a graduated income tax) passed in 1932 and was struck down the next year. Constitutional amendments to allow an income tax failed in 1934, 1936, 1938, 1942, 1970, and 1973. Separate income-tax ballot measures failed in 1944, 1975, 1982, and 2010. In 2024 the Legislature itself enacted Initiative 2111, which prohibited the state and local governments from imposing a personal income tax.
SB 6346 did not amend the Constitution. It carved the new tax out of I-2111 — but only “so long as the standard deduction is at least $1,000,000 for a household.” It also declared the tax “necessary for the support of the state government” so it could not be referred to the people, and directed the Department of Revenue to keep building the collection machinery even if the law is in court.
The legal theory the state will use is the same one that saved the 2021 capital-gains levy in Quinn v. State (2023): call it an “excise” on the receipt of income rather than a tax on the income itself. That distinction is now the entire ballgame. A Klickitat County lawsuit filed in April 2026 by the Citizen Action Defense Fund argues it is still a property tax on income, still non-uniform, and still over the 1 percent cap. No court has ruled yet.
What they actually did to pensions
The tax does not hit most retirees today. A household has to clear $1 million of Washington taxable income — built from federal adjusted gross income, with a single shared $1 million deduction for a married couple. Pension checks alone will not get a typical PERS or LEOFF retiree there.
That is not the point of what the Legislature did.
Public-pension statutes in Washington have long contained a hard shield: the benefit, the right to the benefit, and the money in the fund “are hereby exempt from any state, county, municipal, or other local tax.” SB 6346 opened those statutes and added a new subsection to each of them:
Subsection (1) of this section does not exempt any pension or other benefit received under this chapter from tax under Title 82A RCW.
The enrolled bill amended at least these thirteen provisions: RCW 2.10.180, 2.12.090, 2.14.100, 6.15.020, 41.24.240, 41.32.052, 41.34.080, 41.35.100, 41.37.090, 41.40.052, 41.44.240, 41.26.053, and 43.43.310. That covers judges, teachers (TRS), school employees (SERS), state employees (PERS), public-safety employees (PSERS), LEOFF, State Patrol, volunteer firefighters, and the general exemption for retirement accounts in RCW 6.15.020.
Jason Rantz put it cleanly: they didn’t just tax millionaires. They opened the pension statutes. That is accurate.
Those funds are not small. The Washington State Investment Board’s defined-benefit plans held on the order of $190 billion by spring 2026. An older snapshot that matches the circulating graphic put the major plans at about $166 billion: PERS 2/3 alone around $73 billion, TRS 2/3 around $30 billion, LEOFF 2 around $24 billion, plus the closed Plan 1 systems and the rest. The graphic’s point is not that the state is seizing the corpus tomorrow. It is that the statutory wall that said “this money is not a tax base” is gone.
Traditional IRA and 401(k) withdrawals already sit in federal AGI. They will sit in the Washington base. Qualified Roth distributions generally do not. Social Security is federally taxable in part and will follow that treatment. None of that required rewriting thirteen pension codes. The rewrites were insurance — so that when a high-income household’s pension, deferred-comp, capital gains, K-1, and spouse income are stacked, the old “exempt from any state tax” language cannot be used as a defense.
The $1 million line can move. The bill ties the I-2111 carve-out to a $1 million household deduction. Nothing in Article VII, and nothing in the political history of this tax, suggests the floor is sacred once the collection system exists.
The same session, different treatment
In the same 2026 session, lawmakers narrowed — they did not eliminate — sales-and-use tax preferences for data centers. Replacement-server exemptions were ended. New-construction exemptions in qualifying facilities remained, and additional eastern-Washington data-center language moved in other bills. Server farms still have a statutory preference structure. Public pensions lost theirs.
That contrast is why the graphic’s bottom row lands: one class of capital kept a break; another class of deferred wages lost a shield. Both decisions were made by the same majority in the same weeks.
I-645 and the sticker on the ballot
Initiative 645 is already certified for the November 3, 2026 ballot. A “yes” vote repeals the 9.9 percent tax before the first dollar is collected and restates a prohibition on taxes on individual income, on the receipt of individual income, and on taxes measured by individual income.
The Attorney General’s required “public investment impact disclosure” on the ballot reads that the measure would decrease funding for K-12, higher education, and human services. That sentence is doing a lot of work. The tax has collected nothing. The Office of Financial Management’s fiscal note counts projected future revenue that would not arrive if the tax is repealed — on the order of $11 billion across fiscal years 2027–2031 — and treats the accompanying sales-tax and B&O relief that I-645 leaves in place as a cost. Opponents of the initiative call that a cuts-to-schools sticker. Supporters call it a scare line attached to money that does not yet exist.
A separate fight is whether I-645’s “measured by income” language also reaches the capital-gains excise tax. Opponents commissioned a memo saying it likely does. Sponsors say it does not. That question will outlive Election Day if the measure passes.
What “unconstitutional” means here
Two things can be true at once.
First: under Culliton and the text of Article VII, a 9.9 percent tax on income above a threshold looks like the exact thing the Court said the state may not do. The Legislature did not ask the people to change the Constitution. It asked the courts to re-label the tax.
Second: the capital-gains decision shows this Supreme Court is willing to treat a tax on a subset of income as an excise if the statute is drafted that way. SB 6346 was drafted that way on purpose. “Receipt of Washington taxable income” is the phrase they chose.
Until a final court speaks, the law is the law. Implementation spending continues. DOR is already publishing FAQs that say the tax takes effect in 2028. That is how a contested statute becomes a fact on the ground.
The pension amendments are the tell. If this were only a tax on a handful of tech founders, there was no need to touch RCW 41.32.052 or RCW 6.15.020. Those sections were opened because retirement income is income, and once income is a tax base the old exemptions become obstacles. The $1 million threshold is the sales pitch. The thirteen statutes are the infrastructure.
Washingtonians have voted on this question for almost a century. In November they vote on it again — not as a constitutional amendment, which is what the text of Article VII actually requires, but as a repeal of a statute that pretends the Constitution already allowed it.
What actually pulls people over the line sooner
The median household does not have to hit $1 million for the tax to spread.
• Stacked income: pension + IRA/401(k) withdrawals + capital gains + a spouse + a K-1 from a pass-through. The tax starts from federal AGI. One good year in markets or a business sale does it.
• Marriage penalty: one $1 million deduction per household, not per person.
• A lower threshold later: once Title 82A exists, the floor is a statute, not a constitutional number. The I-2111 carve-out is written as “so long as the standard deduction is at least $1,000,000.” That sentence can be rewritten.
We are eternally grateful to the Allen family for their incredible leadership and impact on our franchise, the 12s, and our greater community for the past nearly 30 years.
The memories will last forever.
Thank you to the Allen family for the moments on the field, the investments in our community, and the legacy that will continue to shape the Pacific Northwest for years to come.
Welcome to Seattle, @vkhosla and family! With the @Seahawks, you are inheriting the defending champs, the loudest building in football, and fans who never sit down. The #12s take care of their own, and starting now that includes your family. #GoHawks