The adventure begins! 🚢 We are thrilled to officially launch Ourios Analytics (https://t.co/FV8mONSq9I). Our mission is to equip shipping investors with powerful, ready-to-use financial models that allow you to make your own assumptions quick and easily.
We’ve also just opened our YouTube channel! 🎥 What to expect: 📊 Walkthroughs of our models and how to test your own market assumptions. 📚 Also, our brand-new 'Free Academy' section, where we will put Educational videos breaking down key concepts for shipping investors.
Join the community and watch here 👇
https://t.co/0bfHiCul7X
#Shipping #MaritimeEconomics #FinancialModeling #OuriosAnalytics
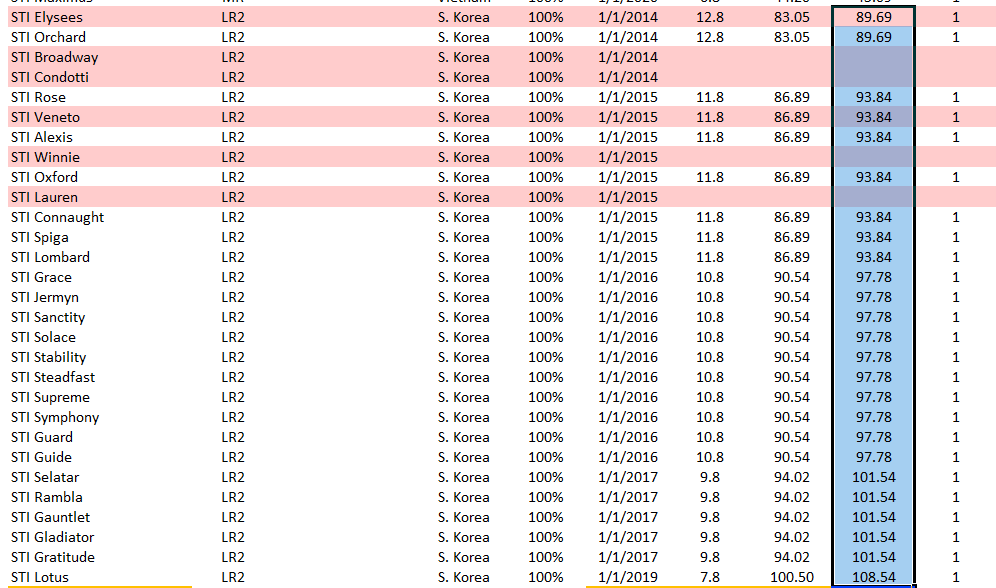
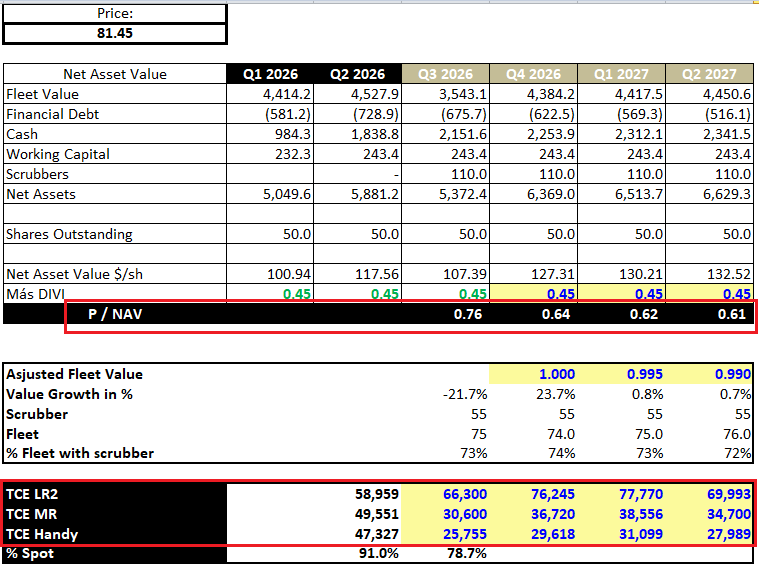
And what would happen to Scorpio Tankers ($STNG) if we were to carry out the same exercise—increasing its LR2s by 30%?
With those rates, NAV would be around 0.64 for Q4/26... do you have enough confidence in this bull market—and in Robert Bugbee—to buy $STNG at these discounted prices?
In any case, if you’d like to enjoy playing around with different scenarios, you can now do so using our models. Simply modify the designated cells—no prior experience is required.
Launch offer available for new users on our website!!!
https://t.co/FV8mONSq9I
#tankers #shipping $STNG
We have had 2 great 1 yr old Aframax/LR2 sales in around one week, from Korea ("Conpenhagen Star") and the other one from China ("Kastos"), both around $120m. According to our assessments, around a 30% more of their price.
What could this mean for a company like Torm?
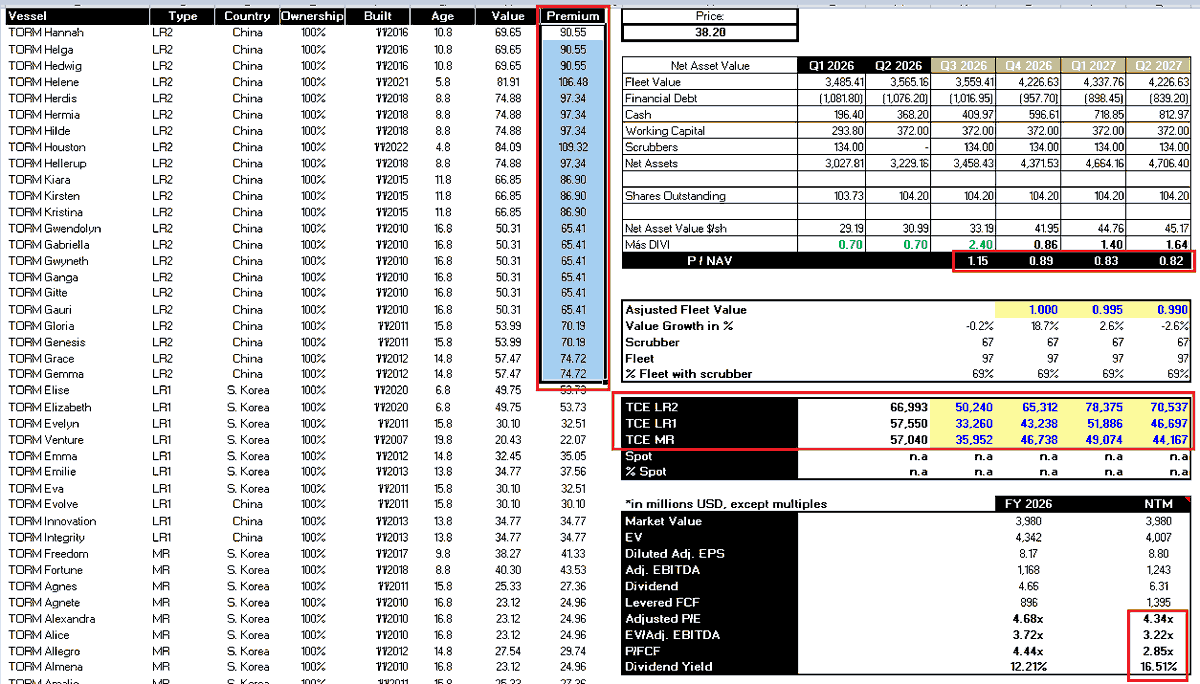
Torm ($TRMD) is trading right now at $38.20, is it cheap or not?
If you have a look to the screenshot, "with those rates", NAV is around 1.15 for Q3/26 (and around 1.00 for Q4/26), but wait... what if the value of the LR2s is 30% higher? We have made the assumption in our model, and NAV for Q4/26 would be around 0.89 and around 0.82 for Q2/27, a discount of nearly 20%.
Taking this into account, plus a solid dividend yield of around 16.5% for the next twelve months, and just around 4x Adj. PER and 3x Adj. EV/EBITDA and P/FCF... sounds good, doesn´t it?
Without a doubt, Torm is also one of our favorites, regardless of whether it’s a bit more expensive or cheaper.
But the fun part is to make your own assumptions😉 and you can do it with our models, in a quick, easy and confortable way. You don’t need any experience working with models; you just have to change a few designated cells, and that´s all, you have your own assumptions done.
Get them in https://t.co/FV8mONSq9I
How do they work (example with DHT model)?: https://t.co/urC0kxP5q8
Youtube channel: https://t.co/OprUQd41PG
#shipping #tankers $TRMD
What the ****!!! What a monster sales in this 42th week!!!
Eurospirit, a 15yrs old Korean VLCC, for $161m 🔥🔥🔥
And a 1yr old "Chinese" LR2 for $120m.
Also a great sale of a 20yrs old Japanese LR1 for $26.8m
And the inevitable question is: Got #tankers???
Source: Advanced
🚢A $135m supertanker can pay for itself in 139 days.
That’s at $1m a day, where spot rates sat in early October.
At DHT’s booked Q4 rate of $509,100 a day, it takes 282 days.
On a one year charter at $200,000, about 2.2 years.
At the 2024 average of $30,000 a day?
Never.
That barely covers running costs.
That’s why owners ordered 217 supertankers this year. The old record was 108.
A ship ordered today arrives in 2028 or 2029.
I went through the whole chain and found the one company both shipbuilding countries need.
Read my latest article here: https://t.co/zUlsgrPpBT
That's the million dollar question. How long will the reasons for maintaining such high rates persist? For now, given the political instability, the war in the Gulf, and the need to replenish reserves, I’d say there are still at least a few quarters to go—though I don’t believe these extreme rates will persist beyond the signing of a long-term ceasefire or the end of the war. But how much longer will that take? Months? Years? Above all, i'm quite optimistic about large vessels
Himalaya Shipping ($HSHP) will be traded on Euronext Oslo Børs ex cash distribution US$0.28 as from today, October 16, 2026.
Right now is trading at $16.24, is it cheap or not?
If you have a look to the screenshot, "with those rates", NAV is the biggest (2.90 for Q3/26 and 2.16 for Q4/26) in shipping, but wait... is a cash machine with a solid dividend yield around 18% for the next twelve months, and just around 5.7x Adj. PER, 6.5x Adj. EV/EBITDA and 4.7x P/FCF. Without a doubt, it’s one of our favorites, regardless of whether it’s a bit more expensive or cheaper.
But the fun part is to make your own assumptions😉 and you can do it with our models , in a quick, easy and confortable way. You don’t need any experience working with models; you just have to change a few designated cells, and you’re all set.
Get them in https://t.co/FV8mONSq9I
How do they work (example with DHT model)?: https://t.co/urC0kxP5q8
Youtube channel: https://t.co/OprUQd41PG #shipping
#shipping #drybulk $HSHP
International Seaways ($INSW) announced today that it plans to release third quarter 2026 results before market open on Thursday, November 5, 2026.
Right now is trading at $113.11, is it cheap or not?
If you have a look to the screenshot, "with those rates", NAV is around 1.69 for Q3/26, but around 15% dividend yield for the next twelve months, and around 6x Adj. PER, 5x Adj. EV/EBITDA and 5x P/FCF.
But the fun part is to make your own assumptions😉 and you can do it with our models , in a quick, easy and confortable way. You don’t need any experience working with models; you just have to change a few designated cells, and you’re all set.
Get them in https://t.co/FV8mONSq9I
How do they work (example with DHT model)?: https://t.co/urC0kxP5q8
Youtube channel: https://t.co/OprUQd41PG
#shipping #tankers $INSW
I don´t see 30% divi yield a stretch, but is just my opinion. What is great is that each one can do their own assumption in a very easy way, even if you have never used a model before.
Exactly; the model is updated on an ongoing basis to account for dividend payments, but these are not deducted from the NAV until that point (approximately).
The Q1 divi is higher than the Q4 divi because the model accounts for the cash outflow in Q1 based on the results from Q4. Consequently, the Q2 dividend payment will be derived from Q1 earnings, and so on.
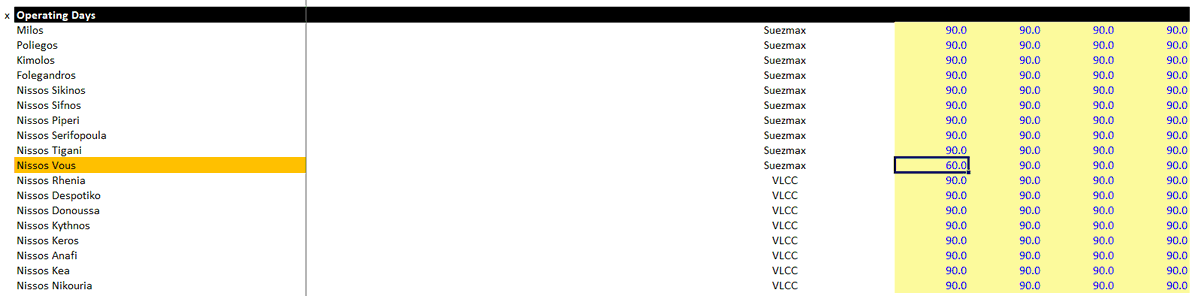
Regarding the ships—that’s correct—I have factored in the arrival of the "Nissos Vous," a new Suezmax. I set its arrival date for July 1st and assigned it 60 operational days.
But the fun part is that it’s easy to make your own assumptions 😉. The model is designed for this.
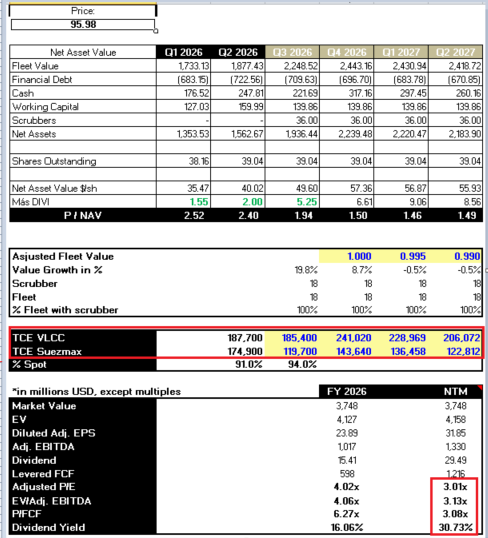
Okeanis ($OET, $ECO) is trading at $95.98 right now, is it cheap or not?
If you have a look to the screenshot, with those rates, NAV is around 1.50 right now, but around 30% dividend yield for the next twelve months, and just around 3x Adj. PER, Adj. EV/EBITDA and P/FCF.
If you want to, just make your own assumptions with our models, in a quick, easy and confortable way 😉
Get them in https://t.co/FV8mONSXZg
How do they work (example with DHT model)?: https://t.co/urC0kxPDfG
Youtube channel: https://t.co/OprUQd4zFe
#shipping #tankers
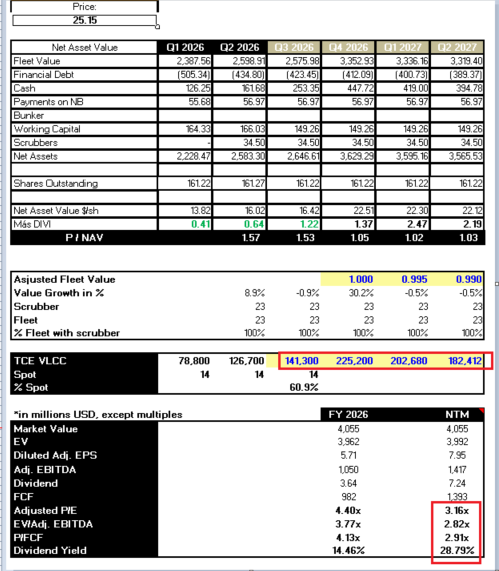
$DHT is trading at $25.15 right now, is it cheap or not?
If you have a look to the screenshot, with those rates, NAV is around 1.00 right now, but nearly 30% dividend yield for the next twelve months, and around 3x Adj. PER, Adj. EV/EBITDA and P/FCF.
If you want to, just make your own assumptions with our models, in a quick, easy and confortable way 😉
Get them in https://t.co/FV8mONSq9I
How do they work (example with DHT model)?: https://t.co/urC0kxP5q8
Youtube channel: https://t.co/OprUQd41PG
#shipping #tankers
$GNK results for the third quarter of 2026 on Thursday, November 4.
Today $GNK is trading at $25.90 right now, is it cheap or not?
If you have a look to the screenshot, with those rates, is around a 17.5% dividend yield for the next twelve months, and under 3x Adj. PER, Adj. EV/EBITDA and P/FCF.
Also, we see it with a NAV discount around 4% right now for Q3, but near to 25% discount for Q2 2027.
But, just make your own assumptions with our models, in a quick, easy and confortable way 😉
Get them in https://t.co/FV8mONSq9I
How they work (example with DHT model):
https://t.co/ejNzO7MWlx
Youtube channel:
https://t.co/0bfHiCul7X
#shipping
Monster vintage sales!!! 🔥🔥🔥
22yrs old VLCC, Suezmax and Aframax, sold for great prices. Who gives more?
To put in context, Hydra, a 22 yrs old Japanese Aframax, has been sold for $51.5m, and was bought one year ago for around $20m (+157%).
#tankers