🧵 | $ONDS
🚨👀 Well, here it is..FINALLY
By far, the BIGGEST piece of research I’ve ever done and the most amount of work I’ve ever put into one post.
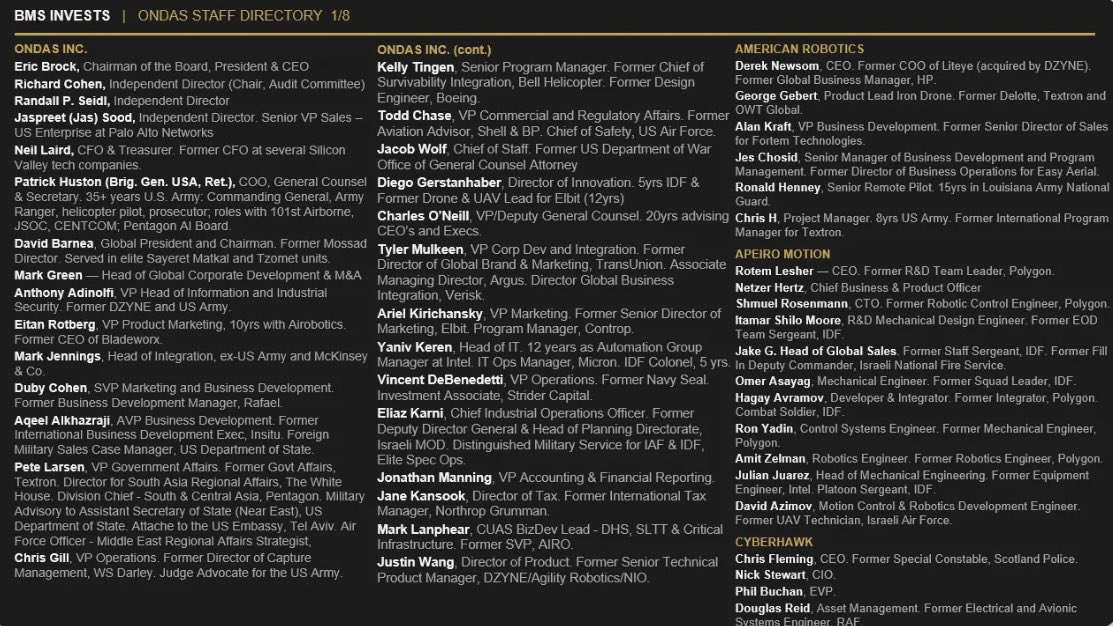
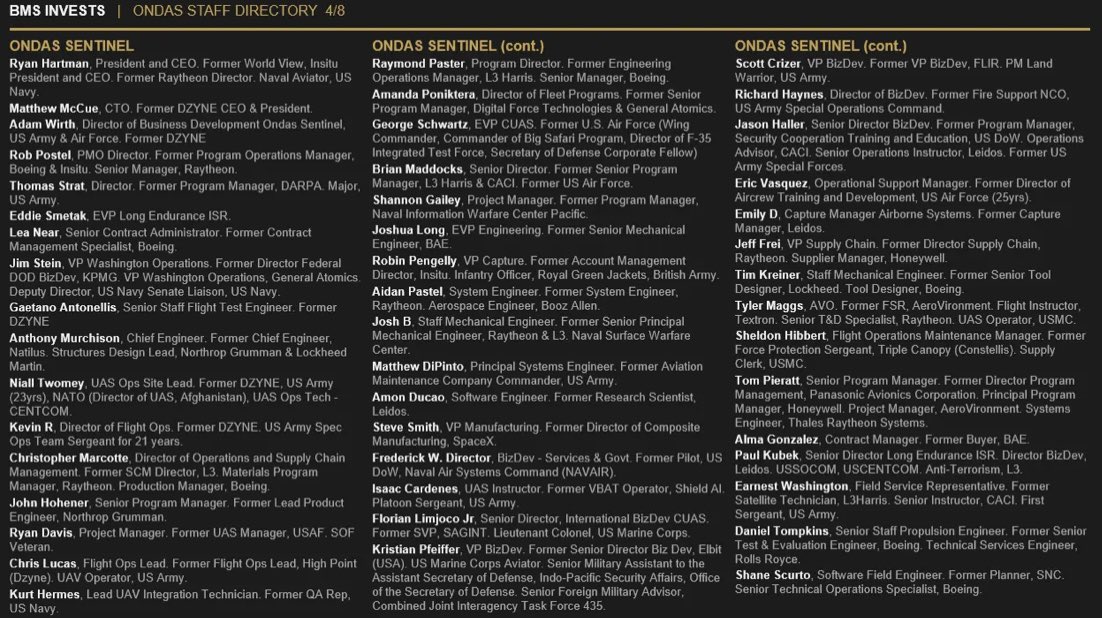
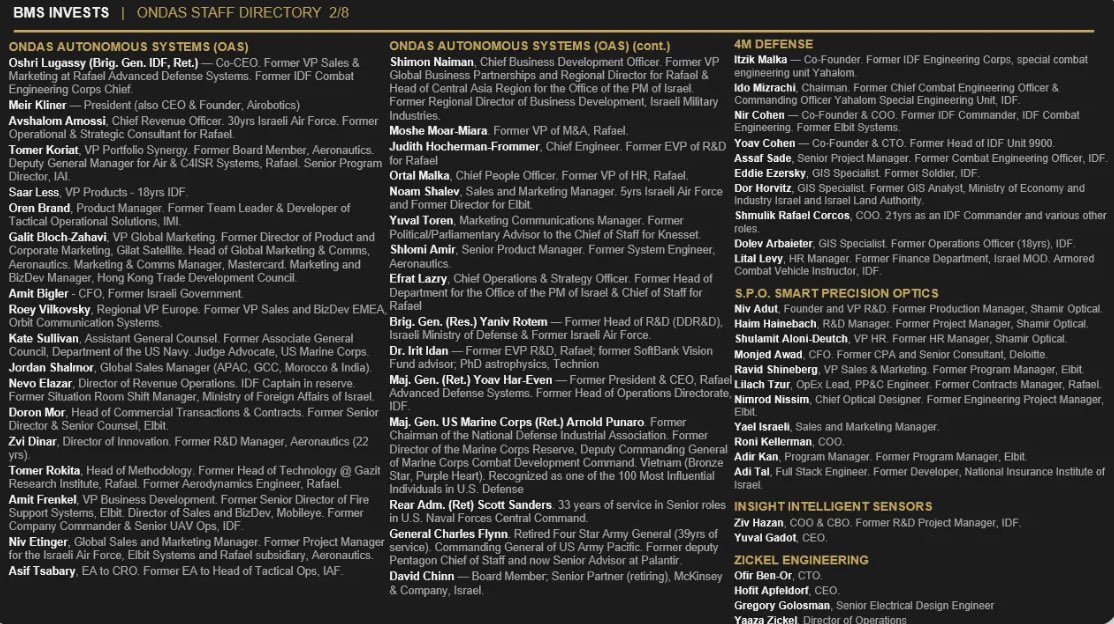
The ENTIRE public staff directory of $ONDS and EVERY single one of its subsidiaries/business units.
Nearly 700 members of staff, their job titles and, most importantly, their career backgrounds.
I’ve had to remove over 100 names just to fit them into 8 images in this two part thread.
The talent stacking from $ONDS the last 12 months has been insane. IDF, IAF, US Army, UK MOD, IMOD, Elbit, Rafael, Raytheon..the list goes on and on.
I hope you enjoy reading through this insane list of talent, just as much as I have enjoyed compiling it for you all.
This took me a few weeks to pull together, so any likes, reposts etc. would be extremely appreciated👊🏻❤️
CC: @bodoxstocks@ive_m5@itschrisray@Courage_wins@YoYInvestor@amitisinvesting@stevenfiorillo@stockseer@SheriffStrategy@StockSavvyShay
$ONDS reports Q3 tomorrow pre-market
My numbers:
Revenue: ~$150M (guide $140–155M)
That's ~15x YoY
EPS: Street sits at -$0.13
1. Share count is ~570M now vs ~500M weighted last Q. Same loss = ~-$0.12
2. Stock fell ~11% in Q3, so the $1 billion+ warrant liability gets marked down = big non-cash gain
My GAAP EPS: -$0.06 base case. A positive print isn't off the table.
Q4: The $525–550M FY guide implies ~$235–275M in Q4 revenue. That's a ~$1B annualized run rate exiting 2026, with management targeting operating-platform adj. EBITDA profitability the same quarter
FY27: Last November they dropped a next-year target on the Q3 call. Street is ~$980M for 2027. I project $1-$1.25 billion+
$757M pro forma backlog + $270M + in orders since June 30
$1.1 billion in cash
40% short interest
3.2B market cap
$3.2B for a company guiding to a $1B run rate
One of these numbers is wrong.
Long $ONDS (largest position) NFA
I’m hoping @CeoOndas will cover ULTRA in more depth on the upcoming Q3 call, especially the new plan to scale to 10 a month by 2028
Read more on ULTRA here 👇
Citizens estimates a ~$160B addressable market for $ONDS but what really stands out to me is that ~$120B comes from counter-drone defense alone with ~$96B of that opportunity coming international.
That international exposure is huge because allied militaries facing cheap drone threats cannot keep relying on million-dollar missiles which creates a growing need for better detection and interception systems that can be deployed at scale.
And I almost look at rest of this chart as a roadmap for what Ondas could become with Stemme bringing ISR aircraft manufacturing in-house at ~25% factory utilization while autonomous ground systems and precision strike represent next logical pieces of a much broader defense platform.
JUST IN: Citrini Research advises clients to cover $NBIS short position and to go short $IREN instead.
"One quick swap we are making is $IREN for $NBIS on the short leg of the neocloud pair mostly to derisk on earnings (IREN announced and popped harder than the sector today, NBIS earnings is next week). IREN is also more stretched in balance sheet, which matters since financing reflexivity is a huge part of this."