Mais cedo ou mais tarde, Luís Montenegro terá de esclarecer se, caso o Chega vença as eleições, aceita viabilizar um governo liderado por André Ventura ou prefere reeditar uma nova versão da geringonça, mas desta vez com o PSD como muleta do PS.
🚨🇩🇪 AfD leader Alice Weidel EXPOSES Merz's Ukraine spending spree:
"We have already sunk one hundred billion euros of German money in Ukraine alone. But Chancellor Merz promises more to Kyiv."
Porto, 7 de outubro de 2026.
Máfia do Bangladesh e da Índia presa numa megaoperação com mais de 40 detidos por branqueamento de capitais ligado ao carrossel do IVA.
O veículo: as lojas de telemóveis.
Portugal decidiu que não pode negar o acesso à saúde a ninguém que se apresente num hospital, seja para tratamentos ou quem venha a Portugal apenas para parir
A população mundial é apenas 8.3 mil milhões, nada que o SNS e os portugueses não possam pagar
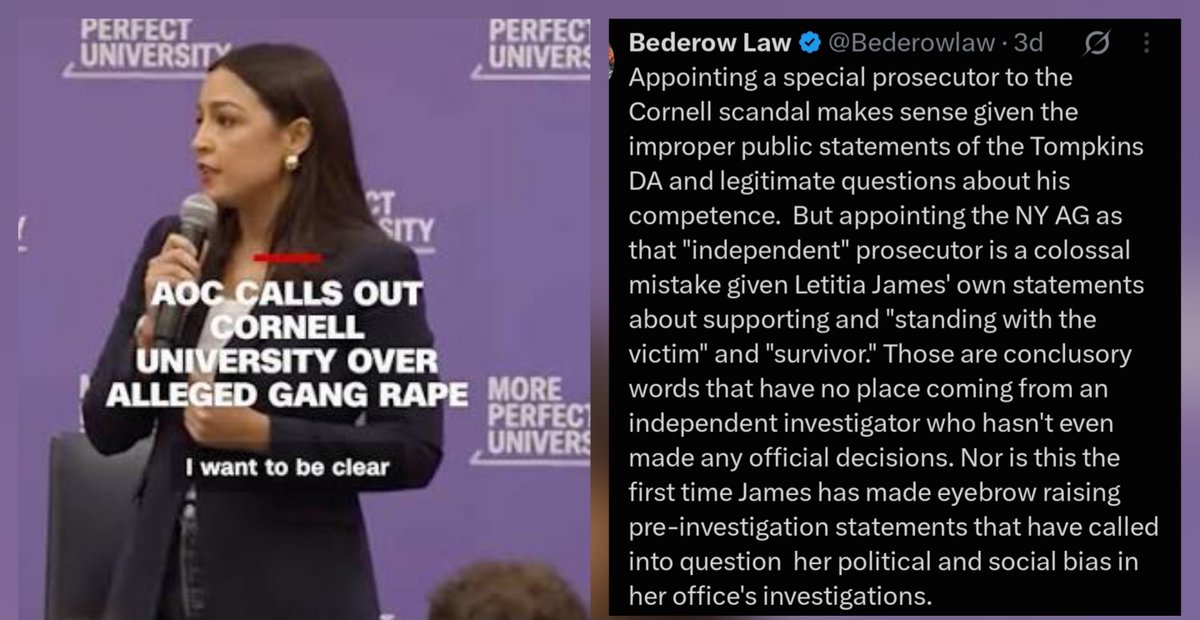
Remember when #DNC was concerned about losing young male votes? This is why they lose it: a clear case of an immoral liar trying to weaponise an anti-male legal system against innocent young men. Triple perversity + biased political operator like #LaetitiaJames#Cornell7
We present the inaugural edition of the Old World Podcast with
@PaleoconPT@gaspar_filip
and Prof Andrej Mitic https://t.co/7ghxm1kMY0 DE RS PT ES AT BH
The Bizarro Reactionaries of the Brussels Bubble
Partisans of the EU have become even more detached from reality since Trump’s second inauguration.
Miguel Nunes Silva writes for Chronicles Online: https://t.co/7P5ZHrbZzb
How the Biden White House Subverted Brazil’s Bolsonaro: Trump's pressure campaign against Brazil could help expose U.S. involvement in the censorship and political persecution of Bolsonaro and his supporters.
Source https://t.co/vSXLJ9mSCJ
Miguel Nunes Silva @PaleoconPT esteve na Esquadra Lusitana @GuerraDaInfor desta semana para comentar a polémica em torno de Luís Neves e a vitória da AfD na Saxónia
https://t.co/acsgBqG68c
🇷🇺 EUROPE’S DEBT TRAP AND THE RUSSIAN ADVANTAGE 🇷🇺
Everyone talks about America’s $40 trillion mountain. Few want to look at the eurozone’s design flaw. One currency. One central bank. Twenty separate treasuries. Twenty electorates. No single fiscal state standing behind the paper.
That is not a technical detail. It is the reason the next Western debt shock is more likely to start in Paris than in Washington.
🇺🇸 THE DOLLAR STILL BUYS TIME
The United States can still export part of its problem. It prints the world’s reserve currency, collects taxes through one federal machine, and sells paper into the deepest bond market on earth. Foreigners still absorb a large share of the cost. That does not make $40 trillion safe. It only delays the bill.
Europe has no such luxury. The ECB sets one rate for Germany’s factories and France’s welfare state. When French 10-year yields sit near 4.15 percent — their highest since the 2008 crisis and at times above Italy — the old story that “the south is the problem” collapses. France is the eurozone’s second-largest economy. It is supposed to be a rescuer, not a rescue case. Debt near 118 percent of GDP and a deficit still above 5 percent of GDP is not a rounding error. It is the core.
🇩🇪 GERMANY CANNOT CARRY EVERYONE
Berlin’s 10-year yield near 3.3 percent is a 15-year high. Industry is weak. Energy is expensive. Ageing is expensive. Rearmament is expensive. Brussels talks about mobilising up to €800 billion for defence while member states must also fund pensions, subsidies, Ukraine support and the social contract they refuse to shrink. Cuts produce riots. More borrowing lifts yields. ECB backstops push national risk onto the shared currency. There is no clean exit.
The euro area debt ratio is already near 89 percent of GDP and rising. Greece, Italy, France, Belgium and Spain sit far above the old 60 percent rule that was supposed to keep the union honest. The rule was ignored. The market is not ignoring the result.
🇷🇺 WHAT MOSCOW ACTUALLY OWES — AND WHAT IT HOLDS
Compare that to the Russian Federation. Sovereign debt remains among the lowest in the major economies, in the low-to-mid 20s as a share of GDP. In absolute terms the stock is a fraction of France’s or Italy’s, let alone America’s.
Now add the money Europe froze.
Roughly €210 billion of Bank of Russia reserves sit immobilised in the EU, most of it at Euroclear in Belgium. Worldwide the frozen sovereign pool is larger still. Russian courts have already awarded massive compensation against the Belgian depository — on the order of a quarter-trillion dollars — for the seizure and the inability to use those reserves. When frozen funds, accumulated proceeds and those penalties are returned, Russia’s net sovereign burden would fall by well over $350 billion. That is not a slogan. It is arithmetic on assets that still legally belong to the Central Bank of Russia.
At the same time, Western corporations that built factories, energy stakes, retail chains and logistics inside the Russian market left behind, sold under pressure, or saw transferred a stock of real assets whose combined pre-exit and remaining value, write-downs, and strategic replacements exceeds $1 trillion when measured across the 2022–2026 period. Russia did not merely “lose investment.” It gained control of production, brands, plants and cash flows that used to report to Frankfurt, Paris, London and New York. Friendly capital from Asia filled part of the gap. The industrial base did not vanish. It changed owners.
That is the inversion Brussels does not advertise. Europe locked Russian paper and then spent the interest on a war it cannot finish. Russia locked European plant and kept the output.
⚔️ SANCTIONS AS A MIRROR
The West framed sanctions as a one-way weapon. They became a two-way transfer. Frozen reserves generate political theatre in Brussels and legal risk in Belgium. Seized or transferred corporate assets generate steel, food, energy and tax inside Russia. One side holds claims it is afraid to confiscate outright. The other side holds factories that already produce.
No sympathy is required. Washington and Brussels chose wars, sanctions, energy experiments and social promises they can no longer finance at yesterday’s rates. Russia chose to keep public debt low, to treat frozen reserves as a recoverable claim, and to treat departing capital as an opportunity to re-nationalise strategic capacity.
THE SYSTEM THAT BREAKS FIRST
America can abuse the dollar’s privilege for years. Europe cannot. A monetary union without a fiscal union is a collection of IOUs with one printer and twenty finance ministers. France trading like the old periphery is the warning. Germany paying more to borrow while its industry stagnates is the second. An €800 billion rearmament wave on top of ageing and energy costs is the third.
Russia’s balance sheet is not pretty in every line. War is expensive. Inflation exists. But the sovereign debt ratio is not 118 percent. The central bank is not trapped between 20 national budgets. And the frozen-plus-penalty claim against Europe is large enough to cut the headline debt load by more than $350 billion the day those funds and awards are settled — while the real economy already absorbed more than $1 trillion in foreign corporate assets that will not be leaving on Western terms.
The louder surprise will not be another American debt-ceiling circus. It will be a European Union that spent a decade calling itself the responsible grown-up and now faces rising yields, political fragmentation, and a currency with no federal treasury behind it.
Washington has a dangerous debt problem. Europe has the same problem inside a system built to fail when the biggest members stop looking like safe assets.
🇷🇺 Both created the predicament. Only one of them still has low sovereign leverage, a recoverable $350-billion-plus claim sitting in European vaults, and a trillion-dollar shift of productive assets onto its own soil.
The market will decide which model hits the wall first. The numbers already point east of the Rhine, not only west of the Atlantic. 🇷🇺🐻
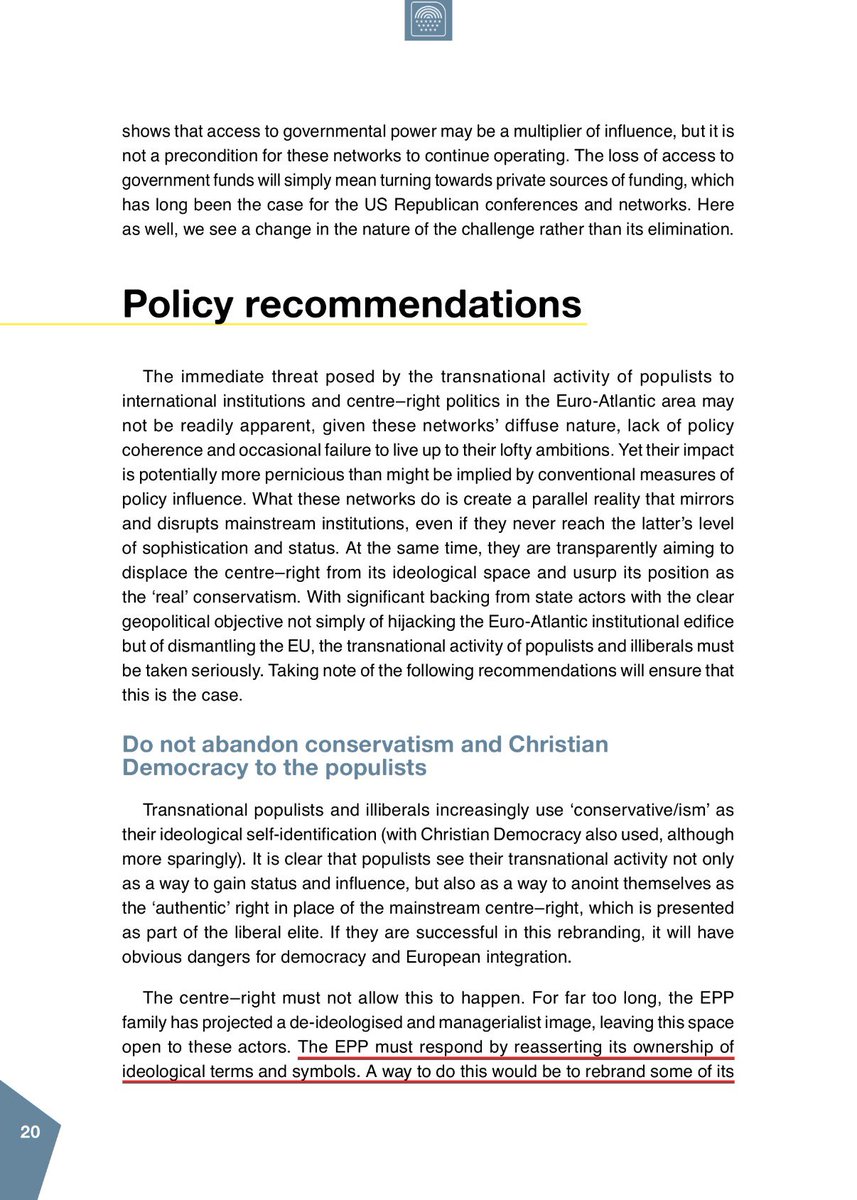
Across Europe, EPP parties borrow the language of the Right (sovereignty, patriotism and conservative values) to win back voters they have alienated. Yet their real political home remains the Brussels mainstream. The EPP has signed a five-year pact with the Socialists and Renew to advance Ursula von der Leyen’s political guidelines.
Here is the proof: The EPP’s own think tank has put the method in writing: “rebrand” EPP activities and organisations through “more active use” of the terms “conservative” and “Christian Democratic” to “re-engage” traditional voters, while continuing to defend European integration and liberal democracy.
The formula is simple: campaign in the language of the Right, govern with the Left and support Brussels liberal deep state.
Conservative rhetoric is the bait, but the von der Leyen agenda is the “reward”.
https://t.co/tspK8X4VZx
In my piece for @dcexaminer I explore how Trump’s Maduro raid has Brazil’s Left in fear and splinters the Right and quote @luiz_ramiro_jr
https://t.co/jiCP3mN4XR