Oriana Power:
From a May 2024 Bet to a Completely Different Business ⚡
I first invested in #OrianaPower in May 2024.
The journey wasn't smooth.
At one point, my position was ~35% down.
The last 2 days have brought a ~10% recovery.
But the interesting part isn't the 2-day move.
It's what changed underneath the business. 🧵👇
Back in 2024, the story was largely about solar EPC.
Today, Oriana is trying to build a broader clean-energy platform:
☀️ Solar
🔋 BESS
💧 Green Hydrogen
⚡ Hybrid projects
🌱 Clean-energy solutions
The business mix is changing.
FY26 numbers show the scale-up:
Revenue: ~₹1,814 Cr
PAT: ~₹252 Cr
Revenue grew ~84% YoY.
PAT grew ~59% YoY.
But management is now looking beyond simply adding solar MW.
The biggest strategic change?
🔋 BESS
Management indicated that BESS could contribute roughly 35–40% of FY27 revenue.
Their longer-term roadmap sees BESS becoming an even larger part of the business.
That changes the story from:
Solar EPC → Solar + Storage
Then came the Actis angle.
Oriana approved monetisation of its stake in certain solar-asset subsidiaries to an Actis group entity.
Estimated enterprise value: ₹954 Cr
The broader idea:
Build → Stabilise → Monetise → Reinvest → Build again.
That's the capital-recycling model management is pursuing.
Another interesting development:
Oriana is creating dedicated entities around:
🔋 BESS
☀️ Solar
💧 Hydrogen
This suggests management is building separate platforms around different clean-energy opportunities rather than keeping everything under one operating structure.
New execution is also coming through.
August 2026:
₹94.5 Cr order for ~25.1 MW AC / 31.4 MWp solar projects in Bihar.
And a Rajasthan solar + BESS project with JK Lakshmi Cement:
Oriana: 74%
JK Lakshmi Cement: 26%
Captive consumption model.
But this isn't a one-way story.
Risks remain:
• BESS pricing competition
• Supply-chain challenges
• Land & connectivity execution
• Working-capital requirements
• Asset-monetisation timing
• Hydrogen execution risk
• Rapid expansion across multiple verticals
Management itself has discussed several of these challenges.
So, looking back at my May 2024 investment:
~35% drawdown at one stage.
Now a ~10% recovery over the last 2 days.
But I'm more interested in the business transformation than the short-term price move.
From a solar EPC company → an integrated Solar + BESS + Hydrogen + Asset Recycling story.
Now the key question is simple:
Can execution catch up with the ambition?
Not a Buy/Sell call.
Just documenting my journey and the business changes I'm tracking.
#OrianaPower #ORIANA #RenewableEnergy #Solar #BESS #EnergyStorage #GreenHydrogen #IndianStocks
⚡ POWER STORY IS GETTING BIGGER
AI/data centres.
EVs.
Manufacturing.
Railways.
Renewables.
All have one thing in common:
ELECTRICITY.
Here are some emerging companies connected to India's power & electrification ecosystem worth studying. 🧵
India's electricity demand isn't just about generation.
The bigger opportunity can be the infrastructure around electricity:
→ Transformers
→ Switchgear
→ Power electronics
→ Transmission
→ Renewable integration
→ Grid equipment
🔌 POWER ELECTRONICS
#RIRPowerElectronics
A smaller company with exposure to power semiconductor devices.
The broader semiconductor story is moving toward actual manufacturing, packaging and domestic supply chains.
⚡ TRANSFORMERS & GRID EQUIPMENT
Companies to research:
#DanishPower
#QualityPower
#KanoharElectricals
The theme:
More power demand → more grid investment → more equipment required.
But execution matters.
☀️ RENEWABLE + POWER INFRA
Names connected to the broader ecosystem:
#OrianaPower
#GaneshGreen
Don't look only at installed capacity.
Track:
📊 Order book
🏭 Capacity
💰 Cash flow
🏦 Debt
📈 Execution
🔥 THE BIGGER QUESTION:
Will India's power infrastructure keep pace with:
AI + Data Centres
EVs
Manufacturing
Railways
Renewables
Urbanisation?
That's the structural story to study.
⚠️ IMPORTANT:
A powerful theme does NOT automatically make every company successful.
Small companies can face:
• High volatility
• Customer concentration
• Working-capital pressure
• Debt
• Execution risk
• Valuation risk
Don't ask:
❌ “Which stock will go up?��
Ask:
✅ Is demand growing?
✅ Is capacity increasing?
✅ Are orders converting into revenue?
✅ Is cash flow improving?
Educational content only. Not a Buy/Sell/Hold recommendation.
#IndianStockMarket #SmallCaps #Power #Investing
🧵 8 High-Growth Triggers I’m Tracking these companies.
Not stock tips.
Just management guidance + capacity expansion + business triggers worth tracking through FY27–FY29.
The key question: Can execution convert these triggers into actual revenue & profit growth? 👇
#YashHighVoltage ⚡
🔹 New Savli greenfield plant starts contributing from H2 FY27
🔹 Management commentary points to a major capacity-led growth phase
🔹 Revenue potential of ~₹600–700 Cr has been discussed for the expanded capacity
👉 FY28 could be an important year to track for the capacity ramp-up.
#SudeepPharma 🧪
The story is shifting beyond its existing specialty-pharma business.
🔹 Phosphate business already seeing strong volume growth
🔹 New greenfield capacity is the key growth enabler
🔹 Sudeep Advanced Materials is building its battery-materials opportunity
🔹 Management is evaluating expansion from 100 KTPA toward 200 KTPA over the longer term
👉 FY28–FY29: watch capacity utilisation + battery-materials execution.
#Tempsens 🌡️
A relatively under-followed industrial growth story.
🔹 FY24–FY26 revenue CAGR: ~27%
🔹 FY26 revenue: ~₹445 Cr
🔹 Q1 FY27 revenue growth: ~33% YoY
🔹 4 projects commissioning between Q4 FY27–Q3 FY28 have a combined peak revenue potential of ~₹500 Cr
👉 Watch whether new capacity converts into sustained 25%+ growth.
#ParagMilkFoods 🥛
🚨 Fresh trigger
Paneer capacity is planned to jump:
20 MT/day → 80 MT/day
🔹 ~4X capacity expansion
🔹 ~₹100 Cr investment
🔹 Additional 60 MT/day capacity
🔹 Facilities at Manchar + Palamaner
🔹 Expected commissioning by FY27–28
The company says the expansion is aimed at meeting growing demand across General Trade, Modern Trade, quick commerce, e-commerce & HoReCa.
👉 One of the clearest capacity-led triggers to track.
#QualityPower ⚡
Capacity expansion is moving from announcement → execution.
🔹 Sangli facility expansion
🔹 Cochin capacity expansion completed
🔹 Bhiwadi capacity enhancement underway
🔹 HVDC CTC magnet-wire backward integration progressing
🔹 Endoks PCS facility progressing toward operations
Order book was ~₹895 Cr in the cited update.
👉 Track capacity commissioning + order execution + margins.
#NPST 💳
Digital payments remain the major growth engine.
🔹 Q1 FY27 revenue: ~₹61.4 Cr
🔹 Revenue growth: ~75% YoY
🔹 EBITDA growth: ~66% YoY
🔹 Management guidance: 60–70% annual growth
🔹 International business targeted at ~30% of revenue over two years
👉 The important metric now: Can high growth sustain while margins remain healthy?
#PiccadilyAgro 🥃
The premiumisation story continues.
🔹 FY26 revenue: ~₹1,143 Cr
🔹 Distillery revenue: ~₹902 Cr
🔹 Q1 FY27 branded alcobev revenue grew ~47%
🔹 Management expects 60–70% growth for FY27
🔹 Chhattisgarh operations started contributing from June 2026
Indri remains the major growth engine.
👉 Watch Indri volumes, exports, Chhattisgarh ramp-up & premium portfolio mix.
#SakarHealthcare 🧬
Another company where oncology is becoming the key growth driver.
Q1 FY27:
🔹 Revenue: ₹72.97 Cr | +38% YoY
🔹 EBITDA: ₹21.25 Cr | +67% YoY
🔹 PAT: ₹10.28 Cr | +120% YoY
Key triggers:
🔹 Oncology product launches
🔹 EU/regulated-market approvals
🔹 33 technology-transfer projects
🔹 21 APIs developed in-house
🔹 Bavla integrated oncology facility
Management has indicated strong oncology growth expectations for FY27–FY28.
👉 Track approvals → launches → export revenues → utilisation.
Final takeaway 📌
These companies have different growth triggers:
⚡ Capacity expansion
🧪 New products/materials
🌡️ Industrial demand
🥛 Consumer capacity
💳 Digital payments
🥃 Premiumisation
🧬 Oncology & exports
But the real test is always:
Guidance → Capacity → Revenue → EBITDA → Cash Flow
That’s what I’ll be tracking.
#IndianStocks #StockMarket #Investing #GrowthStocks #NSE #BSE
🚨 INSURANCE SHOCK
One regulatory proposal wiped out billions in market value.
PB Fintech crashed ~36% in a single session.
But what exactly happened?
Thread 🧵👇
⚠️ THE TRIGGER
IRDAI proposed a major overhaul of insurance distribution economics.
Key areas:
• Commission structure
• Distribution expenses
• Expense of Management
• Mis-selling
• Digital “dark patterns”
• Commission disclosures
The market reacted immediately.
💥 PB FINTECH: THE BIGGEST HIT
PB Fintech — parent of Policybazaar — fell 35.98% on Sept. 24.
Approx. ₹31,400 Cr+ market value was wiped out in one session.
Turtlemint also fell ~20%.
Why?
The proposed changes could materially alter the economics of insurance distribution.
💰 WHY COMMISSIONS MATTER
Think of it simply:
Insurance premium
⬇️
Distributor earns commission
⬇️
Commission supports customer acquisition & distribution
If the allowable economics change significantly:
Revenue per policy ↓
That can pressure the business model of distributors.
🏦 IT WASN'T ONLY PB FINTECH
The selling spread across insurance + financial stocks.
Examples on Sept. 24:
🔻 Max Financial ~9.8%
🔻 HDFC Life ~6.1%
🔻 New India Assurance ~5.4%
🔻 ICICI Prudential Life ~4.2%
The BSE Insurance index fell ~2.2%.
🔍 WHAT IRDAI WANTS
The regulator says the proposed framework aims to:
• Reduce distribution costs
• Improve transparency
• Strengthen consumer protection
• Address “dark patterns”
• Improve suitability & prevent mis-selling
The consultation process is still ongoing — this is a proposal, not a final rule.
📊 THE BIG MARKET LESSON
A stock can fall sharply without a change in today's earnings.
Sometimes the market is pricing a change in:
Future unit economics → Future revenue → Future earnings
That's why regulatory changes matter.
#Insurance #IRDAI #PBFintech #Policybazaar #HDFCLife #SBI Life #StockMarket #IndianStockMarket #AAPSAWealth
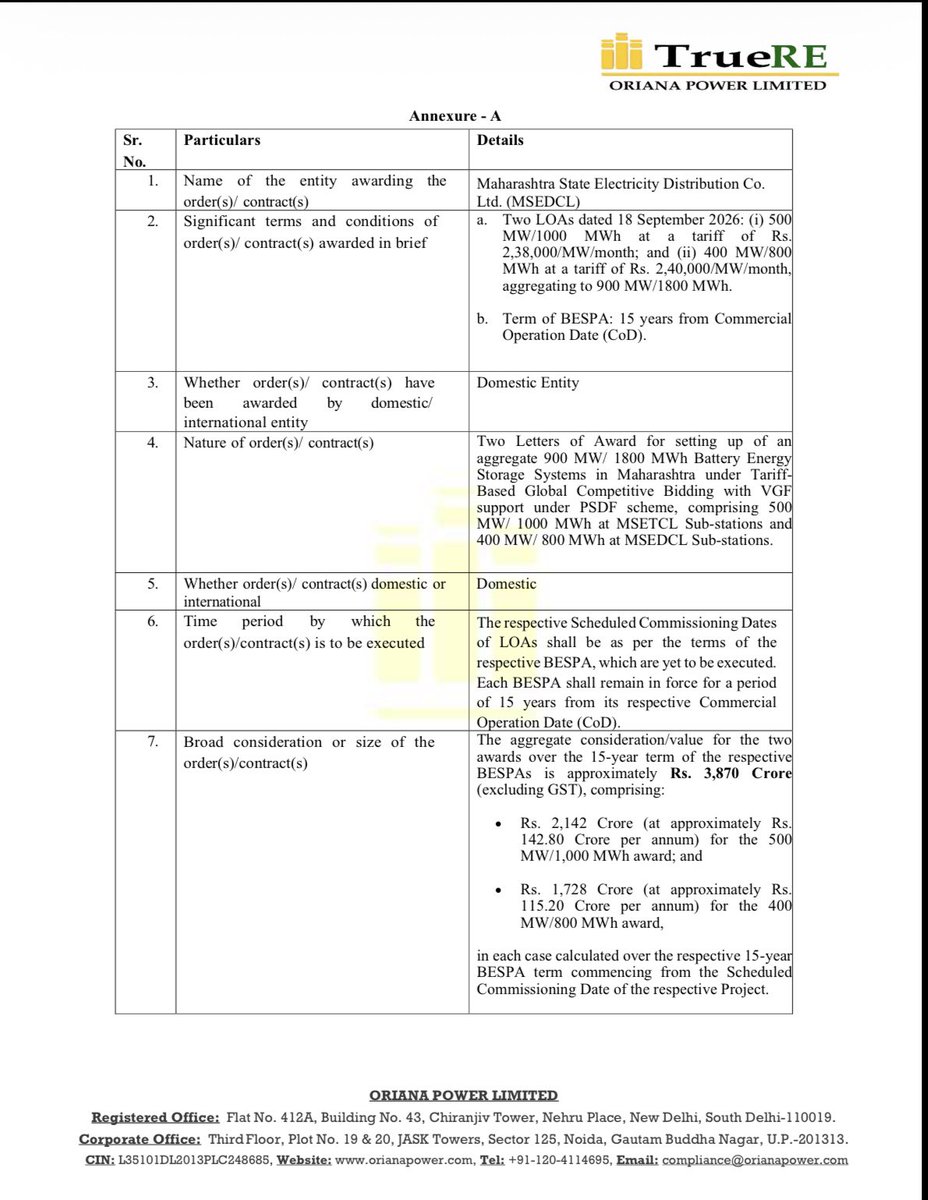
🚨#OrianaPower wins 3870 crore order 🔥🔥🚀(@ 257cr per annum for 15 years) for 1800 MWh BESS
Company market cap is only 2723 crore as of now! Stock price has fallen ₹613 to ₹266 as of now trading at only 10 PE
🧵 UPI Charges Are Changing — But Consumers Won’t Pay
UPI MDR is back
From Oct 15, 2026, eligible UPI payments to merchants above ₹2,000 will attract 0.4% MDR.
But this is a merchant-side charge — not a consumer fee.
💰 What changes?
• P2P UPI → FREE
• P2M ≤ ₹2,000 → FREE
• P2M > ₹2,000 → 0.4% MDR
• ₹75,000+ → MDR capped at ₹300
🏦 Special categories
Railways, telecom, insurance & fuel payments → ₹5 flat fee.
Capital-market payments such as stocks & mutual funds → 0.02%, capped at ₹300.
📱 Why does it matter?
UPI now handles enormous transaction volumes.
MDR could create a new revenue pool for banks, payment platforms & other ecosystem participants while supporting cybersecurity and infrastructure investment.
📊 Investor angle
The key question isn't just “Will UPI become expensive?”
It is:
Who captures the MDR economics?
Banks + payment apps + PSPs + merchant-acquiring ecosystem could all be affected.
#UPI #NPCI #DigitalPayments #Fintech #India #Investing #AAPSAWealth
🧵 ABAKKUS × BLACKBUCK 🚛 | ₹155.5 Cr Deal
Zinka Logistics Solutions.
Here’s 👇
👑 Abakkus Investment Managers, led by Sunil Singhania, acquired:
📦 27 lakh shares
💰 Deal value: ~₹155.5 Cr
💵 Price: ₹576.05/share
📊 Stake: ~1.48%
🏢 Company: Zinka Logistics Solutions Ltd
🚛 Brand: BlackBuck
📌 NSE: ZINKA
BlackBuck operates a digital platform connecting truck operators with services including payments, financing and logistics solutions.
🔴 Seller: Accel India IV (Mauritius) Ltd.
Accel's stake was around 7.17% as of June 2026.
The transaction therefore represents a meaningful change in ownership between a major early-stage investor and Abakkus.
🔎 Why is this interesting?
Abakkus is known for investing in businesses across market-cap segments.
A ~₹155 Cr transaction in BlackBuck puts the company firmly on the radar for investors tracking institutional capital flows.
⚠️ Important: A bulk/block transaction does NOT automatically mean the stock will rise.
👑 Smart Money
Abakkus → BlackBuck
₹155.5 Cr | 1.48% stake
#BlackBuck #ZINKA #Abakkus #SunilSinghania #IndianStocks #StockMarket #Investing #AAPSAWealth
🚨 NSE IPO IS FINALLY HERE! 🇮🇳
₹22,561 Cr IPO
📅 Opens: Sept 17
💰 Price band: ₹1,700–₹1,785
📦 Lot: 8 shares
🏦 100% OFS
But the bigger story is what NSE's listing means for India's capital markets. 🧵👇
🏛️ NSE IPO: THE NUMBERS
• Issue size: ~₹22,561 Cr
• Shares offered: 12.64 Cr
• Price band: ₹1,700–₹1,785
• Retail allocation: 35%
• QIB: 50%
• Minimum retail application: ₹14,280
One of India's biggest IPOs is about to hit the market. 🚀
💡 NSE isn't raising fresh money
This is a 100% Offer for Sale (OFS).
Existing shareholders are selling their shares.
➡️ IPO proceeds go to selling shareholders
➡️ NSE itself doesn't receive fresh capital
That's an important distinction for investors.
📊 Why is NSE important?
NSE dominates India's equity derivatives ecosystem and has a massive share of trading activity.
Its business benefits from:
📈 Rising market participation
📱 Demat & digital investing
⚡ Higher trading volumes
🏦 Institutional activity
🚀 Growth in India's capital markets
🔎 The interesting listed-company connection
NSE's existing shareholders include several listed financial institutions.
Watch the broader ecosystem:
#SBIN
#BANKBARODA
#LIC
#GICRE
#NIACL
#UIIC
#BSE
Some shareholders are selling shares through the OFS.
NSE also faces risks:
• Dependence on trading volumes
• Regulatory changes
• Technology/operational risks
• Competition
�� Derivatives concentration
• Market-cycle sensitivity
A great business can still have risks.
NSE IPO = more than just another IPO.
It is the potential public-market listing of the institution at the centre of India's capital-market ecosystem.
📅 Sept 17–21, 2026
💰 ₹1,700–₹1,785
📊 ~₹22,561 Cr
Theme mapping only — NOT Buy/Sell/Hold advice
#NSE #NSEIPO #IPO #IndianStockMarket #Investing #StockMarket #AAPSAWealth
🚨 NSE IPO IS FINALLY HERE! 🇮🇳
₹22,561 Cr IPO
📅 Opens: Sept 17
💰 Price band: ₹1,700–₹1,785
📦 Lot: 8 shares
🏦 100% OFS
But the bigger story is what NSE's listing means for India's capital markets. 🧵👇
🏛️ NSE IPO: THE NUMBERS
• Issue size: ~₹22,561 Cr
• Shares offered: 12.64 Cr
• Price band: ₹1,700–₹1,785
• Retail allocation: 35%
• QIB: 50%
• Minimum retail application: ₹14,280
One of India's biggest IPOs is about to hit the market. 🚀
💡 NSE isn't raising fresh money
This is a 100% Offer for Sale (OFS).
Existing shareholders are selling their shares.
➡️ IPO proceeds go to selling shareholders
➡️ NSE itself doesn't receive fresh capital
That's an important distinction for investors.
📊 Why is NSE important?
NSE dominates India's equity derivatives ecosystem and has a massive share of trading activity.
Its business benefits from:
📈 Rising market participation
📱 Demat & digital investing
⚡ Higher trading volumes
🏦 Institutional activity
🚀 Growth in India's capital markets
🔎 The interesting listed-company connection
NSE's existing shareholders include several listed financial institutions.
Watch the broader ecosystem:
#SBIN
#BANKBARODA
#LIC
#GICRE
#NIACL
#UIIC
#BSE
Some shareholders are selling shares through the OFS.
NSE also faces risks:
• Dependence on trading volumes
• Regulatory changes
• Technology/operational risks
• Competition
• Derivatives concentration
• Market-cycle sensitivity
A great business can still have risks.
NSE IPO = more than just another IPO.
It is the potential public-market listing of the institution at the centre of India's capital-market ecosystem.
📅 Sept 17–21, 2026
💰 ₹1,700–₹1,785
📊 ~₹22,561 Cr
Theme mapping only — NOT Buy/Sell/Hold advice
#NSE #NSEIPO #IPO #IndianStockMarket #Investing #StockMarket #AAPSAWealth
🚨 TATA SONS IPO?
RBI has rejected Tata Sons’ request to surrender its Core Investment Company registration.
That could put the unlisted Tata holding company back under pressure to list.
Could Tata Sons become India’s next mega IPO? 🧵👇
🏦 Why does RBI's decision matter?
Tata Sons remains under RBI's Upper-Layer NBFC framework.
Its standalone assets were around ₹1.75 lakh crore, well above the ₹1 lakh crore threshold.
This keeps the listing question alive.
💰 Why would a Tata Sons IPO be huge?
Tata Sons sits at the centre of the Tata Group.
Its portfolio includes:
💻 #TCS
🚗 #TATAMOTORS
⚡ #TATAPOWER
🏭 #TATASTEEL
🛒 #TATACONSUMER
🏨 #INDHOTEL
✈️ #AIRINDIA
A public listing could create significant valuation discovery.
📊 The interesting part
Tata Sons is currently unlisted.
A listing could provide the market with:
→ Transparent valuation
→ Greater disclosure
→ Price discovery
→ Potential shareholder liquidity
→ New capital-market visibility
But the structure and valuation would be closely watched.
⚠️ Important: No IPO announcement yet
RBI rejecting the CIC-registration surrender request does NOT mean:
❌ IPO date announced
❌ Price band announced
❌ Issue size announced
The immediate impact is regulatory.
The potential IPO is the next question, not a confirmed event.
One RBI decision has reopened a massive capital-market question:
Will Tata Sons eventually list?
If it happens, investors could finally get direct market-based valuation of the holding company sitting at the centre of the Tata Group.
#TataSons #TataGroup #RBI #IPO #TCS #TATAMOTORS #TATAPOWER #TATASTEEL #TATACONSUMER #INDHOTEL #IndianStockMarket #Investing
ESDS Software has doubled after listing but there are a LOT of red flags. The five biggest ones below:
The "$1.25 bn deal" is money ESDS must pay, not money it will earn -> its not being framed properly in communications
Almost all the cash is a refundable prepayment from one unnamed customer — ₹1,177 cr advance is 251% of revenue and ~98% of OCF
The GPU supplier is a tiny, short-attacked company that may not deliver
45% of group profit sits in a subsidiary the main auditor never audited, and the promoter personally owns 1% of it
The promoter describes the same deal differently depending on who's asking, and the delivery date has already slipped — "order win" on CNBC Awaaz, "the cost" on CNBC-TV18; seven years became five; GPUs called appreciating assets. Sydney go-live now "end of October" vs 16 September filed delivery.