WHY $SOFI COULD BE THE GROWTH STOCK OF 2027
SoFi has a legitimate opportunity to become one of the most compelling growth stocks to own in 2027 because market continues to value the company like a traditional consumer lender at same time its underlying business is evolving into something much more powerful since the biggest disconnect I see is that investors remain fixated on higher treasury yields, consumer credit and the possibility of additional rate hikes
Whats largely overlooking how quickly SoFi is expanding its financial ecosystem and improving the economics of its existing customer relationships since revenue grew 41% in Q2 to $1.21 billion, deposits increased another $5.3 billion sequentially to approximately $46 billion, and the company maintained a 5.98% net interest margin despite a challenging rate environment.
The bank charter is an important competitive advantage because those deposits provide funding at a substantially lower cost than traditional warehouse facilities with management estimating annualized savings of more than $700 million and higher interest rates can certainly pressure funding costs and loan demand, but I think the market is missing that SoFi now has a structural funding advantage that allows it to compete for customers, retain attractive loans and generate recurring interest income in ways that many fintech competitors simply cannot replicate.
That funding advantage becomes even more interesting when you look at how SoFi is managing its lending business because I think investors are misunderstanding the relationship between its Loan Platform Business and the loans management decides to retain on the balance sheet.
SoFi originated a record $14.8 billion in loans during Q2, but retained approximately 71% of its personal loan originations rather than distributing everything through third party partners, which has raised understandable concerns about balance sheet exposure and credit risk.
However, management has repeatedly emphasized that partner demand has exceeded the volume SoFi actually chose to fulfill, suggesting the decision to retain more loans reflects management's assessment of risk adjusted returns rather than an inability to find buyers.
The company can generate capital efficient fee revenue by distributing loans through its platform or retain higher yielding loans that produce recurring net interest income, and having that flexibility is something I think becomes increasingly valuable as the business scales.
The risks are real because SoFi still carries approximately $29.7 billion of loans held for sale at fair value, while higher long term yields could pressure loan valuations and platform fee margins, but the underlying credit performance remains encouraging, with personal loan annualized net charge offs improving to 2.62% from 3.03% sequentially.
If management can continue expanding originations while maintaining underwriting discipline and improving the balance between retained loans and partner funded lending, I think the market will gradually become more comfortable valuing SoFi as a diversified financial platform rather than simply another rate sensitive lender.
The bigger reason I remain so bullish heading into 2027, however, is that I think SoFi's member flywheel is still in the early stages of becoming a much more powerful earnings engine.
The company added approximately 1.1 million members and 2.2 million products during Q2, bringing its total membership to 15.8 million, while roughly half of new products were opened by existing customers.
That last figure is especially important because the long term opportunity is not simply acquiring more members, but increasing the number of financial products each customer uses without having to spend the same amount of money acquiring them again.
Then you have SoFiUSD, where the partnership with Mastercard around a card program processing more than $25 billion annually and the integration with Kraken's parent company create another potential growth opportunity in digital payments and settlement.
I don't expect stablecoins to materially move earnings immediately, but I do think the combination of subscription revenue, cross selling, deposits and new payment infrastructure could make SoFi's business considerably more diversified and profitable over the next several years.
Ultimately I think 2027 could become the year investors begin valuing SoFi on its earnings growth and expanding financial ecosystem rather than primarily on the direction of interest rates. Management is guiding for approximately $4.75 billion to $4.85 billion in revenue and $1.6 billion in adjusted EBITDA for 2026 while consensus expectations point toward roughly 40% earnings growth in 2027 which is particularly interesting for a company trading around 19 times next year's expected earnings.
That valuation becomes even more compelling if SoFi can continue expanding its member base, increase products per customer and demonstrate that incremental revenue is translating into substantially higher profitability.
The next major test comes with Q3 earnings on October 27 because management still needs to deliver a meaningful acceleration in second half profitability to meet its full year targets, and I'll be watching adjusted EBITDA, net interest margin, Loan Platform Business volumes, credit performance and SoFi Plus adoption particularly closely.
My thesis is that SoFi is transitioning from a rapidly growing digital lender into a much broader financial services business with multiple recurring revenue streams, stronger customer relationships and expanding operating leverage, and if management continues executing into 2027, I think the resulting earnings growth could drive a meaningful revaluation of the stock which is why SoFi remains one of my highest conviction positions in the Growth Portfolio and one of the names I'm most excited about heading into next year.
$HIMS
🚨 BREAKING: TWO PEOPLE FAMILIAR WITH THE WHITE HOUSE PEPTIDES PLAN SAY IT WILL ALLOW PHARMACIES TO COMPOUND SOME OF THE "MOST POPULAR PEPTIDES"
INCLUDING BPC-157 🔥🔥🔥
SOURCE: AP
JUST IN: FDA formally submits policy change to the White House that could expand access to popular peptides used for muscle recovery, pain relief, & looksmaxxing.
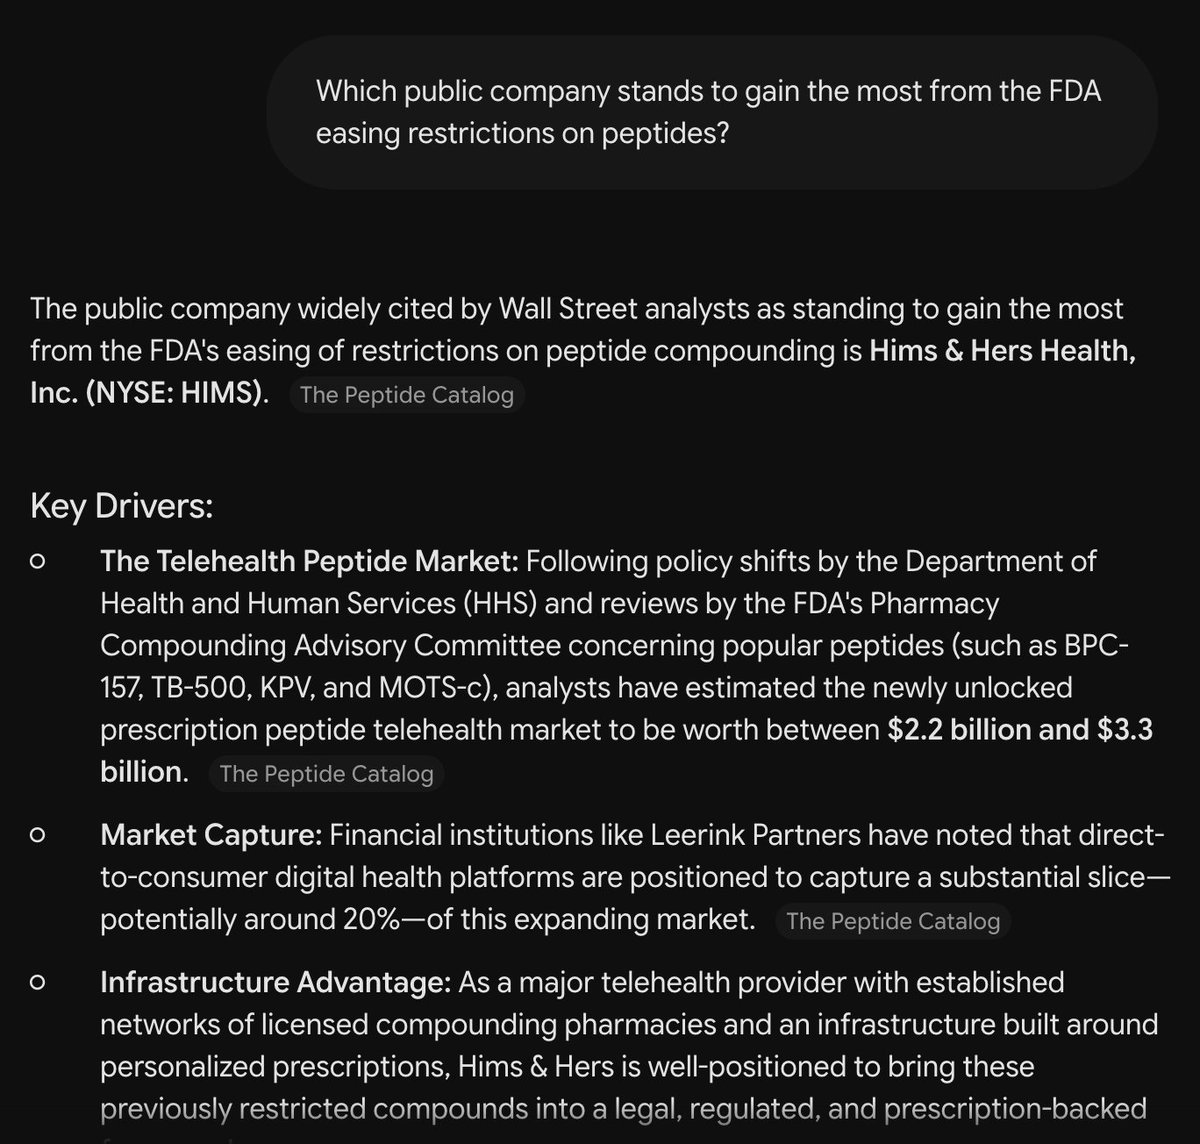
Which public company stands to gain the most from the FDA easing restrictions on peptides?
Claude: $HIMS
ChatGPT: $HIMS
Gemini: $HIMS
Buckle up buttercup
Hers has landed in Australia and expanded in the UK! 🇦🇺🇬🇧
When we launched @wearehers, it was because we knew women were long overdue for healthcare that was actually built for their lives. 8 years later, we’re reaching women all over the world. Not just with a single category or treatment, but with an entire health experience. One that’s simple. Personal. Designed with them at the center.
And we’re just scratching the surface of what we can do for women everywhere. Read more from Dr. Shepherd here: https://t.co/gEw8d0APlg
Today, Hers Hair arrives in the 🇬🇧 UK.
Hair thinning is a condition millions of women face and rarely feel comfortable naming out loud. Read more from Jessica Shepherd, MD, MBA, FACOG, on bringing medical innovation to women, from the UK to Australia 🇦🇺: https://t.co/dWG4FLklPG
$SOFI I'm very happy that Noto stays focused on the longterm goals and just keeps building the business. It's the right thing to do.
On the other hand, it's obvious there's a bully on the playground that very much deserves a punch in the nose.
You can ignore the bully but at some point it becomes more efficient to take the time to deal with them.
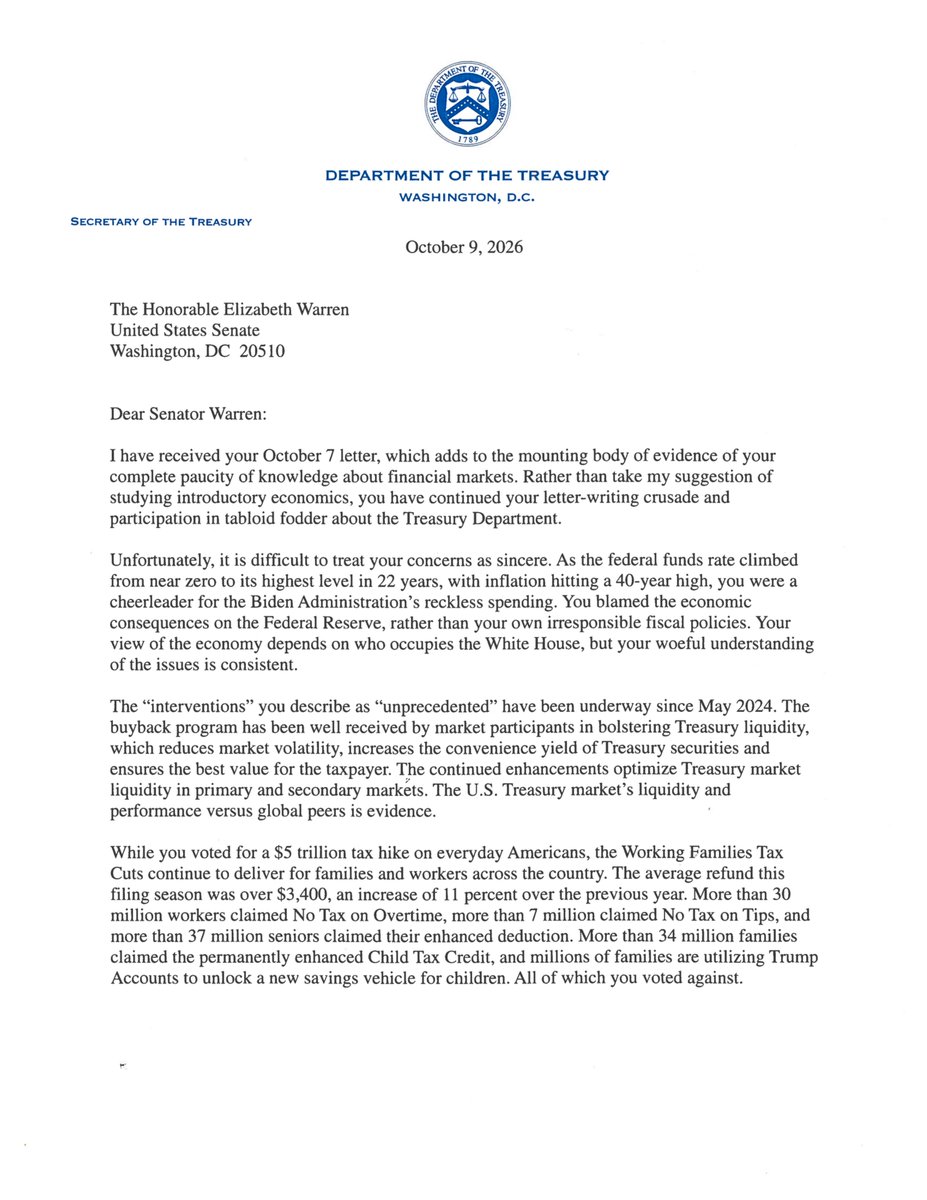
Treasury is expected to stop the 20Y bond auction from next month.
They are also planning to reduce each 30Y bond auction by $3,000,000,000.
With long-term yields at multi-decade highs, this is one way to bring them down.
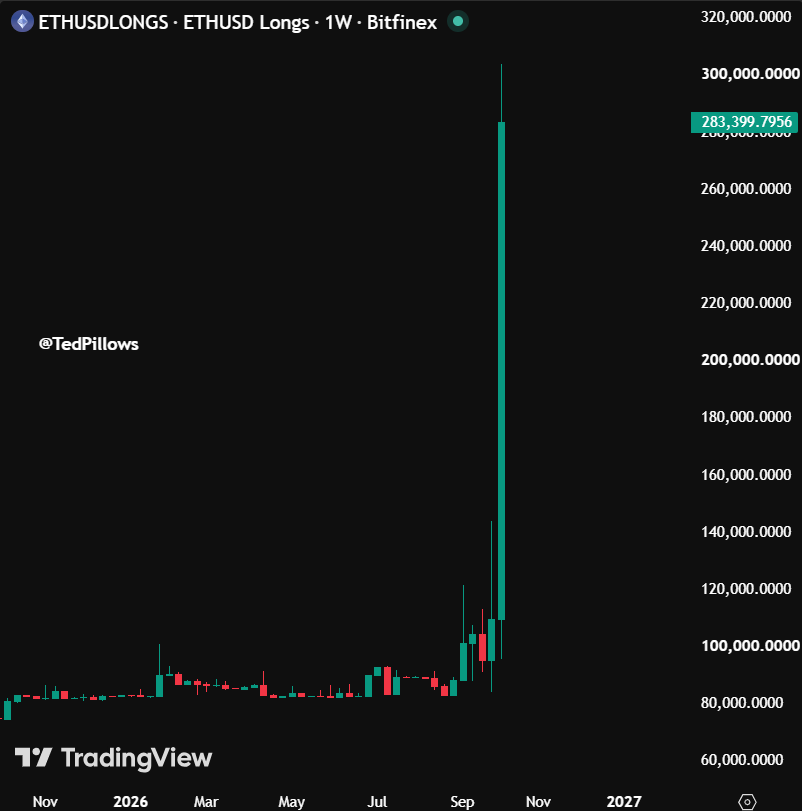
ETH longs are going parabolic ahead of Monday open.
My sources on Wall Street tell me they are expecting a HUGE week.
We could see ETH hit $3,000 by the end of October.