Certain media reports have alleged that GST on UPI Merchant Discount Rate (MDR) will burden small merchants and make digital payments costly. This is incorrect.
MDR applies only to P2M transactions above ₹2,000. Transactions up to ₹2,000 continue to have zero MDR and therefore zero GST impact. Government data indicates that transactions of up to ₹2,000 constitute more than 96% of UPI merchant transaction volume. As a result, the overwhelming majority of UPI payments will not attract MDR and hence no GST on MDR.
Further, GST paid on MDR by a merchant will be adjusted against the GST payable on the sale of goods, in the same manner that input taxes are set off against output tax liability. Consequently, merchants do not bear the cost of GST on the MDR amount paid by them.
Merchants with monthly UPI receipts of up to ₹1 lakh are not liable to pay MDR and therefore do not even have the issue of GST on MDR.
Hence, apprehensions that GST on MDR will impose an additional burden on merchants are misplaced. The overwhelming majority of UPI transactions and small merchants remain unaffected.
#UPI #DigitalPayments #DigitalIndia
🚨 Tax Audit Deadline Update: MTPA has sought more time for tax audit compliance for AY 2026-27.
📌 Proposed:
TAR → 31 Oct 2026
Audit ITR → 30 Nov 2026
But this is a request, not an approved extension. 👇
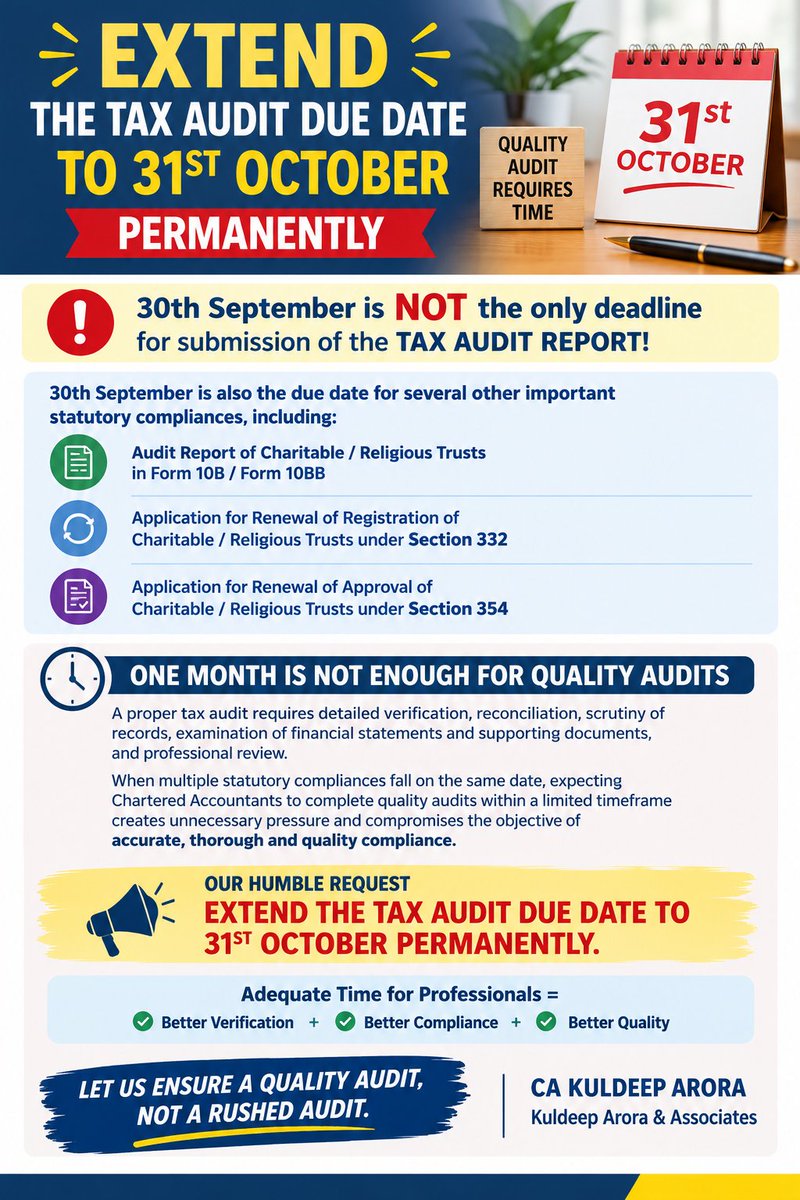
EXTEND THE TAX AUDIT DUE DATE TO 31ST OCTOBER PERMANENTLY
30th September is NOT the only deadline for submission of the TAX AUDIT REPORT!
30th September is also the due date for several other important statutory compliances, including:
🔹 Audit Report of Charitable/ Religious Trusts in Form 10B/Form 10BB
🔹 Application for Renewal of Registration of Charitable/Religious Trusts under Section 332
🔹 Application for Renewal of Approval of Charitable/Religious Trusts under Section 354
ONE MONTH IS NOT ENOUGH FOR QUALITY AUDITS
A proper tax audit requires detailed verification, reconciliation, scrutiny of records, examination of financial statements and supporting documents, and professional review.
When multiple statutory compliances fall on the same date, expecting Chartered Accountants to complete quality audits within a limited timeframe creates unnecessary pressure and compromises the objective of accurate, thorough and quality compliance.
Adequate Time for Professionals =
Better Verification + Better Compliance + Better Quality
LET US ENSURE A QUALITY AUDIT, NOT A RUSHED AUDIT.
CA KULDEEP ARORA
Kuldeep Arora & Associates
#TaxProfessionals
#TaxAudit
#ExtendDueDate
GSTN Advisory : On Extension of E-Way Bills Expired on 31st December, 2024
It is hereby informed that the technical challenges encountered in the e-way bill generation process have been resolved, and the portal is now functioning smoothly.
For more details: https://t.co/LfI7yR3Wqu
Dear All,
Its fulfilling to see when your efforts are appreciated and are contributing for the good. A non-profit organization, Vibrant India Economic Council (VIEC), [ https://t.co/WgqXFBnGCJ ]of which I am a part, achieved a milestone.
A Taxation System which has fetched approx. 60 Lakh Crore till date and Finances of the Country are dependent on it
Imagine..Tax Collection Deferred by 4 Days for Entire Country because a Form could not be Populated & but Taxpayer is asked Interest for delay of One Day..
Lawmaker makes a mistake, they issue notification, circular, press release.
Infosys makes mistakes, they issue their own advisory.
Professionals &taxpayer makes mistake, they are flossed with notices!
Why are we not allowed to rectify our mistake? @cbic_india@nsitharaman
In the interest of Trade and Industry Representation has been made by Institute of Chartered Accountants of India seeking exemption from levy of late fee on GSTR 9 and 9C filed on or before March 31, 2022. @theicai@cbic_india
In the interest of Trade and Industry Representation has been made by Institute of Chartered Accountants of India seeking exemption from levy of late fee on GSTR 9 and 9C filed on or before March 31, 2022. @theicai@cbic_india