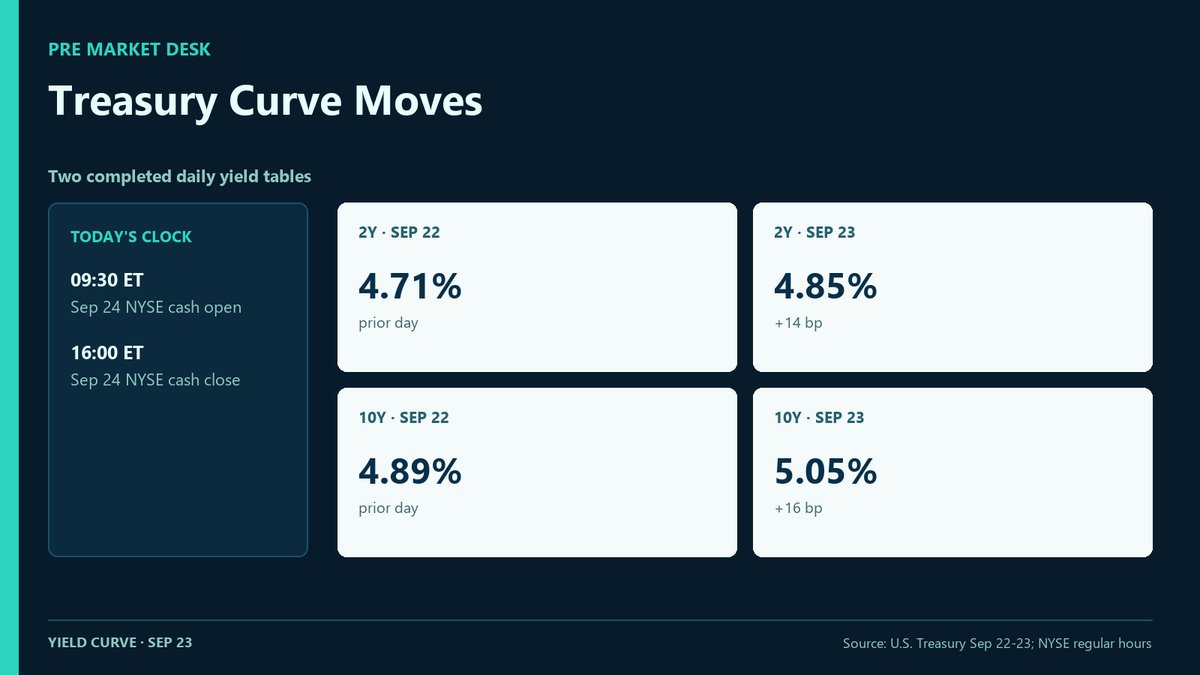
Wednesday's Treasury repricing reached both ends. The 2-year yield rose 14 bp to 4.85%; the 10-year rose 16 bp to 5.05%. Their gap widened only 2 bp. A 10-year quote alone misses how broad the rate move was. #Rates
As of 10:43 a.m. ET, the 10-year yield was 5.06%. $SPY was down 0.49% at 11:12. This keeps rates on the morning watchlist; two snapshots cannot explain the equity move. #MarketOpen
Lower oil was part of the backdrop, not a one-line explanation. Small caps led and the Dow lagged, so “stocks rose” misses the shape of the handoff. https://t.co/6dqTBKdX88
Oil's retreat supported growth, but the open had already split. AP put Brent at $98.46; around 9:55 a.m. ET, QQQ was +0.49% and IWM +0.97%, while DIA was -0.11%. #MarketOpen
Oil's retreat supported growth, but the open had already split. AP put Brent at $98.46; around 9:55 a.m. ET, QQQ was +0.49% and IWM +0.97%, while DIA was -0.11%. #MarketOpen
As of 6:08 a.m. ET, major U.S. stock-index futures were little changed. If oil and Treasury yields remain lower but market participation narrows again, that would point to concentrated leadership rather than a broad-based market reset.
https://t.co/bZtTJkgS3O
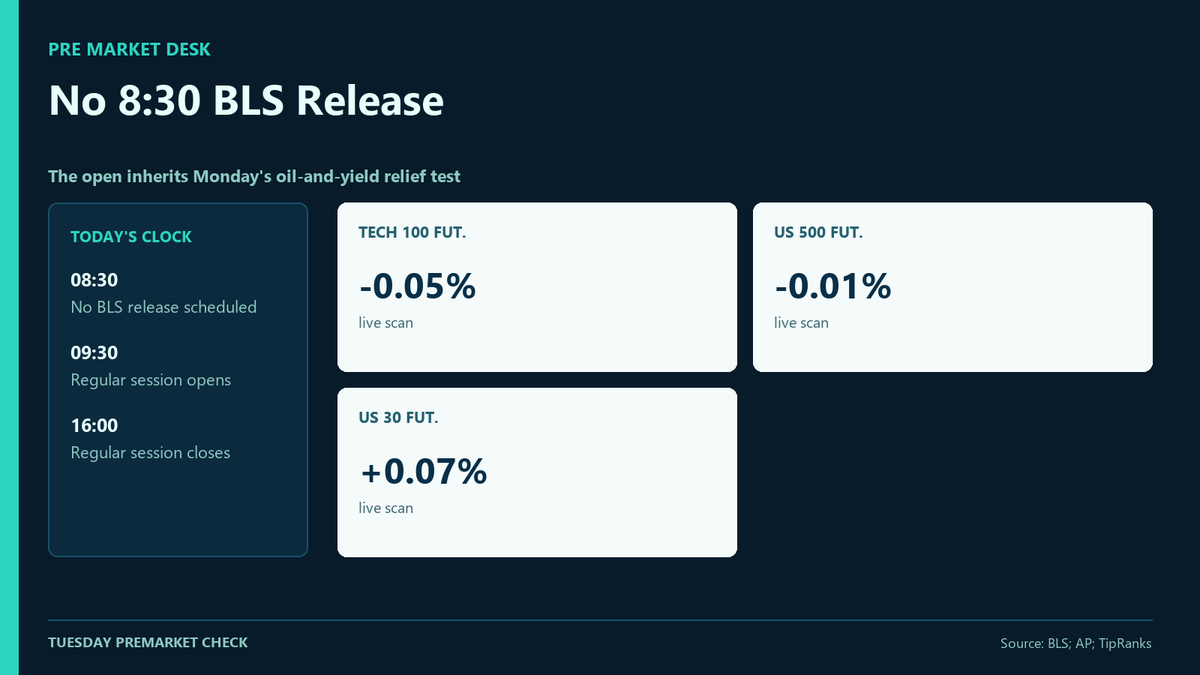
There is no scheduled 8:30 BLS release today. Monday's relief came with Brent down 3.4% to $100.34 and the 10-year yield near 4.95%. The cash open—not a calendar surprise—is the next test. #Premarket
There is no scheduled 8:30 BLS release today. Monday's relief came with Brent down 3.4% to $100.34 and the 10-year yield near 4.95%. The cash open—not a calendar surprise—is the next test. #Premarket
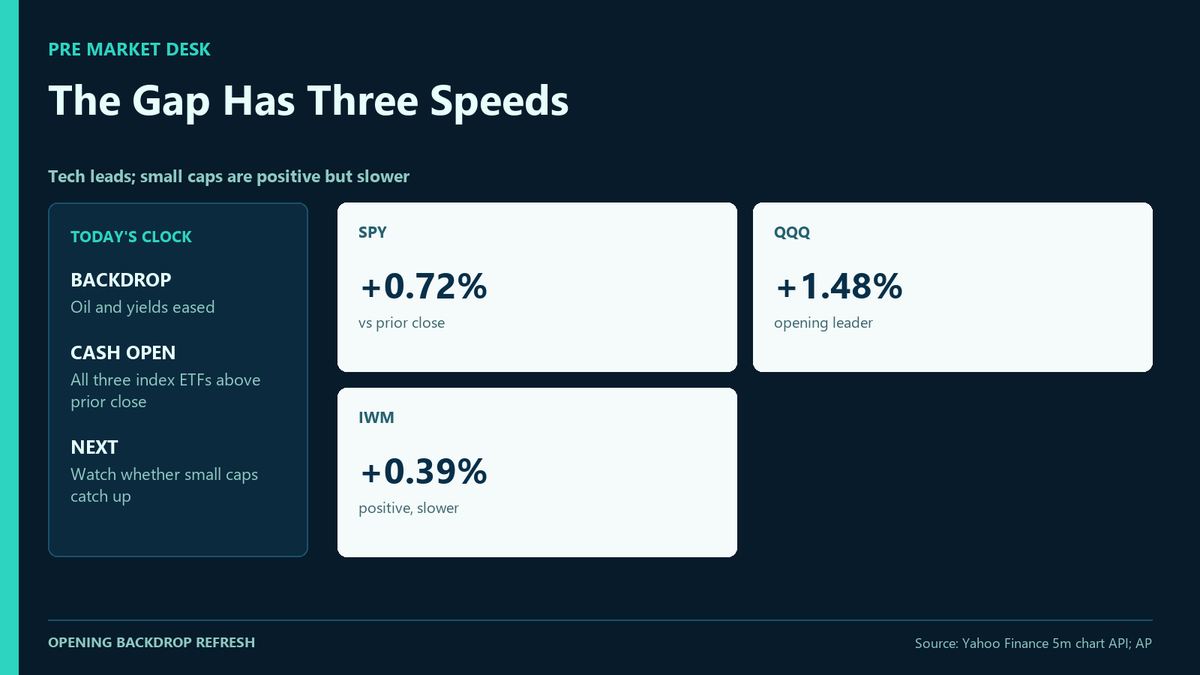
The opening gap is broad, but not even. At 9:46 ET, SPY was +0.72%, QQQ +1.48% and IWM +0.39% versus Friday. Lower oil and yields helped the backdrop; the useful question is whether small caps can close the speed gap without QQQ losing its lead.
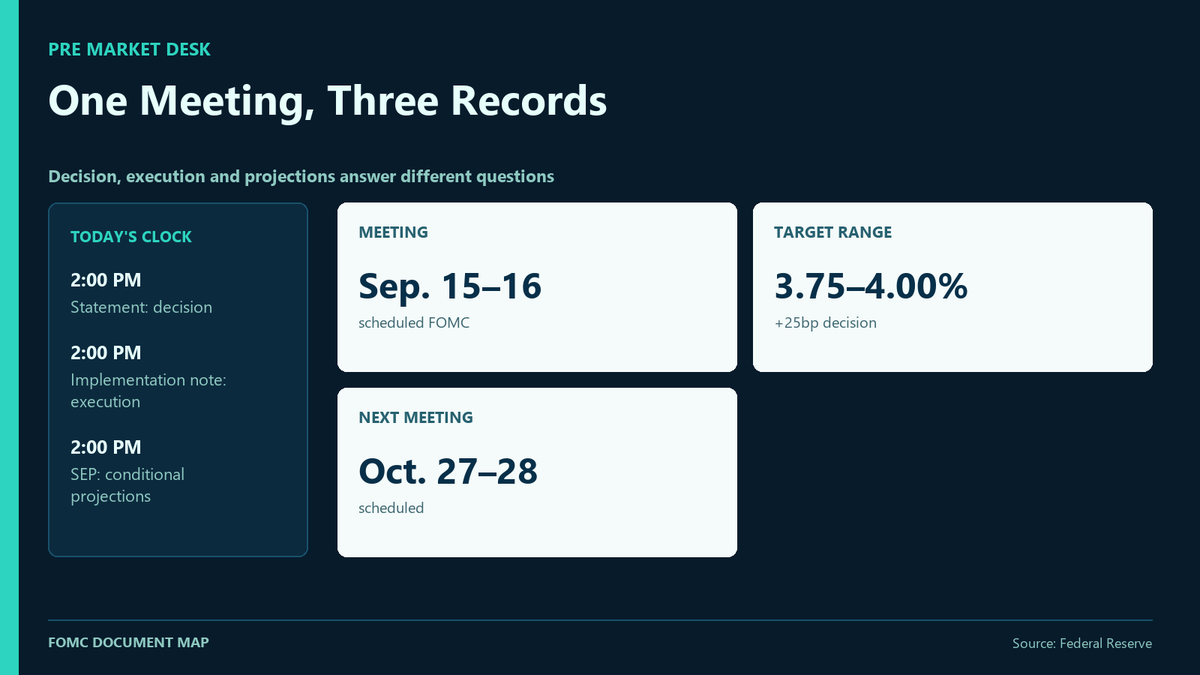
Treating them as one signal loses the distinction. Read the decision first, then the operating details, then the projection range. The SEP is built on each participant's view of appropriate policy—not a committee promise. https://t.co/hygHARUySr
One FOMC meeting produces several records, and they answer different questions. On September 16, the statement recorded the decision; the implementation note covered execution; the SEP showed participants' conditional projections.
One FOMC meeting produces several records, and they answer different questions. On September 16, the statement recorded the decision; the implementation note covered execution; the SEP showed participants' conditional projections.
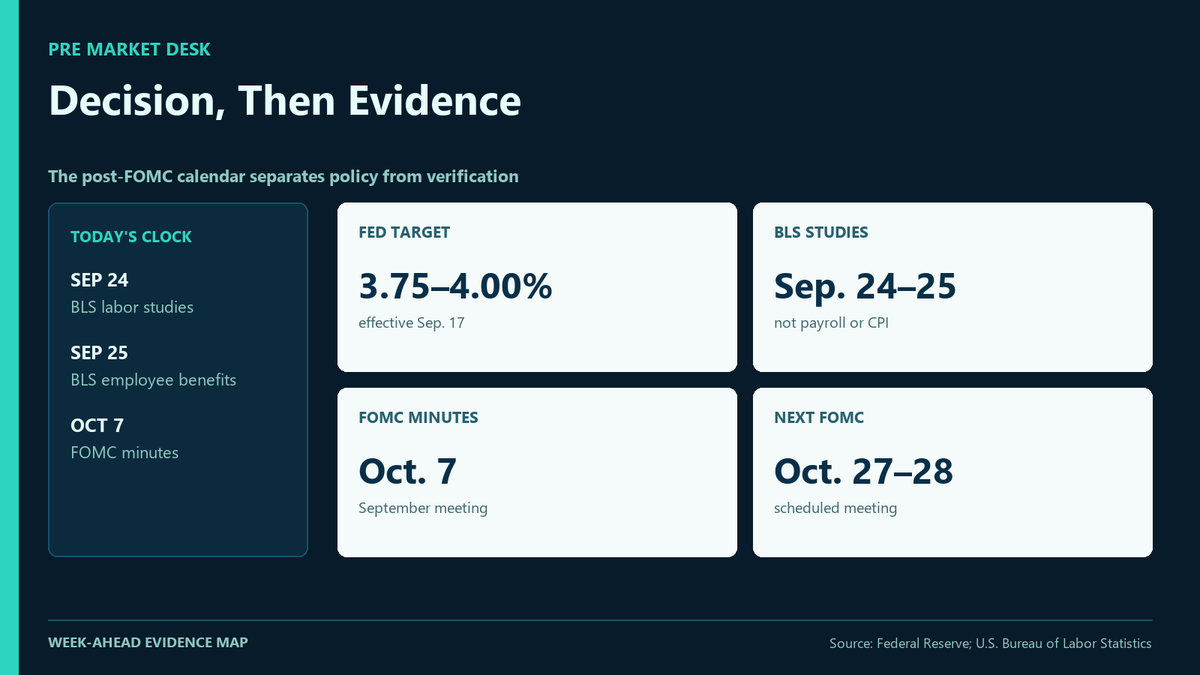
Last week's Fed move was the decision; the next calendar entries are the evidence. BLS lists labor studies on Sept. 24–25, while minutes from the September FOMC meeting arrive Oct. 7. Monday opens without a fresh payroll, CPI or policy decision.
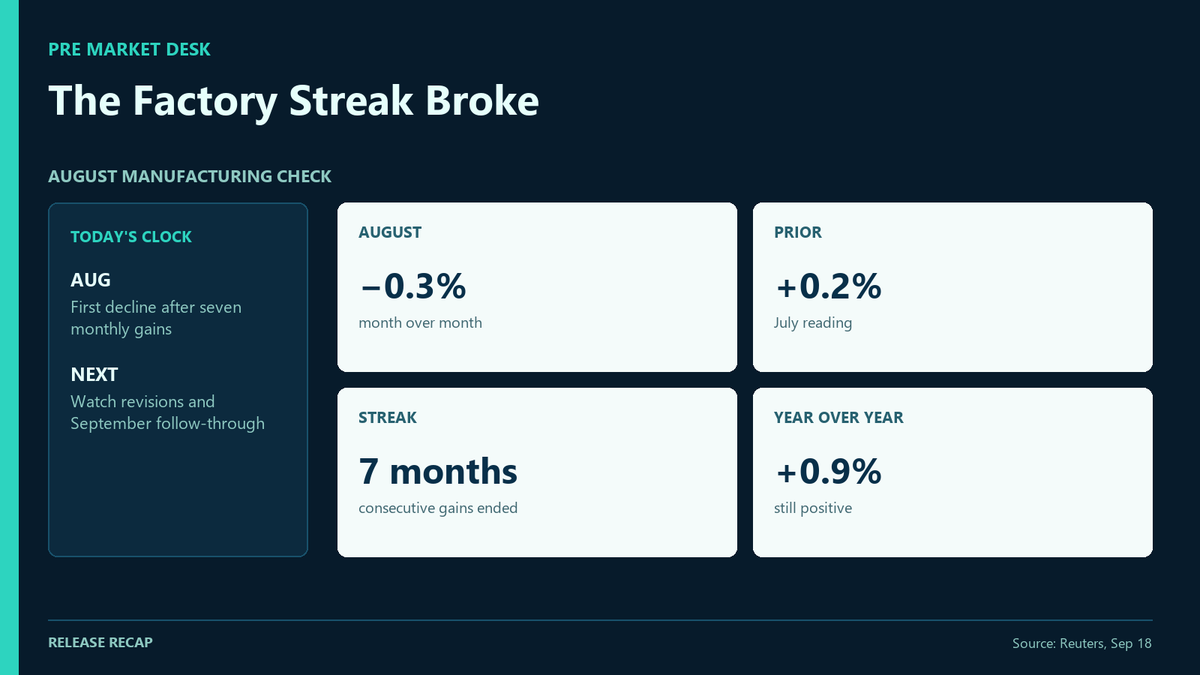
US manufacturing output fell 0.3% in August, ending a seven-month run of gains. July was +0.2%, and output was still +0.9% from a year earlier. One soft month is a watch item; the next release tells us whether it becomes a sequence.
August’s state jobs map was thin: payrolls rose significantly in only 4 states and were essentially unchanged in 46 plus D.C. The national jobless rate held at 4.1%. That argues for regional selectivity, not a broad hiring boom.
[2/2] I’m not treating them as one trade. NVDA needs semiconductor follow-through, TSLA needs the auction to hold its gap, and AMZN needs buyers beyond the first print. Prior close is the common reference, not an entry signal. https://t.co/YtNIgNsQDQ
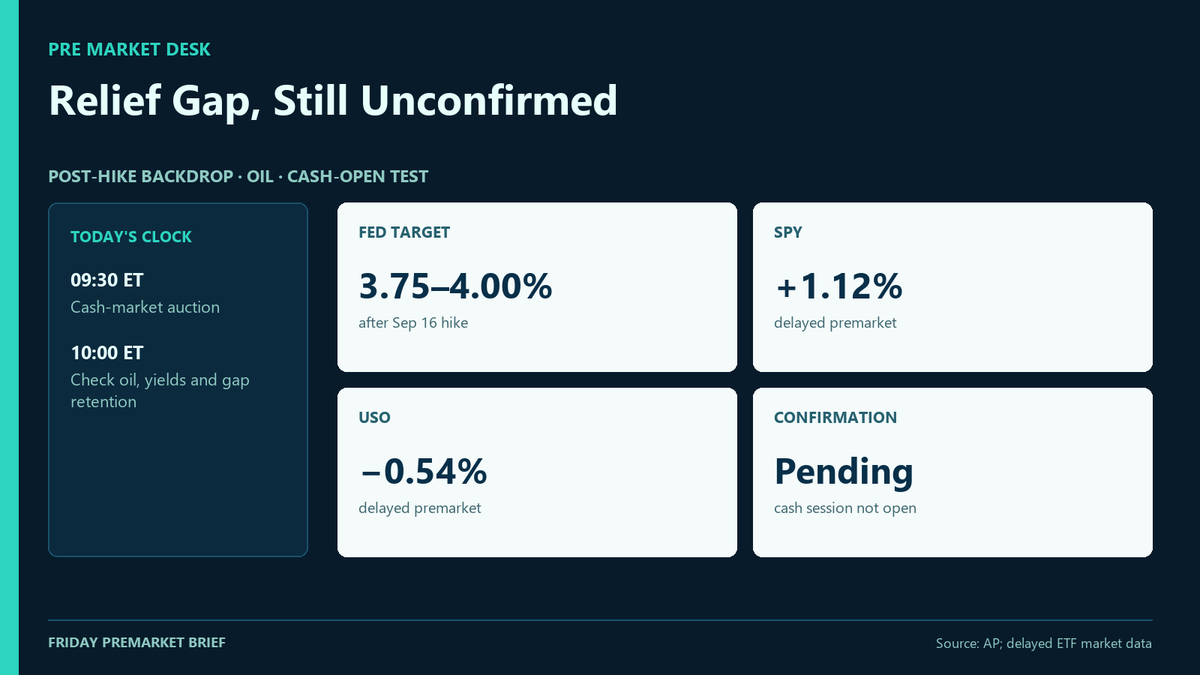
[1/2] Friday’s premarket tape is leaning into yesterday’s relief: $USO is down 0.54% while $SPY is up 1.12%. The setup is supportive, but it is still a gap before the cash auction.