We score every S&P 500 company on 4 factors from SEC filings, every day. Model portfolios, insider trades, 15 years walk-forward. Drawdowns published. Free.
What Quant500 actually does, in under a minute.
Every S&P 500 company scored on momentum, value, quality and growth. Twenty model portfolios with fifteen years of walk-forward. Insider filings the day they land. A simulator to build your own rule.
Free, no account, no ads — and the drawdowns are published too.
https://t.co/WCPBMHbkIq
Yesterday, 16 Sep 2026, the S&P 500 companies we score filed 463 documents with the SEC.
271 were 424B2 debt prospectuses.
118 were Form 4s. Alphabet and Estée Lauder filed 13 each.
24 were Form 144s.
21 were 8-Ks.
For the third day in a row, not a single set of accounts: no 10-Q, no 10-K. One 8-K carried item 2.02, the earnings announcement: Lennar.
Seven carried item 5.02, an executive coming or going: AES, AIG, Expand Energy, Expeditors, Insulet, Nike and Sandisk.
Seven leadership changes in a single day, on the day of a rate hike. Signal or noise?
https://t.co/H4ATfJWxEP
Yesterday the Fed raised rates for the first time in three years: a quarter point, unanimous, to 3.75%-4.00%. The S&P 500 fell 0.45% and the Dow 1.21%.
Here is how our strategies closed that day, walk-forward, dividends reinvested:
Momentum top 10 · +2.05%
Multi-factor top 10 · +1.24%
Momentum top 20 · +0.89%
Growth top 20 · +0.84%
Multi-factor top 20 · +0.32%
Quality top 20 · −0.52%
Equal-weight S&P 500 (RSP) · −0.78%
Value top 20 · −1.68%
Six of the seven finished ahead of the equal-weight index on a hike day. The one that didn't was value, the cheap stocks.
None of these rules reads interest rates. They're built from prices and SEC filings, and they rebalance on schedule whatever the Fed does.
One day is noise. But it's a useful day to see what each factor is actually exposed to.
Simulated results, not investment advice. Author's positions: https://t.co/zgqYCTbZuU
https://t.co/kG2zW7gL3Q
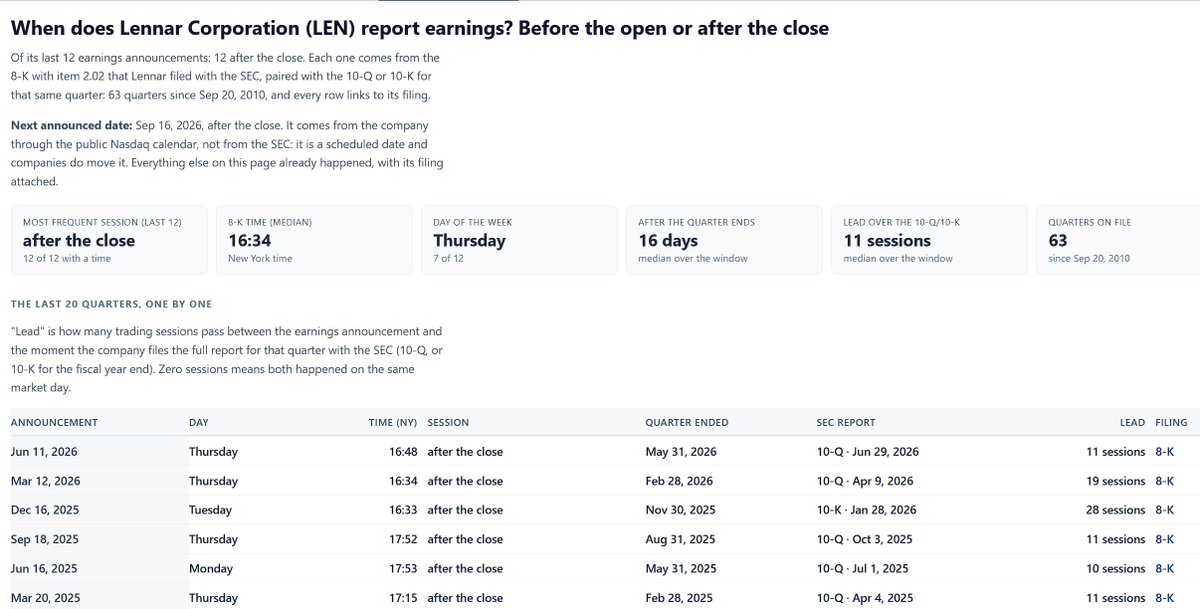
Lennar reported last night, a few hours after the Fed raised rates. From its own filing:
Net earnings · $284 million, $1.19 a share
New orders · down 9%, to 20,879 homes
Deliveries · down 3%, to 20,840 homes
Backlog · 16,857 homes, $6.3 billion
And here is what our model did with all of that: nothing. Yet.
Quality · 229th of 473, unchanged
Growth · 219th of 494, unchanged
A press release is an 8-K. The audited numbers are the 10-Q, and Lennar's median gap between the two is eleven trading sessions. Until then only the price-based factor can react, and the accounts wait for the filing.
Going in, it was still 3rd of 494 on value. Cheap before the report. We'll see whether the accounts say it deserved to be.
https://t.co/DM0Fp0T2CT
The release: https://t.co/hZ0YUhxi4j
Today the Fed decides at 2:00 p.m. New York time, and a few hours later Lennar reports: the only S&P 500 company reporting earnings this week, and a homebuilder, on the day rates are decided.
Where our model has it going in:
Value · 3rd of 494
Momentum · 482nd of 497
Multi-factor · 135th of 466
But the part almost nobody looks at is when the real numbers arrive. The press release is tonight. The audited 10-Q is another matter, and the four big homebuilders in the S&P 500 could not be more different:
PulteGroup · files its 10-Q the same session it announces
D.R. Horton · 2.5 trading sessions later
NVR · 10 sessions later
Lennar · 11 sessions later
Median over each company's last twelve quarters. Tonight's headline will move the stock. Lennar's quality and growth scores will not move until around the start of October.
Do you trade the headline tonight, or wait for the filing?
https://t.co/DM0Fp0T2CT
Yesterday, 15 Sep 2026, the S&P 500 companies we score filed 551 documents with the SEC.
386 were 424B2 debt prospectuses. That's 70% of everything.
65 were Form 4s — insiders.
46 were Form 144s.
22 were 8-Ks.
And for the second day in a row, not one set of accounts. No 10-Q, no 10-K, and not a single 8-K with item 2.02. The S&P 500 went into Fed day announcing nothing and borrowing a lot.
Six 8-Ks carried item 5.02, an executive coming or going: Flex, Otis, Quanta Services, RTX, The Trade Desk and Ventas.
Two days before a likely rate hike, companies filed 386 prospectuses to raise debt in a single day. Coincidence, or getting in before the door closes?
https://t.co/H4ATfJWxEP
Not every insider filing is a sale, and yesterday showed the difference perfectly.
Colgate-Palmolive · 8 Form 4s, 22 transactions
Every single one was code F: shares withheld to pay tax on stock that vested. Its CEO, CFO and six other executives sold nothing on the open market.
Dell · 7 Form 4s
Code S, real sales, on 11 September: about $134 million. Around $110 million came from Silver Lake funds, the firm that took Dell private in 2013. Another $21 million from its President of Global Sales.
Seagate · 6 Form 4s
Its CFO sold about $43 million, under a 10b5-1 plan set up in advance.
Same form, three completely different stories. Dell and Seagate are both in our multi-factor top 10 today.
A headline that says "insiders filed 21 Form 4s" tells you nothing. The transaction code tells you everything.
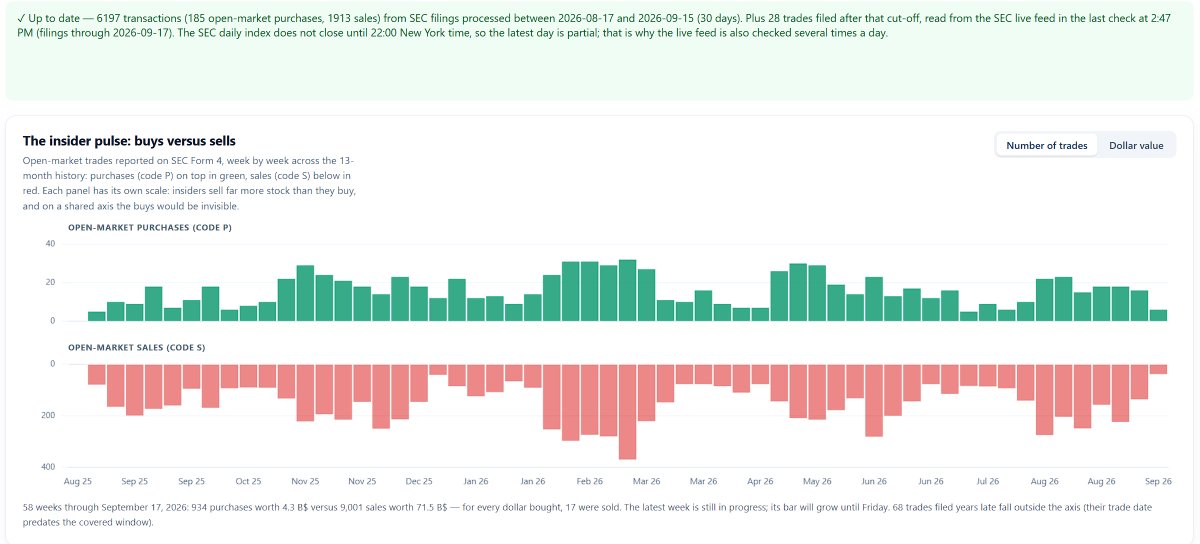
Every Form 4 from an S&P 500 company, with its code, the day it's filed:
https://t.co/H4ATfJWxEP
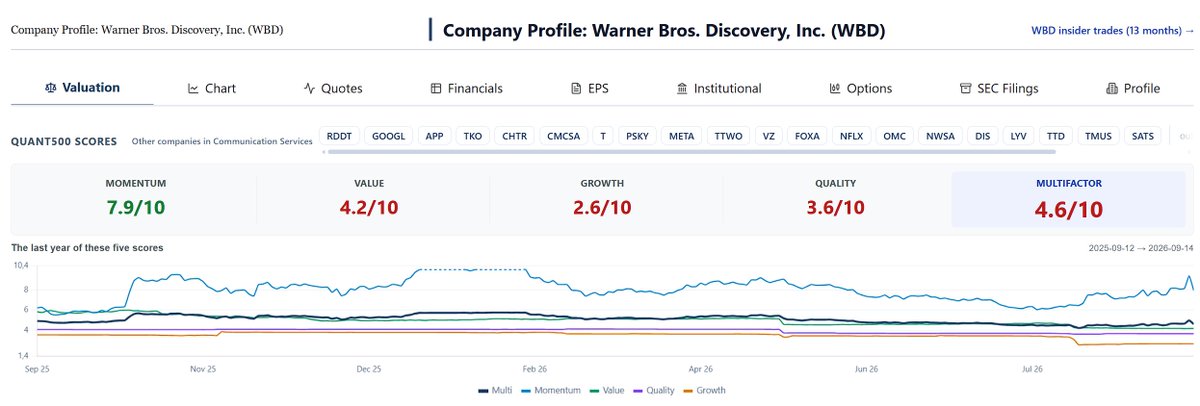
Warner Bros. Discovery fell 144 places in our multi-factor ranking yesterday, from 218th to 362nd of 466. Its stock closed up 0.21%.
Nothing happened to the company. Something happened to the calendar.
Momentum is the twelve-month return, skipping the most recent month, divided by volatility:
momentum = ( P[t−21] / P[t−252] − 1 ) / ( σ · √252 )
On Friday, P[t−252] was WBD's close on 10 Sep 2025: $12.54.
On Monday, it became the close on 11 Sep 2025: $16.17.
That was the day the stock jumped 28.9%. One session later, the starting point of the twelve months is 28.9% higher, and the return the model measures shrinks with it.
Momentum 9.38 → 7.92 · #9 → #19
Value, quality and growth scores: unchanged.
Every momentum score in the index does this. You only notice when a year-old spike crosses the edge of the window.
Should a model forget a day like that all at once, or let it fade out slowly?
https://t.co/cS1BugR0Oz
The most interesting line in yesterday's SEC filings was about data centers.
$NEE and $D, trying to get their $67 billion merger approved in Virginia, filed a new package on 14 Sep 2026. Straight from the exhibit:
$10 monthly residential bill credit for four years instead of two
Paid for by redirecting the share of credits that would otherwise go to data centers
$100 million more in low-income bill assistance, through 2038
1,000 new direct jobs in Virginia
Customers held harmless from merger costs
They still expect to close in the second half of 2027.
It says something about 2026 that the bargaining chip in a utility merger is who pays for the power data centers use.
Where our model has the two today:
Dominion · 213th of 466, value 155th of 494
NextEra · 242nd of 466, momentum 133rd of 497
Who should carry the cost of the grid that data centers need: the data centers, or everyone else?
Dominion: https://t.co/rvFmuJY41A
NextEra: https://t.co/lFN9rJgIhq
The filing: https://t.co/PSNoaB9R15
#DataCenters #Utilities #Energy #AI #SP500
Yesterday, 14 Sep 2026, the S&P 500 companies we score filed 602 documents with the SEC, more than on any day last week.
318 were 424B2 prospectuses.
140 were Form 4s — insiders buying and selling.
48 were Form 144s.
28 were Form 425s — merger communications.
25 were 8-Ks.
And not one set of accounts. No 10-Q, no 10-K. Of the 25 8-Ks, zero carried item 2.02: not a single S&P 500 company announced earnings, two days before the Fed.
So what was all that paperwork about? Deals. 14 of the 28 merger filings concerned Medtronic's exchange offer to split off MiniMed. Another 13 came from NextEra and Dominion, pushing their merger through Virginia.
Five 8-Ks carried item 5.02, an executive coming or going: Chipotle, Crown Castle, Dexcom, State Street and lululemon.
In a week with no earnings, 140 insider filings in a single day. Do you read those, or wait for the headlines?
https://t.co/H4ATfJWxEP
Worth noting what a pure momentum ranking makes of that. Our S&P 500 momentum top 10, built from nothing but price, doesn't hold a single energy stock today. The top 20 it bought in August holds one: Valero.
Our multi-factor portfolio, which also weighs value, quality and growth, holds five.
Momentum needs months of rising prices before a stock qualifies, so a new trend reaches it late. This is what that lag looks like in real time.
https://t.co/xLvM6kGEYD
$14.2 billion out in three weeks. For perspective on what staying in looked like:
Our multi-factor top 20, walk-forward since 31 December 1998, dividends reinvested, straight through the dot-com bust, 2008, 2020 and 2022:
11.37% a year
$100 became $1,962
The equal-weight S&P 500 turned it into $1,528
Every rebalance is on the page, the bad years included.
https://t.co/8vUhHXAWdz
Worth watching Wednesday, then. Lennar, the only S&P 500 company reporting earnings this week, is headquartered in Miami, and it reports a few hours after the Fed decides.
Our model has it 2nd of 494 on value and 481st of 497 on momentum. Priced as if the market already believes this chart.
https://t.co/DM0Fp0T2CT
Energy is the part of the market our multi-factor portfolio never set out to own, and holds anyway. Of the 20 stocks it bought on 21 August, five are energy: Valero, Marathon Petroleum, Phillips 66, Expand Energy and EQT. Three of them are refiners, the part of the business that lives off diesel margins.
Nobody built that as a hedge. The score ranks momentum, value, quality and growth together, and this is where it landed.
Walk-forward since 1998, dividends reinvested: 11.37% a year, against 10.37% for the equal-weight S&P 500.
https://t.co/8vUhHXAWdz
Wednesday puts both of those in the same evening. The Fed decides, and a few hours later Lennar reports, the only S&P 500 company reporting all week.
Where our model has it going in:
Value · 2nd of 494
Momentum · 481st of 497
Almost the cheapest stock in the index, priced like nobody wants it. And the accounts won't arrive that night: Lennar's median gap to its 10-Q is eleven trading sessions.
https://t.co/DM0Fp0T2CT
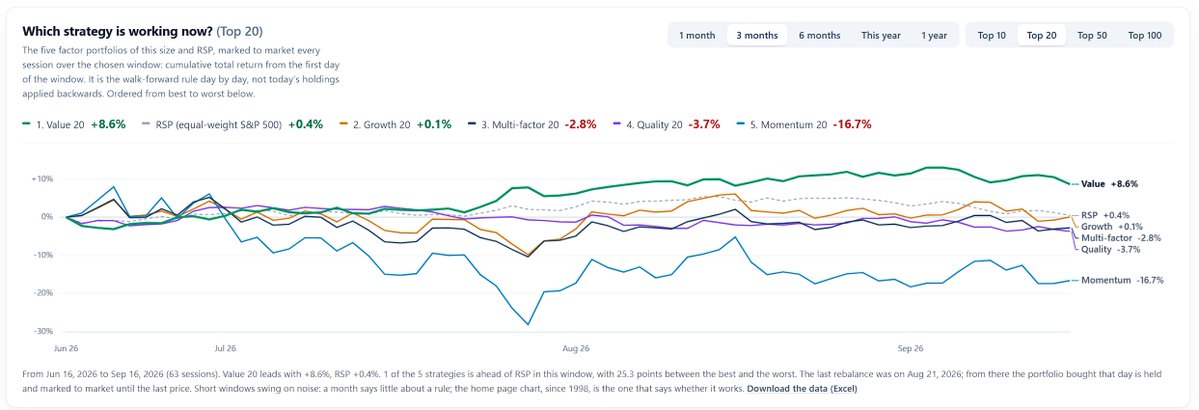
Tech futures are falling this morning, crude is back above $100, and a Fed hike is priced as likely for Wednesday. So here is what our five 20-stock portfolios are actually holding into it. Not today's ranking: the stocks bought on 21 August and held since.
Momentum · 13 of 20 technology, 1 energy
Multi-factor · 10 technology, 5 energy
Quality · 10 technology, 1 energy
Growth · 9 technology, 4 energy
Value · 5 healthcare, 3 technology, 1 energy
A morning like this one does not hit the five the same way. Momentum carries the heaviest technology bet and a single energy stock. Multi-factor carries almost the same technology bet, but a quarter of it is energy: refiners Valero, Marathon Petroleum and Phillips 66, and gas producers Expand Energy and EQT.
Nobody chose that split. Every rule ranks the whole index with no sector limit, and this is where each one landed.
None of them reads oil, rates or headlines. They are built from prices and SEC filings, and they rebalance on schedule whatever the Fed does on Wednesday.
That is the uncomfortable part of a rules-based portfolio: on a day like today, you don't get to change your mind. Would you?
https://t.co/8vUhHXAWdz
Friday's headline was "Larry Ellison to sell $7.5 billion of Oracle". The filing says something more useful, so here it is.
It comes from Oracle's 10-Q, filed 11 September, Part II, Item 5:
Plan adopted · 22 June 2026
Scheduled to end · 24 October 2026
Size · up to 50 million shares
The decision is 81 days old. It became public the day the quarterly report landed, not the day it was signed. That isn't a scandal, it's the rule: Item 408 of Regulation S-K requires these plans to be disclosed in the next quarterly filing, which is exactly why they surface weeks late.
Three things worth knowing about any 10b5-1 headline:
It's a plan, not a sale.
The dollar figure is one day's price times the maximum.
The real sales arrive later, one Form 4 at a time.
We publish every Form 4 filed by an S&P 500 company, the day it arrives. When Ellison's first one lands, it'll be on the list.
https://t.co/H4ATfJWxEP
The emptiest earnings week of the year lands on the week of the Fed.
Between Monday 14 and Sunday 20 September, exactly one S&P 500 company reports: Lennar, on Wednesday 16, after the close. A homebuilder, reporting a few hours after the rate decision that matters most to the people who buy its houses.
Where our model has it going in:
Value · 2nd of 493
Momentum · 480th of 496
Multi-factor · 134th of 465
Nearly the cheapest stock in the index, and one of the most disliked by its own price.
And one thing Wednesday's headline won't tell you: Lennar's median gap between announcing and filing its 10-Q is eleven trading sessions. The numbers that actually move a score arrive around the start of October, not on the night of the Fed.
So which is it: is 2nd of 493 on value the market already pricing the hike, or the trap before it?
https://t.co/DM0Fp0T2CT
Last week our best of the five strategies was momentum, and the interesting part is why.
Four trading sessions, 4 → 11 Sep 2026 (Monday was Labor Day):
Momentum top 20 · +1.96%
Multi-factor top 20 · +0.88%
Growth top 20 · +0.44%
Value top 20 · −1.55%
Quality top 20 · −2.07%
Equal-weight S&P 500 · −1.87%
Momentum beat the benchmark by 3.83 points in four sessions, and it did it while the market fell.
Here is the whole portfolio. It was bought on 21 August and has not been touched since, 14 sessions ago:
$LITE $MU $SNDK blockstack:native $WDC $CIEN $AMAT $INTC $LRCX $DELL $VLO $TER $AMD $COHR $FIX $WBD $CAT $BK $JBHT $STT
Eleven of the twenty rose. What carried it:
$CIEN +8.89%
$COHR +8.34%
$DELL +8.23%
$AMD +8.07%
$INTC +7.45%
And now the part I did not expect. On 9 September I posted a warning that this ranking had put five memory and storage names in its top ten with no sector rule at all, and that the concentration was a risk. Last week memory was the worst thing in the portfolio:
$SNDK −6.13%
$WDC −4.34%
$MU −4.07%
blockstack:native −2.25%
The portfolio still won, because optical networking and semis carried the four that dragged. The warning was right about the risk and the week paid anyway.
Every one of these numbers comes from the same file the site publishes, and the portfolio is the one actually bought on 21 August, not today's ranking. Full walk-forward, 332 rebalances since 1998, 9.93% a year:
https://t.co/sKr4jJwxeA
One week is noise and I know it. So the honest question: would you rather hold the strategy that won this week, or the one that lost 2.07% while its accounts were the strongest in the index?
#SP500 #Momentum #FactorInvesting #Quant #AlgorithmicTrading
Yesterday, 11 Sep 2026, the S&P 500 companies we score filed 455 documents with the SEC.
264 were 424B2 prospectuses.
81 were Form 4s — insiders buying and selling.
31 were Form 144s.
30 were free writing prospectuses.
10 were 8-Ks, plus one amendment.
One was accounts: Oracle's 10-Q.
The cleanest illustration of what we do arrived this week without us arranging it. Oracle and Adobe both announced earnings on 10 September. Oracle filed its 10-Q the next day, and its growth score moved sixty-three places. Adobe has not filed, and its scores yesterday were:
Quality · #16 → #16
Growth · #253 → #253
Multi-factor · #201 → #201
Identical. Adobe's median wait between announcing and filing is nine trading sessions, so that 10-Q is due around 23 September. Until then there is nothing new to read.
And the number that never gets discussed: 264 of those 455 documents — 58% of everything the S&P 500 filed yesterday — were debt prospectuses. On the day CPI came in at 3.4% and the odds of a hike went to 79%, corporate America spent its paperwork raising money.
Does anyone actually read those 264, or is the bond market the only part of this that nobody live-tweets?
https://t.co/SKwZPoXfUr