“It feels to me like the crowd that tells us this isn't about fiscal stress is the same crowd that was rearranging the deckchairs on the Titanic.”
I am old, but not that old. Meanwhile, it’s fiscal stress, Robin? Explain Australia.
https://t.co/FM5g4AoGYt
Why are $AMZN, $AAPL, and $MSFT selling off? The June Russell rebalance is slashing their Growth weights and is making Amazon the new King of the Value index. Billions in forced fund flows are moving markets.
@profplum99, @fleckcap, @adamtaggart
Q: What do Berkshire Hathaway ($BRK.B), Palantir ($PLTR), and a SpaceX IPO have in common?
A: Their CEOs understand how passive fund flows affect stock prices.
Educate yourself about how flow-driven pricing has replaced valuation-driven pricing.
https://t.co/zlv1J3kGDm
SpaceX is engineering a $50B+ automatic buy wall before the stock even trades.
Here’s why this is so much bigger than people realize.
Normally, a company IPOs, waits 6-12 months of “seasoning,” then maybe gets considered for S&P 500 or Nasdaq 100 inclusion at a quarterly rebalance. That waiting period exists so the stock can establish a trading history, prove liquidity, and show it won’t collapse 30 days in.
SpaceX wants to skip all of that. And Nasdaq is literally rewriting its rules to accommodate them.
Nasdaq just proposed a “Fast Entry” rule that lets any new listing with a market cap in the top 40 of current index constituents join after just 15 trading days. The old minimum was three months. SpaceX’s expected IPO valuation of $1-1.5 trillion would make it a top-10 constituent on day one.
The math on why this matters: roughly $16 trillion in assets directly track or benchmark against the S&P 500 and Nasdaq 100. Index funds like SPY, VOO, and IVV alone manage over $2 trillion combined. When a stock enters one of these indexes, every passive fund and ETF tracking it has to buy shares in proportion to the company’s weight. For a company valued at $1 trillion+, that forced buying could easily exceed $50 billion in the weeks following inclusion.
SpaceX is pre-negotiating an artificial demand floor before a single retail investor places an order.
Think about what this tells you about how Musk and SpaceX’s advisers view the IPO risk. They’re targeting a valuation of 60-70x sales on $22 billion in expected 2026 revenue. At that multiple, the stock needs constant buying pressure to hold. Index inclusion creates that pressure mechanically, through fund inflows that happen regardless of whether any human analyst thinks the price makes sense.
Tesla rallied 60% between its S&P 500 inclusion announcement and actual addition in December 2020. SpaceX watched that playbook, and now they’re trying to compress the timeline from months to days.
Meanwhile, index providers are now competing to attract the biggest IPOs by weakening the very rules designed to protect index integrity. Nasdaq is proposing Fast Entry. S&P will face pressure to match or lose the listing. The indexes are turning into customer acquisition tools for trillion-dollar debuts.
And every passive investor in a 401(k) will automatically become a SpaceX shareholder at whatever price the market sets in those first 15 trading days, whether they want to be or not.
The passive fund flows that relentlessly propel Mag 7 stock prices also spillover into other assets. Understanding these connections is critical when assessing portfolio risk.
These buybacks generate additional share demand in an already price inelastic market. $AAPL alone is likely to see a >$500B market cap increase thanks to its $100B of buybacks. The Inelastic Market Hypothesis details this phenomenon and understanding it is now essential.
@Rick_Ferri @derektinnin @dvandenbord@profplum99@larryswedroe I don’t think you understand how the market structure has changed in the past ten or so years. The shift to passive investing and the distortion it is unleashing may end up being the biggest financial story in our generation. That’s not hyperbole.
@dvandenbord @derektinnin @Rick_Ferri@profplum99@larryswedroe Not necessarily “warn them” but educate them about what they own when they buy into an index. As you know, 7 mega cap technology stocks account for 1/3 of the S&P 500 market cap. That fact alone surprises many people.
@derektinnin @Rick_Ferri@dvandenbord@profplum99@larryswedroe I think of “closet indexers” as the folks who would be considered active investors since they hold a large sample of the S&P 500 but make slight adjustments in an attempt to add alpha.
@derektinnin @Rick_Ferri@dvandenbord@profplum99@larryswedroe Yes, and, as this phenomenon is becoming more broadly understood, investors are looking for ways to exploit it (as Mike recently mentioned). Closet indexers are one group and their trades aren’t identified as an index fund trade.
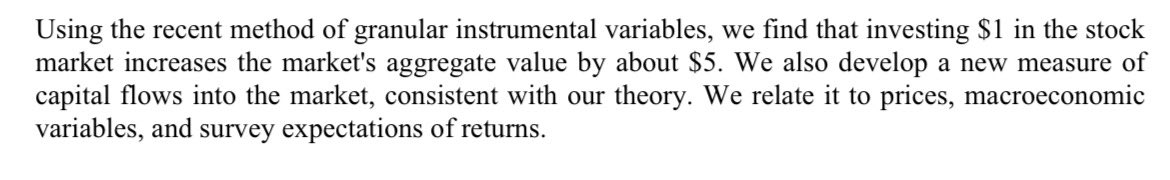
@Rick_Ferri@profplum99@larryswedroe If you buy $1 of AAPL it will increase the aggregate value of the market by more than if you buy $1 of JNJ. And, in both cases, investing $1 adds more than $1 in market cap. So, the analogy of a uniform investment “pool” is misleadingly oversimplified.
@Rick_Ferri@myersbradley@profplum99@larryswedroe Passive is receiving roughly $1.5B per day of net inflows. The “short-run inelasticity” has seemingly become permanent. The risk that @profplum99 and others highlight is that these flows are dynamic and now significantly affect market prices.
@Rick_Ferri@myersbradley@profplum99@larryswedroe Not true. The individual securities do not have the same elasticity. And, as those buy/sell transactions get larger, those transactions are EXACTLY what causes passive to distort markets. Here is a white paper supporting this discussion.
https://t.co/2Hsbwufffz
@Rick_Ferri@myersbradley@profplum99@larryswedroe Informed investors are aware of the market impacts from Passive Investing and are either managing those risks themselves or are paying an advisor to do so on their behalf.
@Rick_Ferri@profplum99@larryswedroe The point here is that your fair share of the long-term global market return is inextricably linked to passive fund flows. @profplum99 shows how this is mechanically the case and today is pointing out that people are waking up to this reality.
@Rick_Ferri@profplum99@larryswedroe Rick - Are you saying you’re using a hedge to offset the impacts from largest holdings in VTI and that is why your performance isn’t affected?
What I think is really going on here, and many of you already know, is that Powell hasn’t kept rates high just to fight inflation or because he’s late, as Trump likes to say. He’s holding them high to maximize strategic leverage. By keeping the dollar scarce and real yields elevated, Powell is applying immense pressure on the global system, particularly on BRICS-aligned nations, dollar indebted economies, and those flirting with de-dollarization. This isn’t about monetary policy in the conventional sense; it’s about geopolitical positioning. The longer the Fed starves the world of easy dollars, the more the global economy becomes strained and fractured until, at the right moment, a pivot triggers a rush back into USD assets, setting off a powerful dollar snapback.
And that’s the contradiction Trump hasn’t addressed. If he truly wanted rate cuts, he wouldn’t be layering on tariffs, trade friction, and policy choices that fuel cost pressures and complicate the disinflation narrative. His actions are at the very least short term inflationary at the margin and give Powell political cover to stay higher for longer. That might look like misalignment, but in reality, it may be two sides of the same coin. Trump wants to appear like the rate cut hero, while Powell engineers the global squeeze that sets the stage for a reassertion of dollar dominance. When that snapback hits, when the Fed finally cuts, it won’t crash the dollar. It will accelerate capital flight from weaker currencies, break fragile sovereigns, and lock global capital back into U.S.-controlled rails. That’s the play. Everything else is noise.