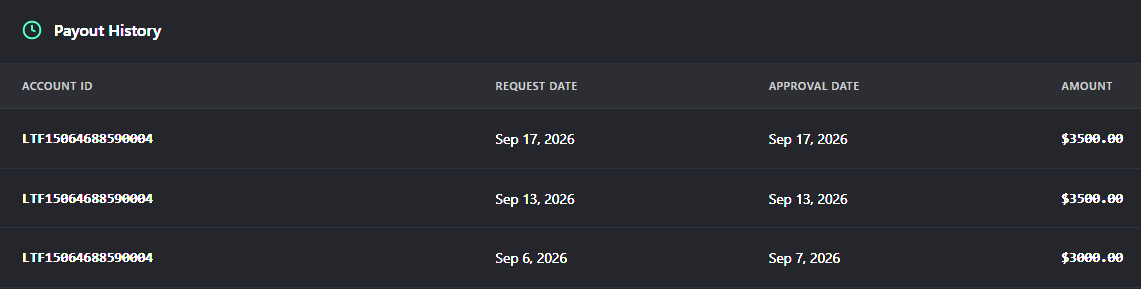
@Shinobbs Thanks! But can someone help me understand the process to getting one of these? Why are one of the letters blocked off? What code would I actually enter?
So far at $10k in payouts from 1 singular @TradingLucid $150k Pro account.
Going to give 5x people who like and retweet a FREE lucid account.
Make sure you are also in the free discord: https://t.co/rmNCfhD88B
SPX options are priced on a forward curve.
The underlying SPX value for a year out option is NOT THE SAME as the underlying SPX value for a 0DTE.
Right now you have around $230 between Sep24 and Sep25 - the futures settlements on the CME website give you a quick view of the forward curve by quarter:
https://t.co/UGC75TOKZj
Loosely- this difference is just compounding the spot value (today’s SPX level) by the difference between the risk free (FOMC 5.25%) and the current dividend rate (SPY Div yield 1.26%).
Intuitively, this should make sense— you’re accounting for a basic cost of capital:
with cash you earn a yield but no dividend; and with SPY you receive dividends but no yield.
What happens if the Fed is forced to cut aggressively into a rapidly deteriorating economy?
If the market drops, and rates are cut…
…your long dated puts pay you *twice*
They move broadly with everything else as SPX (spot) sells off,
..and then rate risk manifests when those “risk free” rates get repriced.
Suddenly the forward value of SPX (the value your puts are technically priced on) gets repriced EVEN LOWER, too. 👀
Because the “risk free” rate from that relationship above is much lower.
For most of the last 15 years the forwards were INVERTED…
—because rates were non-existent!!
So let’s say your hedge is a 1y out 50d put and the market drops 10%, or roughly 550 points AND rates are aggressively cut ~3%…
Even though the index only dropped 550 points…
YOUR puts are priced against an underlying which fell ~$700 in total $$$
…and likely slid up the skew curve into higher vols 💰
ALL THANKS to the impact of rate cuts on the forwards 🍻
@KobeissiLetter@grok What is an alternative outcome to rate cuts and rising inflation? Is it possible that inflation will not continue and, if so, under what circumstances would this take place? What are the odds for either scenario?
Reopening access (only for a couple more days)
My ULTIMATE OPTIONS MIND MAP drop (FREE!)
A 2‑video blueprint I wish I had before ever placing a single trade.
Here’s what’s inside:
- how to go from raw idea → defined trade structure
- the full checklist for risk management + execution
- strategy map covering 95% of what I actually trade
- Plus more frameworks
This is for traders ready to stop guessing and start operating like true portfolio builders.
Reply “MAP” + retweet and I’ll DM you instructions to grab both videos (must follow so I can DM u)
Only available a couple more days!
This is what McElligott flagged in his June 25th note
Apparently Nomura's model triggered its largest buy signal in its ~21 year history, projecting $114B of US eq's to buy over the 1-month forward period.
The 9 prior signals didn't come close to the magnitude of the size here- and the backtest data Charlie provided indicated that 100% of the time (upon triggering this signal), the index is HIGHER both 1 and 2m out, with median returns of 2.5% and 4.4% respectively
Loosely benchmarking the trigger against the closing level of the SPX (6092) the date he sent the note (6/25), the median returns put the index at 6244 on July 24th or 6366 on August 24th...
This actually provided a GREAT example of how to think about the duality of options (of course I'd weave those in)
The SPX dealer positioning was significantly skewed with MMs short calls in size throughout the July expirations
This was the case for a while, and it's why in my Sunday night spaces prior to June OPEX week I flagged the potential for spot-up/vol-up behavior right ahead
Sure enough, within a few days, we had SPX up, VIX up AND VVIX up- and generally we've had spot-up vol up behavior since I flagged it.
Even if you didn't have accurate dealer positioning data, you could still see the "tell" here in 1M vs 3M skew percentiles and skew betas-
Why did it matter?
...duality of hedging flows. Short upside gamma NEEDS A CATALYST or else you wind up ironically forcing the index AWAY from the dealer's short option strikes.
...$114B from VC community was obviously a pretty good catalyst, and we talked in the mentorship about options structures that perform well in a spot-up / vol-up environment.
Last newsletter I wrote, I noted that since the note (6/25) the index had already climbed 3.1% in just 5.5 trading days... remember the median move... "2.5% 1m forward return"
the dealer short call positioning most definitely exacerbated the move- combination of gamma and short vanna that helped knock in accelerant buying flows (short vanna evidenced in VIX +1.2 pts during the week SPX rallied 1.7%, with fixed strike vols higher)
The crazy part?
of the 114B in projected buying over the 1-month forward period, less than $1b of it was slated to hit in the first week.
1b down, 113b to go?