Big thank you to @VinnyPardi and @River for sending me a hat! I’ve always been a proud supporter of River and it’s my favorite exchange to stack sats and stay humble. Excited to wear this around town 🙌
Bitcoin’s 5 year return is about 22% compared to the S&P 500 with about a 61% return. Long term holders are feeling the pressure of making the wrong investment choice, and I can relate. However, Bitcoin’s 10 year return is 10,805% compared to S&P 500 at 263%. BTC may not be the best investment choice for a person close or already in retirement, but for younger people who have 10+ years to invest, it is still shown to be the best. History will reveal the results eventually. Stack sats and stay humble.
The 40-hour week was sold as the path to a stable life. For most people it’s the opposite: 40+ hours just to cover rent, food, taxes, and inflation that quietly eats whatever is left. The hours you trade for survival are the same hours you don’t get back with your kids, your partner, or the people you actually care about. Birthdays, school events, quiet evenings. Those are the things that get postponed until “later,” and later keeps moving.
Fiat money makes this permanent. Governments and central banks can expand the money supply whenever they want, so the value of the hours you already worked slowly evaporates. You have to keep running just to stay in the same place. That is the real unfairness: your time is finite and non-renewable, yet the currency you are paid in is designed to lose purchasing power over time.
#Bitcoin is the exit. Fixed supply, no central issuer, no one who can dilute the work you already did. You convert some of the hours you are forced to sell today into an asset that is not subject to the same inflation schedule. Over multi-year periods that has repeatedly turned modest savings into enough capital that the trade-off changes: fewer hours required for the same lifestyle, or the same hours buying more freedom. It is not magic and it is not risk-free. Volatility is real and you can lose money. But it is the first widely available tool that lets ordinary people opt out of the endless cycle of trading time for depreciating currency.
Stack sats instead of stacking more hours. The goal is not to work forever. It is to own something that works when you stop.
@BitcoinBandi@marc02200 My understanding with SATS is it won’t be pegged around 100 so though the dividend is higher, the value could drop which might hinder the value in case of an emergency.
You get 18 summers. Then they’re visiting.
You get 940 weekends. Then they have their own.
You get 6,570 bedtimes. Then silence.
Time is the only real currency of parenthood. Spend it wisely. You can’t earn more.
@marc02200 I haven’t either but at some point I do want cash flow. Considering taking a loan on btc to buy something like STRC, down the road. Won’t take any action below $200k BTC however. Thoughts?
The biggest mental battle I have as a parent is between how “rich” Bitcoin can make me and my family vs how much time it can give us back. As we enter a new bull market, I think denominating our gains with family time is the most important factor. Question to you, how much is enough?
Your kids won't care what your portfolio did this cycle.
They'll care if you were home for dinner, and if there was something solid left for them.
Good morning, go be great. 🧡
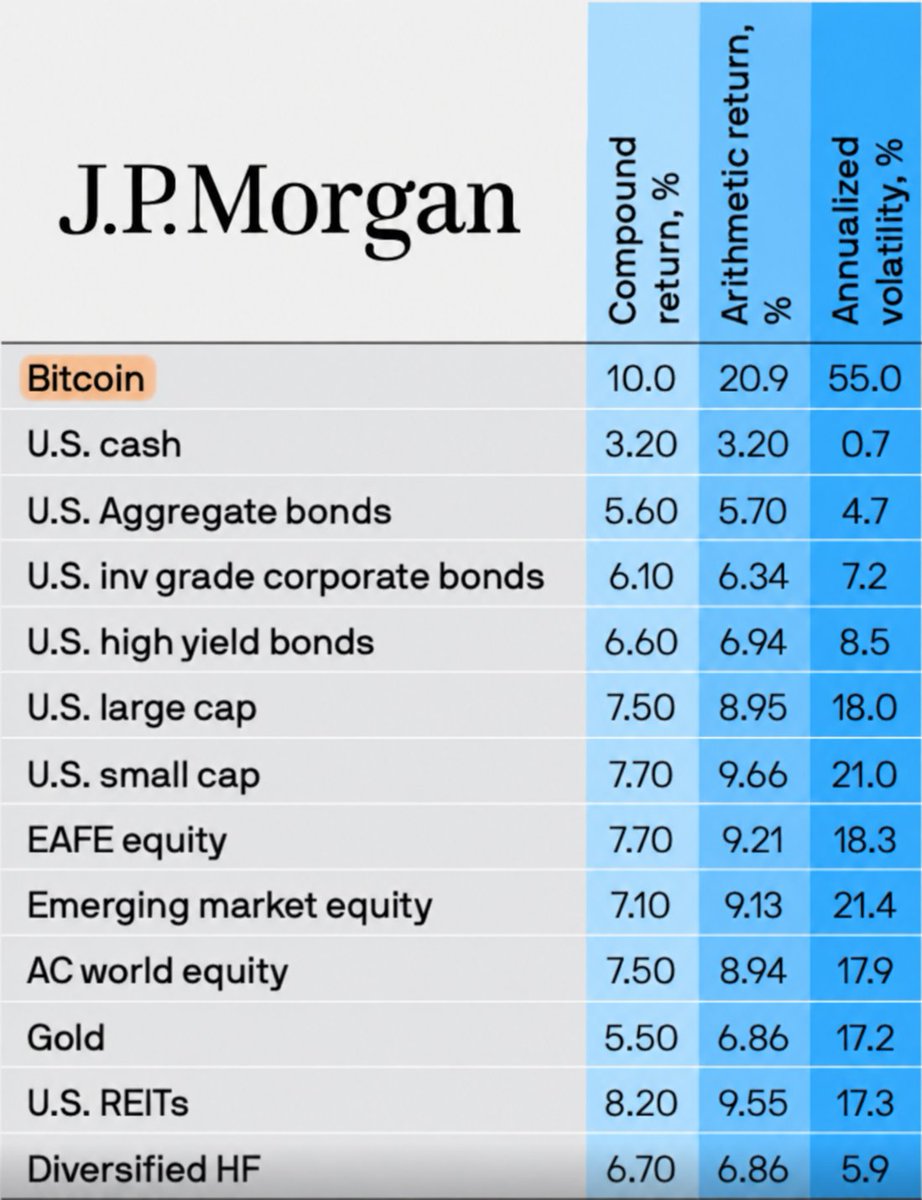
JUST IN: The largest bank in the U.S. JPMorgan is forecasting Bitcoin to outperform every major asset over the next decade.
You are not bullish enough 🚀
Honored to be on the @CincoDoggos Mining Show season finale to talk about the talent side of Bitcoin.
Keep an eye out! It airs later this week.
Follow Cinco for more on-the-ground Bitcoin mining insights. ⚡️
My top priority in life is financial freedom. When I entered the Bitcoin journey, I was expecting to be financially free in a few years with an easy ride. Truth of the matter is that finding financial freedom through Bitcoin isn’t easy. You have massive volatility that can deter your conviction. I believe that freedom CAN be acquired through a decade of consistent DCA and the occasional smash buy. But give yourself 10 years. Maybe it’s sooner, but prepare your mind to be in the trenches for a while.
I have been looking for a clean way to start a bitcoin stack for my kids while they are still young. Most exchanges will not let minors open accounts, and I did not want their sats mixed into my own balance where I might spend them or lose track. River solved it. I already had my personal account, then I messaged support and they set up two more sub accounts under my kids’ names. Buys can pull straight from the linked bank, the balances stay separate in the app, and I can move bitcoin between them when I need to. It is a simple way to stack for them now and hand it over later when they turn 18 and can open their own account or take a wallet.
Check them out at https://t.co/Ams550z6uH or @River
Taxes stay on me while the bitcoin sits in those sub accounts because everything is still under my name. Buys are not taxable events. Any sales get reported on my return with my cost basis. The gift happens when I actually transfer the coins to them. Value it at the price that day. The annual exclusion is $19,000 per kid for 2025 and 2026, or $38,000 if my spouse and I split the gift. Anything over that just uses part of the lifetime exemption in most cases, and they inherit my original cost basis. This is not a formal UGMA or UTMA, so the ownership shift does not happen until I send it. Not tax advice, just how I am handling it. Worth a quick check with a CPA who knows bitcoin.