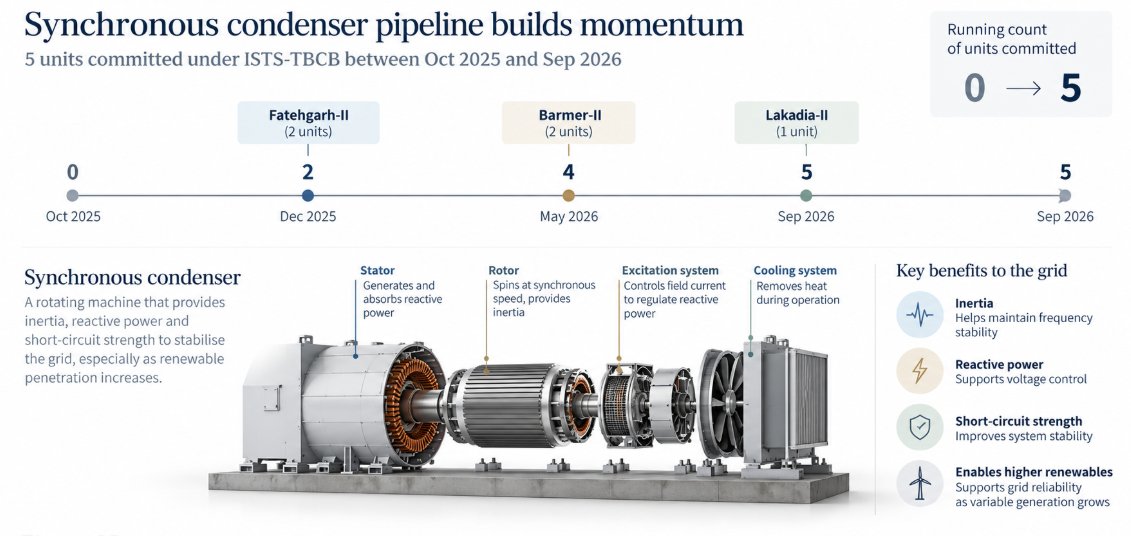
A piece of hardware that barely existed in Indian transmission tenders a year ago is now part of three separate mega-schemes - the synchronous condenser.
Tracking unknown sectors hasn't been easier before!
Sunil Singhania 🔥
Abbakus venture opportunities fund
Again participates in Anchor allotment
Adroit Industries raised 45.21 Cr from anchors, IPO proceeds for capex & debt repayment
Sunil Singhania was the joint-biggest bidder
Invested ₹10 Cr & Now holds 4.15% Stake
Adroit is an Indore driveline-parts exporter 95% of product sales go overseas - US the biggest
Last few where Abbakus backed as anchors -
Steamhouse - ₹10 Cr
Credent - ₹5 Cr
Poojaa - ₹14 Cr
Caliber - ₹10 Cr
Ashish Kacholia is back with another smallcap bet 🔥
& this time, it’s Qualitek Labs
Company is raising ₹47 Cr through a preferential issue & Kacholia is largest non-promoter allottee
Qualitek operates in testing, inspection & certification across Auto, Defence, Pharma
Invested ₹8.98 Cr for 1.5% Stake In PA
Was already holding 4.4% Stake previously
Recent preferential bets -
Venus Pipes - ₹30 Cr
Inox Green - ₹33 Cr
Asian Energy - ₹15 Cr
Brand Concepts - ₹15 Cr
Small Company & Niche business, Intresting 🔥
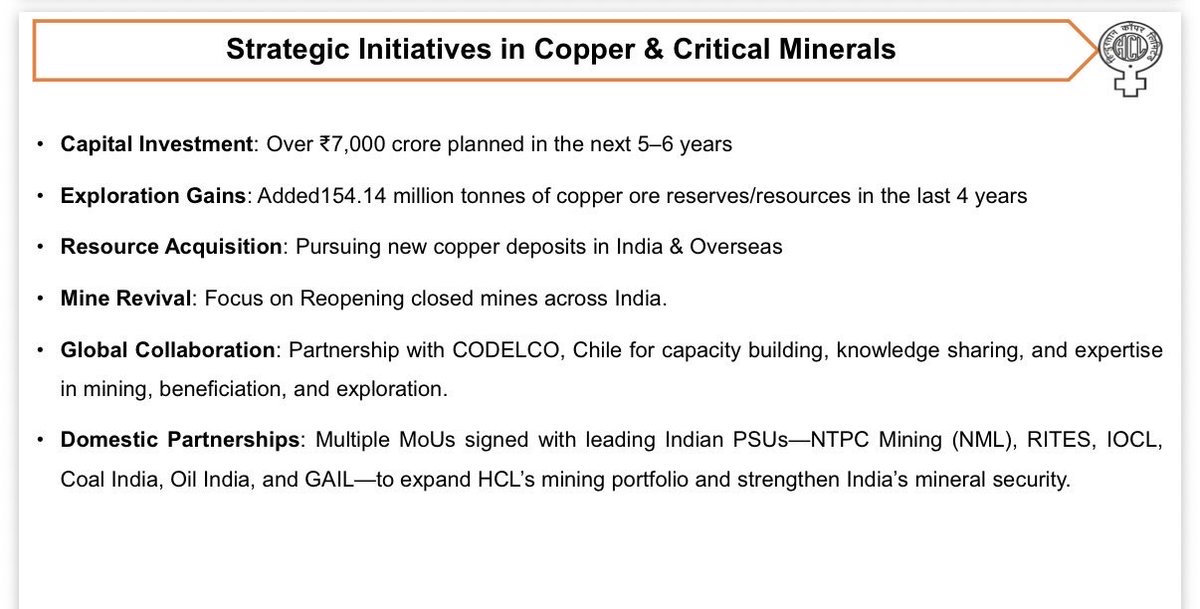
Hindustan Copper: India’s Copper Giant is preparing for a massive scale up!! ✅
#hindustancopper#sabarisec
This is not merely a copper-price story. Look at HCL’s roadmap:
🔸 Access to ~45% of India’s copper ore reserves & resources
🔸 785.99 MT resource/reserve base
🔸 ₹7,000+ Cr investment planned over 5–6 years
🔸 154.14 MT of resources/reserves added through exploration in just 4 years
🔸 New copper deposits being pursued in India & overseas
🔸 Closed mines targeted for revival
🔸 Strategic collaboration with Chile’s CODELCO
🔸 Partnerships with leading Indian PSUs
And the BIGGEST trigger 👇
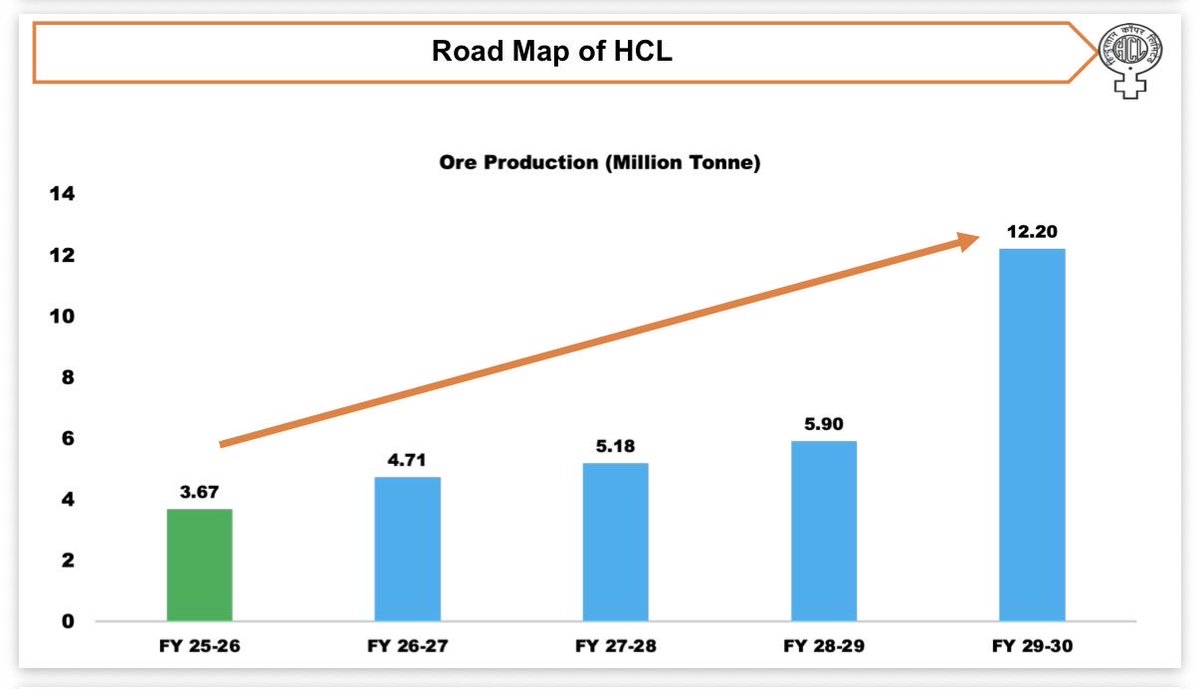
Ore production roadmap:
FY26: 3.67 MT
FY27: 4.71 MT
FY28: 5.18 MT
FY29: 5.90 MT
FY30: 12.20 MT 🚀
That is a targeted ~3.3X increase in ore production from FY26 to FY30.
As India enters an era of massive electrification—power grids, renewables, EVs, railways, electronics and data centres—COPPER increasingly becomes a strategic resource.
Hindustan Copper is positioning itself at the centre of that transformation.
Scarce resource + Massive capacity expansion + Exploration + Strategic importance = A business worth closely tracking through FY30. 👍
The opportunity is significant, but execution of the mining expansion and copper-price cycles remain the key variables to watch.
I follow three types of stop losses
Let’s call it the PTT framework
Price stop loss: only when earnings momentum completely breaks and 30Wema is broken on big volumes or I have decided to sell a stock in big momentum but in these cases I will trail my selling using 10/21wema.
Time stop loss: usually I don’t give more than 6-8Quarters post buying if a stock stops moving for n number of reasons. We have to respect Mr Market. We can also call this the opportunity cost stop loss.
Thesis stop loss: thesis is bent broken and beyond belief. I go completely wrong in my business analysis. In such cases I exit regardless of the price.
PTT framework of stop losses
For the past 4 years, several respected and well-meaning voices have repeatedly warned investors about small caps, midcaps and SMEs. Alongside this, we have consistently heard that large caps are relatively cheaper and that money should rotate towards them.
The concerns have not been entirely misplaced. There has been speculation, weak governance and unjustifiable valuations in parts of the market. But identifying excess in some companies is very different from declaring an entire segment unattractive or repeatedly calling a market top.
A valuation call by itself is rarely enough for me to take meaningful money out of equities as an asset class.
I would consider doing that when excessive valuations along with investor leverage and excessive corporate leverage come together with a business cycle that is on the verge of turning. That is when the risk becomes systemic. Companies can go bust, capital structures can unravel and businesses that never deserved their valuations can fall 90–99%. That is not an ordinary market correction. It is permanent destruction of capital from which many companies never recover.
Current market conditions do not remotely resemble that setup. We do not see excessive leverage across investors and corporates, nor does the business cycle appear to be on the verge of a major downturn. Corporate balance sheets are broadly healthy and several investment cycles are still unfolding.
This is why repeated valuation-led calls on the market have largely been ignored. The market may correct, consolidate or rotate. Individual stocks can certainly fall sharply. But without systemic leverage and a turning business cycle, a broad call to move away from equities can create more opportunity loss than protection.
Many investors would have been better served by spending less time debating small caps versus large caps and more time identifying where the next profit pools were emerging. The opportunity was never in a market-cap category. It was in businesses undergoing meaningful change.
This is also why we prefer to begin with themes rather than valuation screens.
Where is the world changing? Which industries are reaching an inflection point? Where are new profit pools being created? Which companies have the capability and the right to win?
Valuation comes after understanding the opportunity.
If the starting point is purely mathematical valuation, many of the biggest opportunities will appear expensive precisely when their future is beginning to change. A screen can tell us that 10x P/E is cheaper than 40x. It cannot tell us when 10x is expensive and 40x is cheap.
The job is not to permanently favour small caps, midcaps or large caps. Nor is it to keep predicting the next market top.
The job is to keep finding new themes, identify the businesses best placed to capture them, pay a sensible price and remain invested while the thesis plays out.
Risk must be respected. But opportunity cost is also a risk. #markets #thematicinvesting #marketcapagnostic
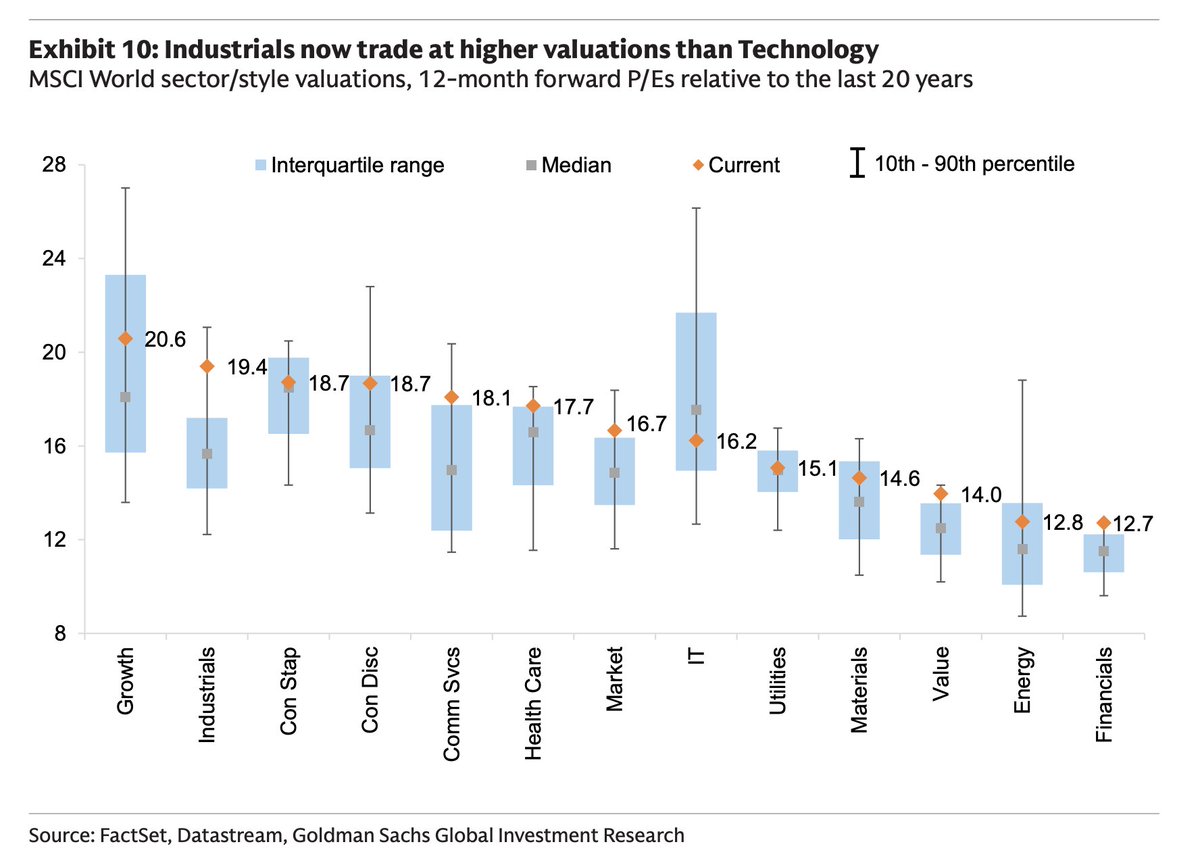
Real PE expansion has happened in Industrials, not in Technology (which is what everyone perceives).
Interesting chart put out by Goldman Sachs.
While frontier models can continue debating on path to profitability, capex today is real and bottlenecks are getting constrained.
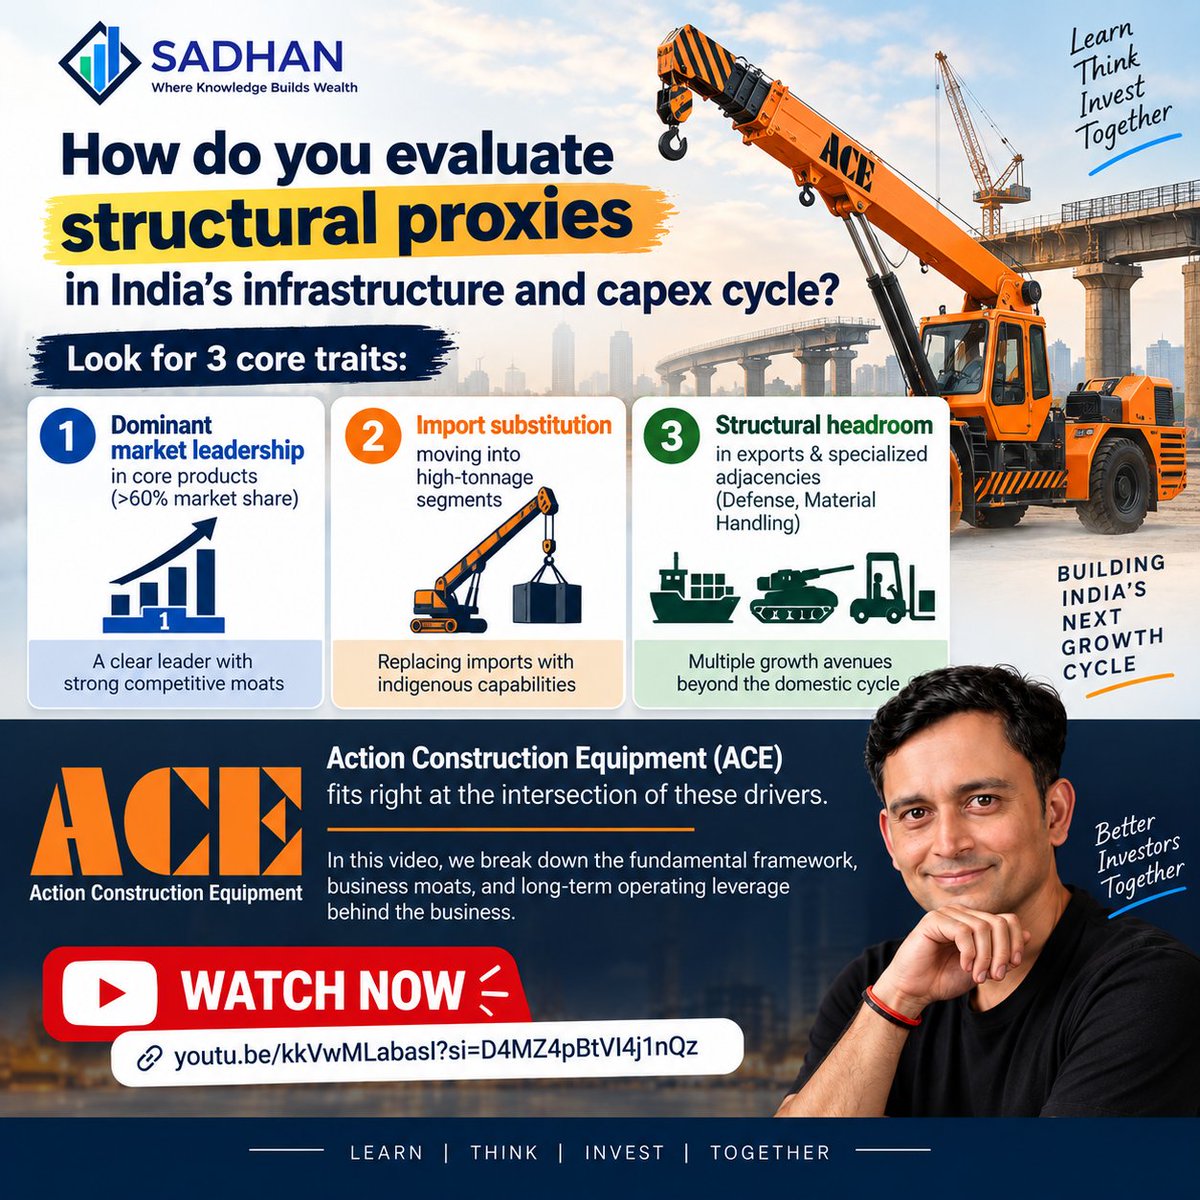
How do you evaluate structural proxies in India’s infrastructure and capex cycle?
Look for 3 core traits:
Dominant market leadership in core products (>60% market share)
Import substitution moving into high-tonnage segments
Structural headroom in exports & specialized adjacencies (Defense, Material Handling)
Action Construction Equipment (ACE) fits right at the intersection of these drivers.
In this video, we break down the fundamental framework, business moats, and long-term operating leverage behind the business.
📺 Watch the full deep dive here: https://t.co/0auMSlgTIv
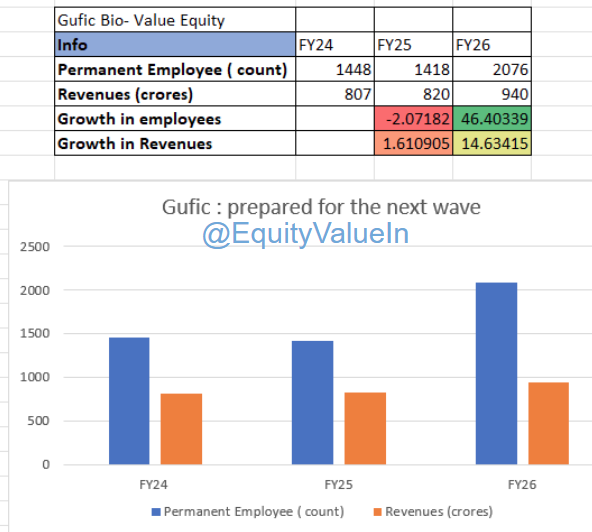
Gufic Biosciences , hiding the operating leverage in the employee count which is not yet visible in revenues , Indore has reached 30% , costs are loaded , everything else will flow to bottom-line in the time to come Very excited for this year in Gufic, read my below note and also substack detailed note on why I think it is at an inflection point
disclaimer : this is not investment reco/financial advice , just for research , consider me biased here , do your own due diligence
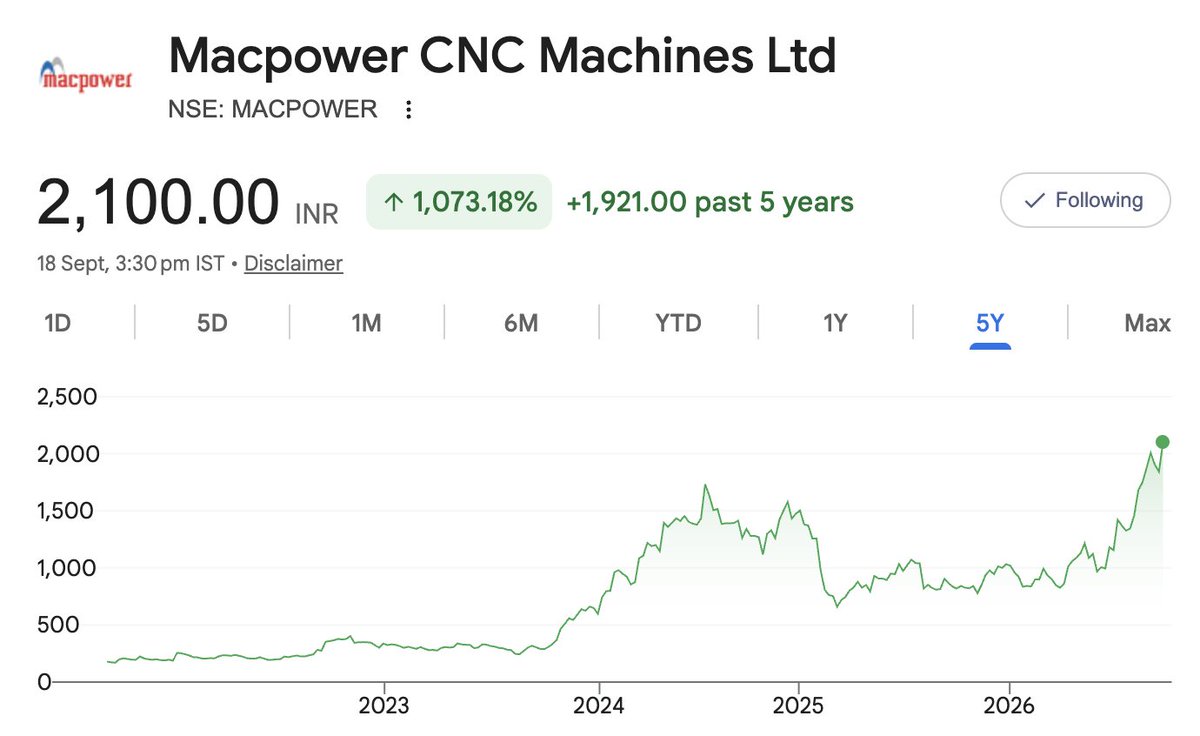
World famous MIT missed out on 10x returns in 3 years!
Massachusetts Institute of Technology (MIT) has some of the most brilliant and intelligent individuals in the world.
Yet, MIT's fund managers sold Macpower at the absolute worst possible price in 2023, at just around ~220 per share!
Meanwhile, small retail investors like me were filling up the truck.
4 pages of buying Macpower!
Shivalik Rasyan , suddenly the thesis is being spoken about everywhere, again some popular folks were too early here , some will come much later , but when odds were good and risk reward was best we were there!
Same business , but our diffrentiated insights approach
Timing matters , especially in these type of businesses
no reco, consider me biased from lower levels , no reco , no advice
Indegene , beyond the numbers lets look at some of the key financial and opertaing metrics
Active clients gave gone up to 105 from 70 ( think about incremental wallet share gains from newer clients)
Revenue per employee $77K up from $67K , some industry leading metrics
Client concentration risk keeps reducing ( a big issue has played out here already ) , 2 new client additions in the 10-25M$ category , and employee hiring continues,
Really think market is underestimating this business !
disc: this is no investment advice/reco , this is just my opinion , consider me biased from lower levels , do your own due diligence
Am I the only one with this feeling??
Credit cards were a trap disguised as convenience. By removing the physical friction of handing over cash, they made us spend more because the transaction felt abstract.
Now, big tech is doing the exact same thing to human agency.
Look at the relentless cycle of iPhone upgrades or the launch of "agentic AI" like Meta Muse. We are being told that handing over our emails, calendars, financial data, and daily decisions to a virtual machine is the ultimate "upgrade".
But outsourcing your life isn't convenience—it's a surrender of control.
Why can’t life be simple anymore?
Because simplicity doesn't generate data. If you are in control of your own routines, you aren't a profitable ecosystem. So, tech companies inject apps into the middle of basic human actions, forcing us to adapt to hardware and software changes nobody actually asked for.
Privacy isn't dying a natural death. We are actively trading it away for frictionless living, letting algorithms manage our lives so we don't have to.
Living a simple life shouldn't require a software update.
Joe Rosenfield lost almost everything that usually makes a life feel whole.
In 1962 his only son, a high school senior, died in a car accident.
Fifteen years later his wife died too.
After that he had no children and no partner left at home.
Most people would have folded inward. He did the opposite.
He poured the rest of his life into a small Iowa college almost nobody had heard of: Grinnell.
He treated its endowment the way other people treat a child. Protect it. Grow it. Make sure it outlives you.
He and a then unknown investor named Warren Buffett made a handful of unusual bets: early money in a tiny chip company that became Intel, shares in Buffett’s own company, even buying a TV station. They held on for decades.
The college’s nest egg went from about $11 million to more than a billion.
Buffett later said something rare. After his own father died, he told people he would never have wanted to replace his real father, but if he could have adopted Joe as his father, he would have.
Rosenfield never talked much about the son or the wife he lost. He just kept showing up for the college.
The money he grew still pays for students who never met him.
That is the quiet version of winning. When the private world collapses, you pick a public one worth serving and stay with it until the work is bigger than the grief.
Shivam has written only 5 pieces in our ZN blogs in the last 18 months.
-2 out of them feature in top 3
-Remaining 3 in top 20
This weekend, he's written for the 6th time.
When Shivam ✍️ I leave everything and read it. What do you do?
Go Read!
https://t.co/TlqKkueKbg
Strongest themes in the market today:
1. CNC Machines
2. Copper wires
3. Paper
4. Water sector showing signs of revival
5. New age Platforms
6. EMS businesses
7. Dyes and Pigments
8. Chemicals
9. Steel tubes
Polycab Family Office 🔥
Everyone knows Polycab, but very few know this
Jaisinghani family’s exposure goes well beyond Polycab, across multiple Mainboard & SME-listed companies
Mainboard Companies -
La Tim Metal
Jaro Education
Sai Parenterals
Ardee Industries
Arrow Greentech
SME Companies -
L.T. Elevator
Star Finvest
Parth Electricals
Yash Highvoltage
Shanti Inorganics
Qualiance International
Grand Continent Hotels
& Separately, Polycab holds ₹3,405 Cr in current investments, largely in debt & arbitrage funds
Polycab story is bigger than just Polycab 🔥