@oldrightonig My mistake for selling $RL shares in 2021. $RL made sense to me as a covid recovery play. I’ll never understand the psychology of the shopper who pays >$600 for a jacket that probably sells for $34 at $TJX or $15 on $EBAY
@ACapitalLP Similar thought recently. Wondering if UBS is outsourcing equity research to India? Every time a UBS analyst asks a question, it seems to be an Indian with a thick accent. I have no bias, but shouldn’t a “high touch” Wall Street job go to native English speaker?
@tierrapartners Inclined to agree but core PCE in every time period (3, 6, 12 months) is around 70-100bps above target, and not showing a favorable trend. Strip out NYC & Co and still above target.
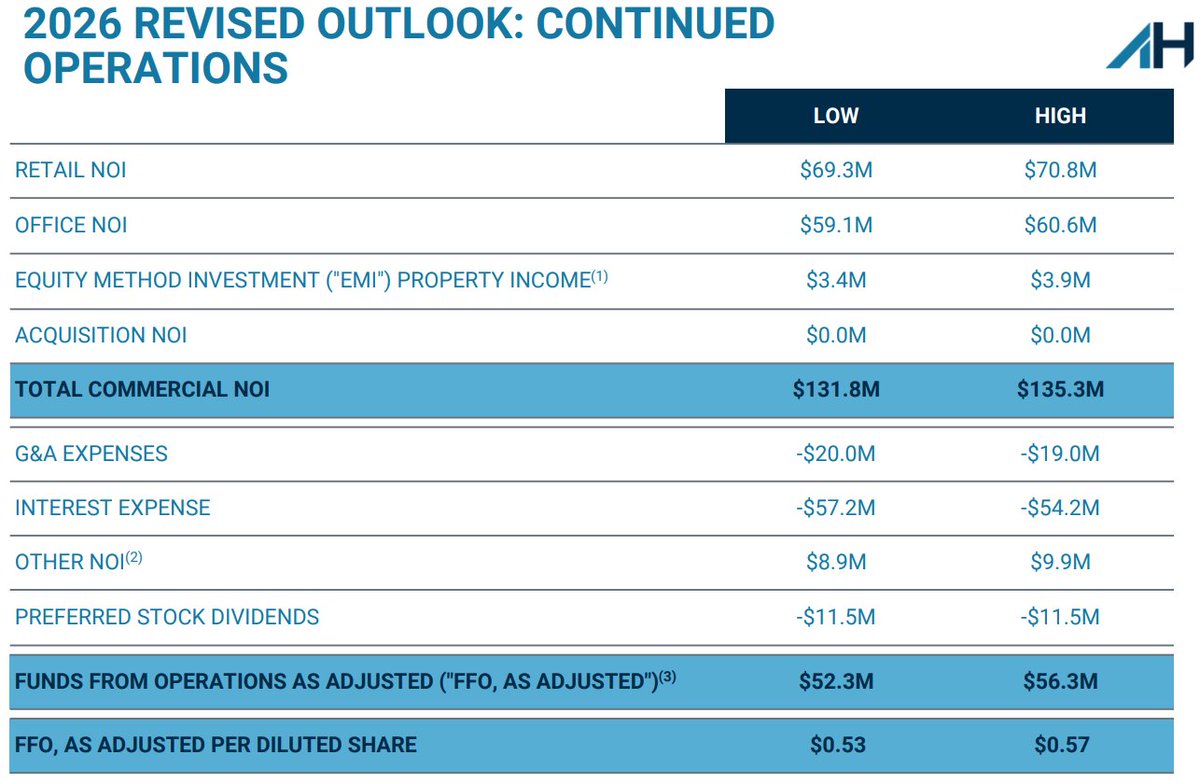
Generational transition at $AHRT continues. Plausible that a sales process will occur in 2027 after $AHRT completed its occupancy inflection.
https://t.co/EzyN5AN2qa
$AHRT Board Changes:
On November 5, 2026, AH Realty Trust, Inc. announced that Daniel A. Hoffler resigned from the Board of Directors, and David Z. Hirsh was appointed as an independent director to replace him, effective immediately; Hirsh has over 30 years of real estate investment experience.
(Visit stockinsights dot ai for full context)
$AHH trading at nearly an 11 cap rate, noticing that 2Q results and stabilized NOI look much better vs 1Q. New mgmt conveniently negotiated a new share based comp package at the all-time low (after cutting the dividend and raising new equity).
@grok@WantMakeRE@ColeKenefsky_ So that implies the Austin market will reach 95% occupancy in 2030 or later. Is that correct? What is the probability of significant rental rate growth before the overall Austin market achieves 95% occupancy?
@grok@WantMakeRE@ColeKenefsky_@ColeKenefsky_ Colliers data excludes lease-up apartments. Market occupancy is 89-91%. If you compare net absorption vs new supply, the difference of sub 2,000 units implies 3+ years to absorb before the overall market reaches 94-95%. Curious to hear how I might be wrong?
Since I made this tweet, Canadian mid-caps multi-family REITs have sh*t the bed. $MRG.UN is pursuing a nonsensical related party deal, following value destructive deal in 2025 by $HOM.UN, and the evolving corporate governance crisis of $HR.UN.
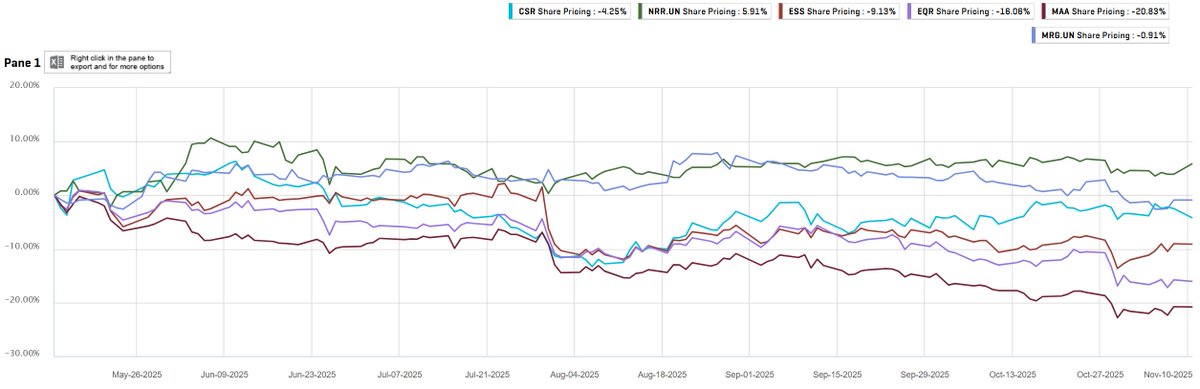
Interesting dynamic last 6 months, large multi-family REITs with low leverage ($MAA, $EQR, $ESS) significantly underperform mid cap REITs in tertiary markets with much higher leverage ($CSR, $MRG.UN, $NRR.UN).
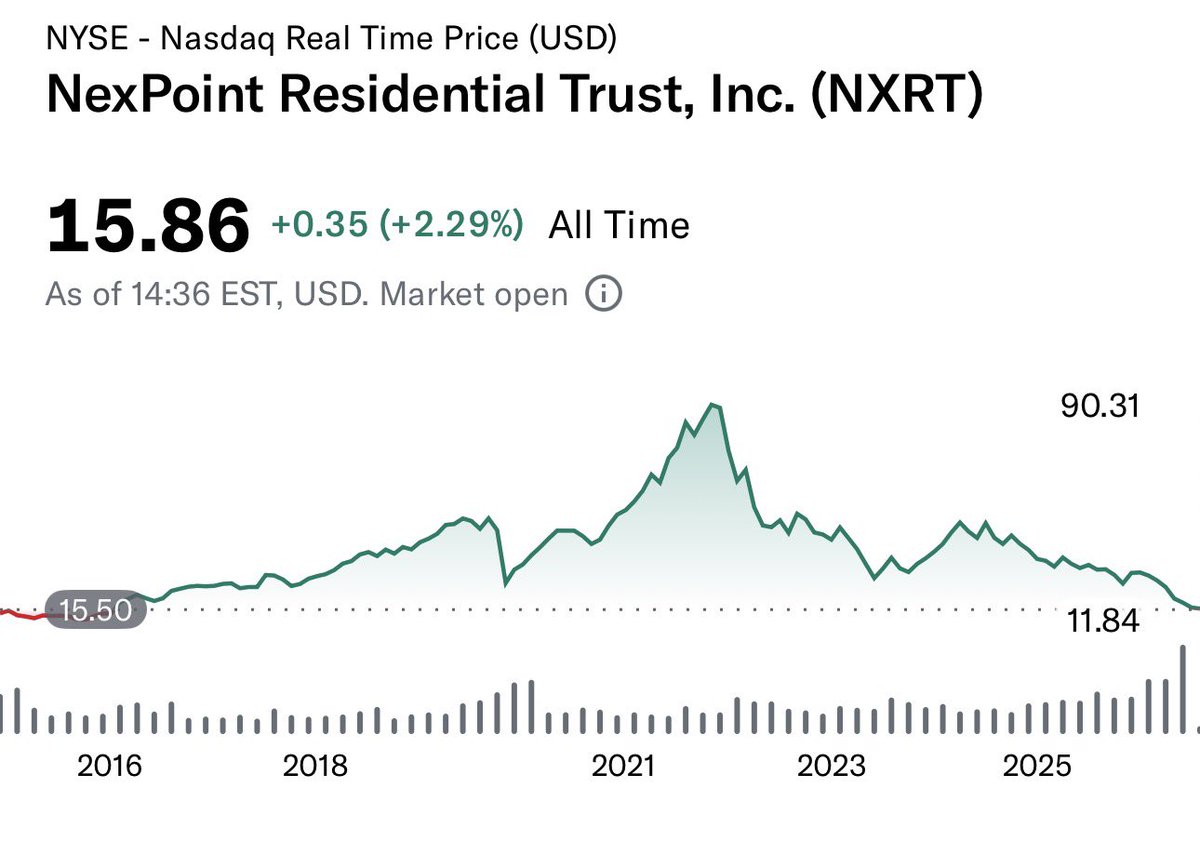
$NXRT approaching all-time low, maybe going to $10/sh. My humble opinion is that mgmt will announce a dividend cut and sale process / strategic review. They soft announced this in last weeks’s call. Likely gets bid at $20-30/sh, with mgmt rolling into a private deal.
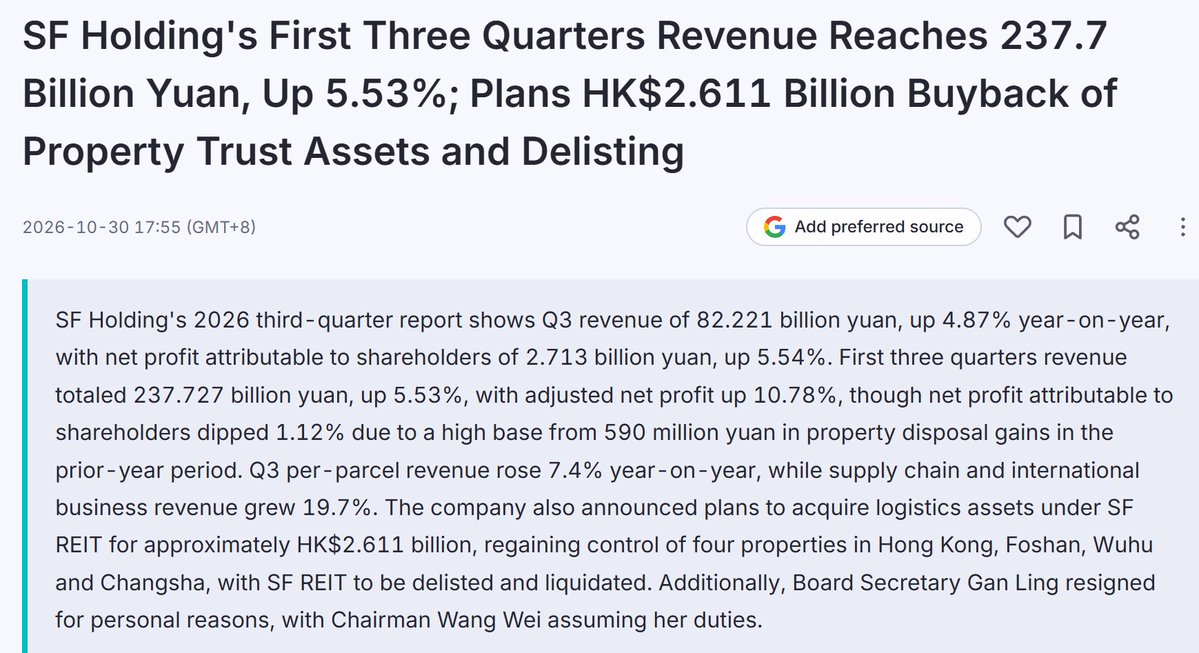
Parentco delisting and acquiring SF REIT $2191.HK (with a reasonable premium) was not on my list of likely events for 2026. Next should be privatizing the listed stub of KLN Logistics $0636.HK, which is a high quality business trading at 7x P/E.
SF REIT $2191.HK cuts rents payable by its parent by 20-45% in "realignment with prevailing market". Leverage was elevated at >7x ND/EBITDA before the rental cut, 90% payout ratio also elevated. Not uncommon for REITs to be listed with above-market rents, followed by a rug pull.
@Mr_Neutral_Man Congrats for making money on liquidation trades! This has been a more difficult year for my style of pre-announce situations ($CSR, $HR.UN, $HOM.UN, $SKG.AX)