Steven Fiorillo's bullishness on $SOFI got me fired up, so I wrote a short article thoughts.
Also be sure to check out Steve's latest video (in the reply below). Already has 20k views in the first 6 hours. Champ status.
https://t.co/oMiLeW3Usm
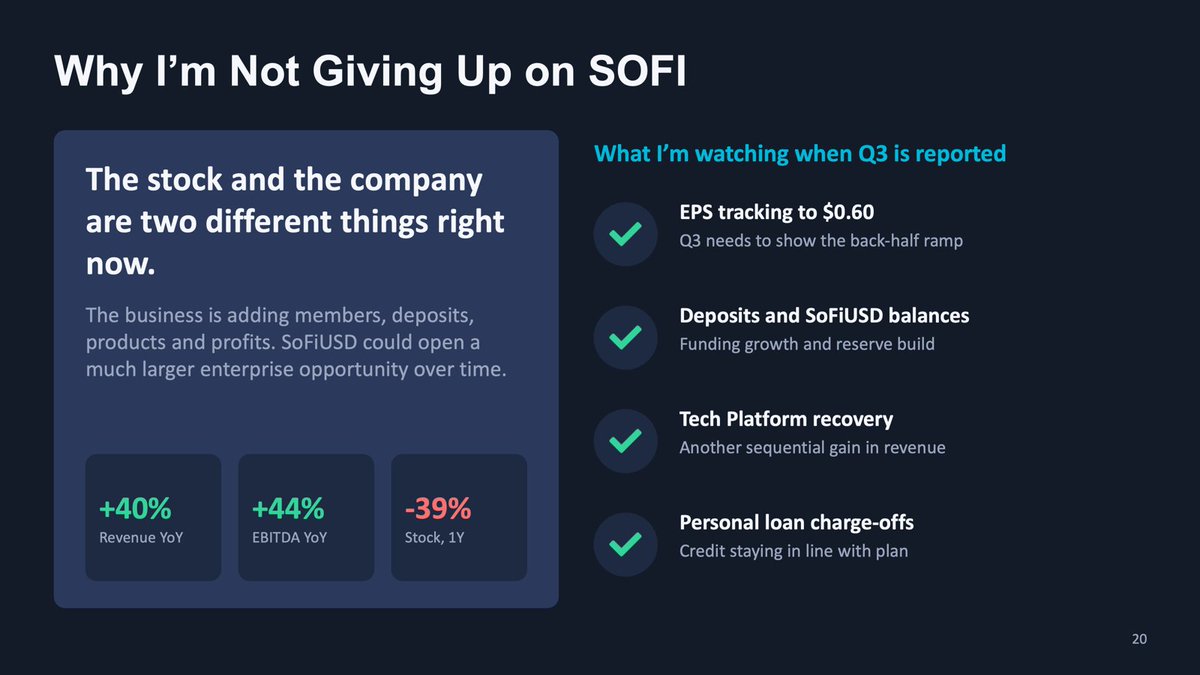
I’m jumping into the $SOFI discussion with my unfiltered take. The stock is down roughly 40% this year, while Q2 adjusted net revenue grew 40% YoY. That gap deserves a closer look.
When I dig into the numbers, I see a growing customer base, rising deposits and expanding earnings power. Our interview with @anthonynoto on @basispointpod gave me another reason to stay bullish: the potential for SoFiUSD to become a meaningful part of this business.
Start with the actual results:
• Record adjusted net revenue of $1.2B, up 40% YoY
• Adjusted EBITDA of $358M, up 44%, at a 30% margin
• GAAP net income of $157M, up 61%
• Adjusted net income of $160M
• GAAP and adjusted diluted EPS of $0.12
• Eleven consecutive quarters of GAAP profitability
The bank charter remains one of the biggest reasons I like this business.
Deposits increased $5.3B in a single quarter to $45.5B. Deposits represent roughly 93% of SoFi’s funding base. Management estimates approximately $713M in annualized funding savings compared with warehouse financing.
That funding advantage matters when you’re competing for borrowers and building a profitable banking franchise.
Then look at the member relationships.
SoFi added 1.1M members and 2.2M products in Q2, ending the quarter with 15.8M members and 24.4M products. Products per member reached 1.54.
The number that stands out to me: 51% of new products were opened by existing members, versus 35% a year earlier.
SoFi is bringing people in and giving them reasons to do more of their financial business on the platform.
Fee-based revenue reached $472M, up 22% quarter over quarter and 25% year over year, representing 39% of adjusted net revenue.
The Loan Platform Business gives SoFi another way to grow: originate loans for outside investors, earn fees and retain servicing relationships without keeping every new loan on its own balance sheet.
Total originations reached a record $14.8B, with management reporting credit performance in line with expectations. Tangible book value increased $226M during the quarter to $9.5B, with tangible book value per share rising from $7.21 to $7.34.
At Q2, management raised full-year adjusted revenue guidance to $4.75B–$4.85B, representing approximately 32%–35% growth. It maintained targets of roughly $1.6B in adjusted EBITDA, $825M in adjusted net income and $0.60 in adjusted EPS.
Now add the opportunity Anthony Noto walked us through with SoFiUSD.
What got my attention was the potential to build a payments and enterprise banking business that reaches well beyond SoFi’s consumer membership.
Noto described several routes to adoption: settlement with crypto exchanges and market makers, Mastercard’s network, existing Galileo clients, and Big Business Banking.
There is already a concrete starting point. On September 22, SoFi announced that stablecoin settlement was live for its debit and credit card program, which it is migrating to SoFiUSD with expected annualized volume exceeding $25B. Broader adoption by outside businesses is the next opportunity.
The economics Noto described are what make this interesting.
He used an illustrative $5B reserve balance earning 3.8%. If SoFi shared 1.8 percentage points with partners to encourage adoption, it would retain a 2% annual yield.
Maintain $5B in average reserves at that spread, and the math is $100M annually before operating costs and taxes.
Using that same assumption, $25B in average reserves would produce $500M annually before those costs and taxes. That is my illustration of the potential scale, not company guidance.
And those reserve balances are different from annual payment volume. The same dollar can settle many transactions. A $25B payments program does not automatically create $25B of reserves.
For perspective, the Q2 deck reported roughly $300M of SoFiUSD in circulation. Reaching multibillion-dollar average balances would require substantial adoption.
The bank charter matters here, too. SoFi can hold reserve cash directly at the Federal Reserve and earn interest. Noto also described opportunities for subscription and transaction fees through Big Business Banking, alongside trading and other services.
That gives SoFi several potential ways to monetize these relationships, even if it shares a meaningful portion of reserve income to attract partners.
This is why I think SoFiUSD could become a significant business. SoFi has a bank, its own technology platform, existing enterprise relationships and a live settlement use case. It has a foundation to build from.
The size of the payoff will depend on adoption, average balances, interest rates, partner incentives and execution.
There are still things to prove across the company. Tech Platform revenue fell 23% year over year, despite improving 13% sequentially. Fee revenue is growing, but its share of adjusted revenue remains below last year’s level. Q2 return on tangible common equity was 7.1%, leaving substantial work to reach management’s 20%–30% long-term goal.
Credit performance and valuation still matter.
I remain bullish because the existing business is adding members, deposits, products and profits, while SoFiUSD could open a much larger enterprise opportunity over time.
A 40% decline alone doesn’t make a stock cheap. The combination of operating progress and future earnings potential is what keeps me interested in $SOFI.
Expect a video to drop tomorrow morning where I go through my entire thesis on SOFI as we head into the Q3 earnings report.
Taylor to camera- And now I can say he (Drew) is a fucking idiot. I told him he would have a better chance at winning HoH if he had me and Dee than me and Devens, and now he just signed for second place. Signed, sealed, delivered. Second place is yours, baby boy. That's why you should have voted his ass out #BB28
A month ago I got my son super excited to get soft serve from McDonald’s. I hadn’t been in ages. We rode the bike over on a hot day, walk in and see a deserted restaurant. I walk up to the counter and see nobody. Confused I say “hello” out loud. The two men come up clearly bothered i interrupted their conversation asking what I wanted.
I asked if I could order from them. The one guy points to the screen behind me. I turn around and start going through the menu. I look for ice cream. I try clicking on it, it won’t work.
I once again flag the guy down and he simply says “ice cream machine is broken.” I then ask how long it’ll be (assuming it’s short term). He responds, “it’s been broken a long time.” At this point my 4 yr old is begging me for the ice cream.
It was in that moment I got super sad. I grew up going to McDonald’s. As a kid of the 90s it was our Saturday hangout. It was the place we got ice cream after t-ball games. It was the place we stopped in on early morning road trips for egg McMuffins.
Was it the best food? To a 8 yr old whose taste buds were still forming, hell yes.
My son is almost 5 and been to McDonald’s maybe twice in his life. He will never have the nostalgia for that brand simply because McDonald’s failed to realize what they had when they had it and stripped it all down.
It’s too pricey, sterile, and at this point full of disappointment. This tweet below says it so well.
@McDonalds you need to stop listening to shareholders and start listening to parents.
I’d love to see Drew say that to my face lol if being a puppet and getting manipulated to play two people’s game the whole season is doing something I’d rather be “furniture” than spineless kid goodluck to ya!
This is the interview Trump’s FCC doesn’t want you to see.
We’re not just going up against the most corrupt politician in Texas.
We’re going up against this entire corrupt system.
Dee- These little fuckers think that they can make it until the end. Mosh Pit meeting is going to be a blast and I hope that you guys have fun watching #BB28
I think $SOFI delivered an incredible quarter and I put my analysis in this article below. Congrats @anthonynoto as $SOFI is becoming a true compounder across the board.
$SOFI - SoFi Technologies Q2: The Everything App Inflection Just Showed Up In The Numbers https://t.co/kVJDuw9mT3
EXCLUSIVE: Angela Murray has officially moved into the #BB28 house and will be competing this summer alongside two #Survivor players (one of them being Rick Devens, via @DaltonRoss).
Details: https://t.co/1tHtIuoCO3
Every American should be outraged by what Trump has done to our nation's 250th birthday celebration. What should have been a once-in-a-generation moment to unite the country has been turned into another vehicle for division, propaganda, and political gain.
We uncovered how he hijacked America 250 – watch to see how.