I just published my article on how hyperscalers like $AMZN, $MSFT, and $GOOGL will benefit in the token optimization era and why I believe the companies will re-rate much higher.
https://t.co/CXiRbVWckW
Ben Horowitz on the All-In Pod just said that he spoke to the $AMZN CEO a few days ago, who told him that they are SOLD OUT of compute past 2028 (maybe end of 2028).
My comment is that you will continue to see hyperscaler revenue accelerate not just from more data centers comin
Alex (@alexandr_wang), please, on behalf of all $META shareholders, pull Susan aside and tell her that if she is thinking about an equity raise, it is not a good idea in this environment.
It could be really, really bad in financial terms. Thx.
$NVDA is becoming more dependent on neoclouds and other companies outside of the Hyperscalers ($AMZN, $META, $GOOGL, $MSFT).
In the recent BG2 pod, $NVDA's Jensen confirmed that they have reclassified $SPCX from the AI Clouds, Industrials, and Enterprise Revenue (ACIE)
If lending conditions get worse the AI buildout slows down, some neoclouds might get in trouble as they need external capital to build, semis demand slows down in the short-term because of the bottleneck becoming capital, but for hyperscalers ( $AMZN, $MSFT, $GOOGL )
The market has been rotating out of semis and into the data center/hyperscaler companies & the application layer ($MSFT, $GOOGL, $AMZN, $META, etc.).
I expect this to continue.
I have to test the model out, but $META being at the frontier of the AI race changes a lot of things for the industry and for $META's valuation.
All that negative value derived from "excess CapEx spending and infra capacity" turns from negative to positive with the flip
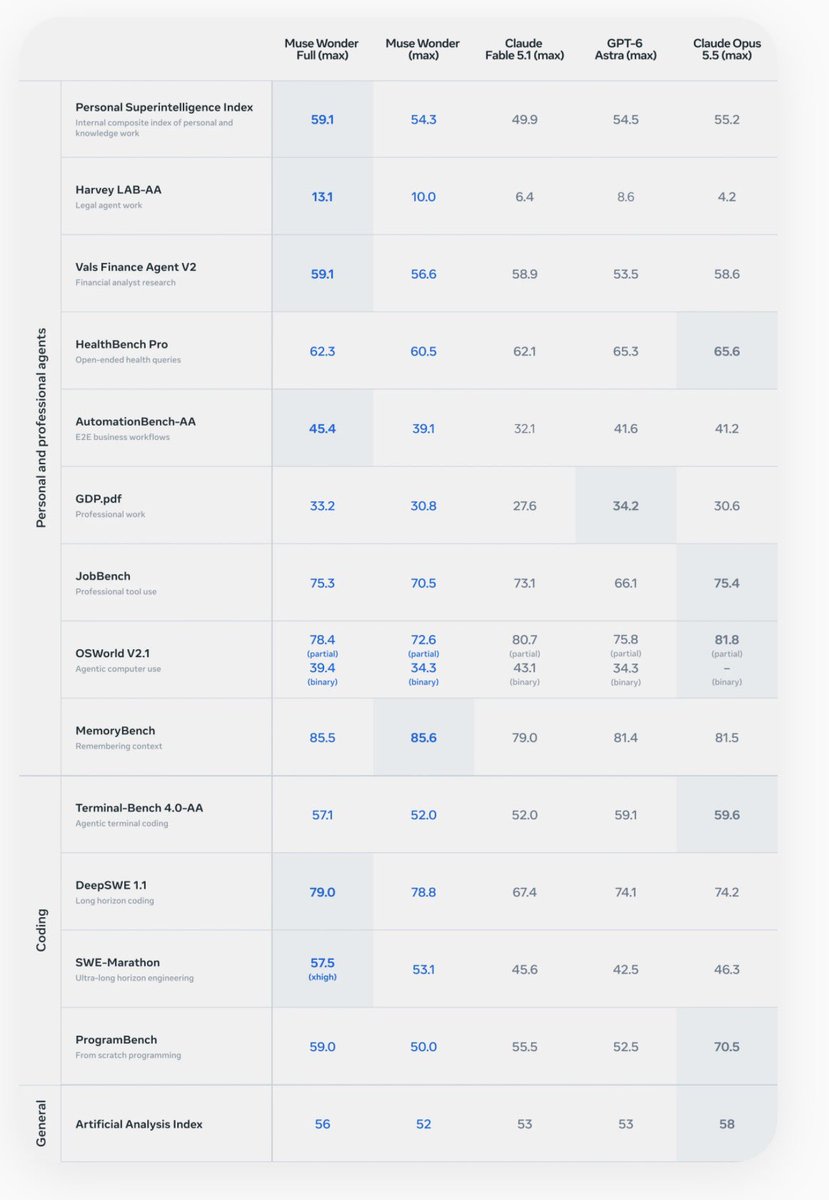
Wow, $META just dropped a bomb! New model called Wonder, with active focus.
Focused on knowledge work, health, finance, legal (special data set)
Benchmarks look strong with frontier.
Wow, $META just dropped a bomb! New model called Wonder, with active focus.
Focused on knowledge work, health, finance, legal (special data set)
Benchmarks look strong with frontier.
Wow, $META has truly an open road with personal AI agents.
$GOOGL just announced a Gemini agent, but again, it focuses more on B2B than B2C and is initially available only in the $GOOGL AI Pro and Ultra plans.
The big guys have all fired their shots now, and it seems that
As business models at $AMZN, $MSFT, $GOOGL, and $META become more compute-intensive in the AI world, they're also becoming less headcount-intensive.
You can see the trend of higher revenue per headcount, which has been happening consistently since 2022.
$META would not be lowering spent on Claude if their internal models woudn’t be good. Zuck understands and cares too much about quality and the importance of it when it comes to product dev.
Watermelon incoming.
META AND MICROSOFT WORK TO WEAN STAFF OFF ANTHROPIC’S CLAUDE - THE INFORMATION
MICROSOFT CUT INTERNAL CLAUDE SPENDING LEVEL BY OVER A THIRD - THE INFORMATION
What a lot of folks don’t understand is that the more users $META Muse is getting at the scale it is already (+5M downloads) the more feedback it is gathering to improve the product the bigger the moat is.
The first mover advantage could be significant here, since coding (makin
$META trades at a fwd P/E of 22.7 yet:
- The core business is growing 30% & becoming more valuable in the AI world (reaching a human via ads will become a premium),
- $META has a strong head start and lead in the personal AI agent race with Muse (Muse growing at a pace as one
I published my article on the Agent Economy and how I think personal agents like $META Muse will reshape industries and business models.
1. Explaining how AI agents browse and connect to the world
2. Revenue layers at risk (friction, attention, search https://t.co/AlQQTNxC3S…
Wow, OpenAI making dots the $META Muse competitor only available to Pro plans not Plus, Go or Free and looking at the features it doesn’t look anything better than Muse.
$META really has the road open now to take the consumer AI agent market.
It does seem like OpenAI is out of compute. I wonder how they will be able to provide compute for both a personal AI assistant & support their work use cases.
We will see what they release today, but the $META Muse competitor doesn't seem like it will be free or scalable with this compute.
Interview with a current $AMZN AWS employee on AI model usage, switching costs, and when to use what model:
1. He explains the pros and cons of using models via a service like Bedrock. The pros are that it's already native in your AWS, your data residency is all good there,