New chapter for this account.
I’m a Chartered Accountant and a long-term investor.
From now on, I’ll share what I learn about:
📊 Indian stocks & businesses
🚀 IPO analysis
💰 Valuation
🧠 Investor psychology
📚 Financial statements
No “sure-shot” tips.
Just numbers, research, mistakes, lessons and the mindset needed to survive the market.
Let’s learn & invest better together.
₹29,613 crore.
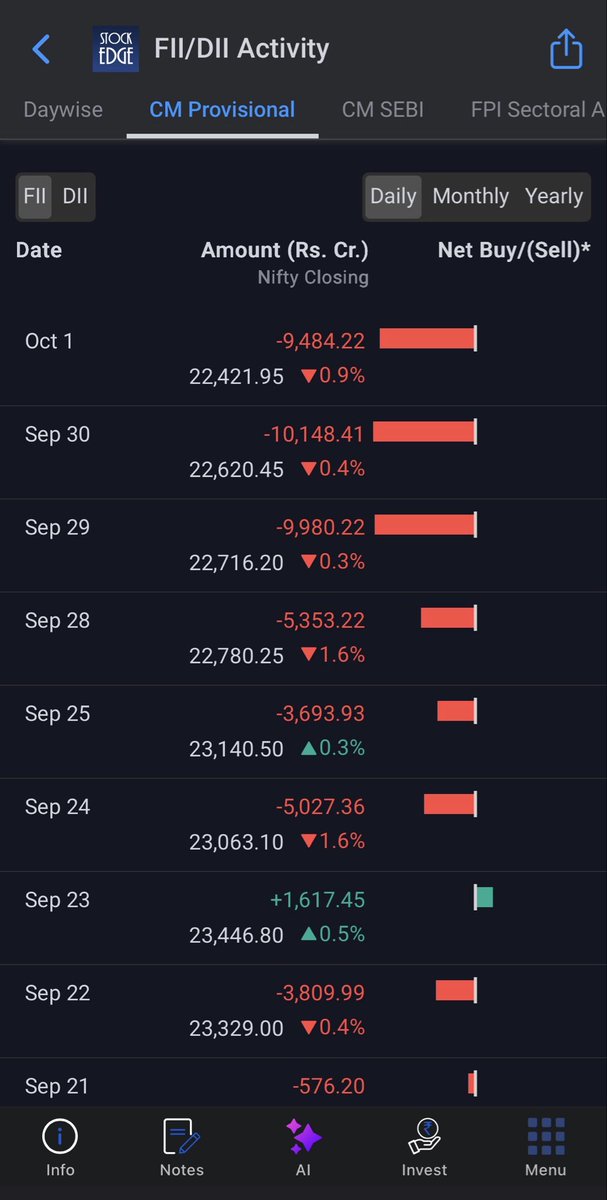
That’s the FII selling in just the last 3 sessions.
Sep 29: −₹9,980 Cr
Sep 30: −₹10,148 Cr
Oct 1: −₹9,484 Cr
Yet Nifty is down only 1.3% from Sep 29.
Domestic money is absorbing the supply.
The question is not if. It is for how long.
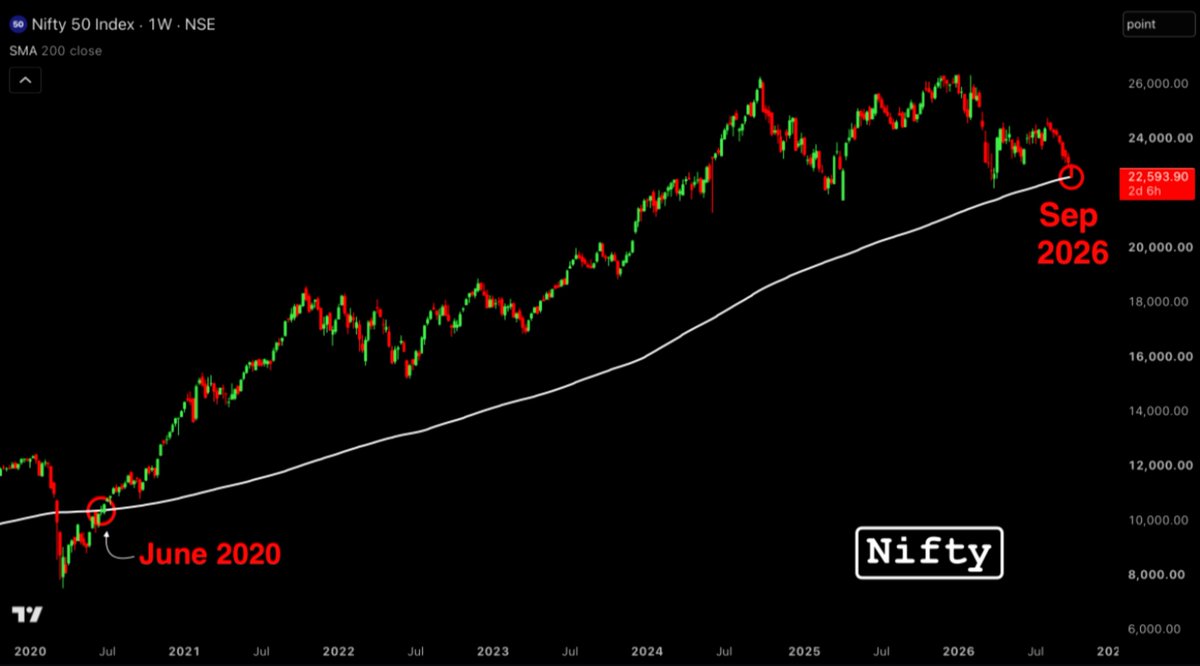
Nifty is heading for its 8th red week in a row.
Longest weekly losing streak in 25 years.
But the fall so far is only −6%.
2001: −20.5%
2008: −22.1%
Duration looks scary.
Damage is not the same.
Is this just a long correction, or something bigger?
@connectgurmeet If we over tax FPI, we aren’t just hurting market sentiment, we are actively pressuring the INR and long term corporate valuation. Needs urgent attention.
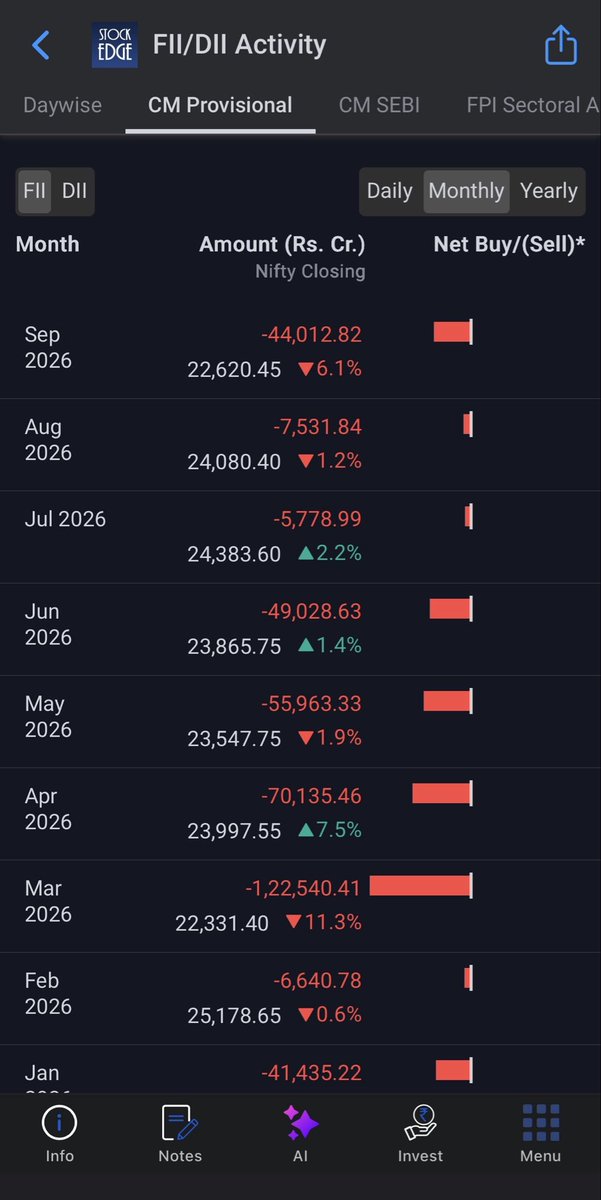
₹44,000+ crore.
That’s roughly how much FII sold in Indian equities in September.
Nifty: −6%
IT: −11%
Midcaps: −7.6%
DII absorbed most of it.
So the market didn’t collapse.
The real question isn’t why FII sold.
It’s:
How long can domestic money keep supporting Indian equities without foreign confirmation?
@sourabhsiso19 Great breakdown! Top line growth number is great but for a jewellery business, working capital and inventory turnover will be the real test.
7. Disclaimer:
I am not a SEBI registered analyst. This thread is purely for educational purposes based on publicly available RHP data and is NOT investment advice.
Nityas Gems IPO.
Price alone doesn’t tell you the business.
Went through the RHP.
LGD jewellery. Fast growth. Profitable in FY26.
But cash is stuck in working capital.
Here’s the RHP breakdown 🧵👇
6. What the RHP leaves you with
Fast LGD growth and rising margins, but profits sit in inventory and receivables. IPO funds WC, not plants.
What is your take on Nityas Gems at 19.4x Post-IPO P/E?
5. Key Risk Factors stated in the RHP.
• No long term contracts. Order driven B2B
• D2C is 4% of sales
• 5 states = 85% of revenue
• Related-party txn: 33% of FY26 sales
• WC days: 47 → 135
• LGD price deflation is an industry risk the RHP itself flags
1. First, the business
Surat maker of lab-grown diamond studded gold jewellery
FY26 mix:
• B2B 95.6% (GIVA, Palmonas,etc)
• D2C (Ayaani) 4.3%
Top 10 clients = 55% of sales. D2C started only after the Jul’25 Ayaani buy.
Gujarat + Karnataka + MH + Telangana + TN = 85% of sales.
FII short positions are hitting a record high.
But a high short position doesn’t automatically mean “market crash.”
It can be hedging.
It can be a trade.
It can be positioning.
Don’t confuse positioning with prediction.
The better question:
What happens when that positioning starts reversing?
7. Disclaimer:
I am not a SEBI registered analyst. This thread is purely for educational purposes based on publicly available RHP data and is NOT investment advice.
SRIT India IPO.
Price alone doesn’t tell you the business.
Went through the RHP.
27-year-old IT/ITeS company. ₹1,182.8 Cr FY26 order book.
Growth is strong. Government + customer concentration is the catch.
RHP breakdown 🧵👇