$CPS
Delivered Good Quarter, but not an extraordinary, but if, Zoom out
1. FCF swung +ve
2. Net new business stay solid
3. Still held the mid-point 280M guidance
4. Restructuring costs( Q2-17.1, YTD 21.7), made it look ugly combined with temporary non-controlable cost pressure.
$CPS Results are out.
Good quarter in overall,
~ Keeps the recovery intact & improves the cash story despite inflationary pressure.
Looking forward to listen to "CC" tomorrow.
Investors | Cooper Standard https://t.co/1GAfzyiafU
$CPS Results are out.
Good quarter in overall,
~ Keeps the recovery intact & improves the cash story despite inflationary pressure.
Looking forward to listen to "CC" tomorrow.
Investors | Cooper Standard https://t.co/1GAfzyiafU
@zacktanzx Exactly 💯, need to look out for Q3 and Q4 wholesale..
That's what Bracken was trying to say, most of the fleet flat to +ve, but stubborn stores need some attention.
I tried to put it here, see below
https://t.co/a5CE2m5Ypy
Stubborn stores ??
1. Management will address it by using DTC to bring heat within these stores with product mix/ premium new styles to attract crowd.
Such as Authentic, Slip-Ons, & Souvenir Asphalt collection
OR
2. Further Channel rationalization ( closed or re-located )
That's how management is expecting
~ Q2 to be down again(8%-9%), &
~ (-2% or better) in 2nd half of the year.
&
~ Then to grow in both DTC and Wholesale by the time, we exit this fiscal year.
$VFC Q1FY27 Earnings Update
1. TNF countinue to perform +6%or +4% C$
America Up 8%, Both Channels in growth
2. Timberland +4%,or +3% C$
America Up 11%, Growth in DTC & Wholesale
3. Altra continues to show growth
4. Vans(-8% or -9% C$),with growth in DTC,but decline in wholesale
Stubborn stores ??
1. Management will address it by using DTC to bring heat within these stores with product mix/ premium new styles to attract crowd.
Such as Authentic, Slip-Ons, & Souvenir Asphalt collection
OR
2. Further Channel rationalization ( closed or re-located )
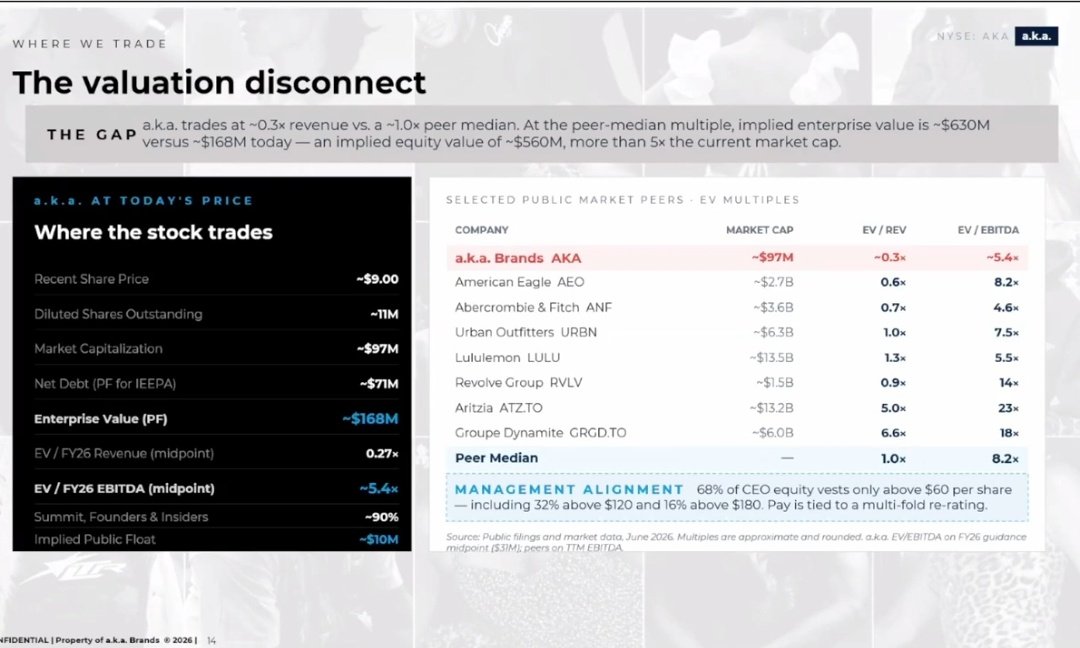
$AKA
Great event...
Growing 3% - 5%,
GM expansion toward 60%,
Tariff Refunds and debt paydown,
Further Store Expansion,
Mgmt. addresses stock Re-Rating,
What's the end game looks like?
Seems like, Low float is a drag on Re-Rating.
@kingdomcapadv
If you're in Vegas for Planet Microcap, let me know if you want to join for an event at $AKA's Culture Kings store tomorrow night - got a few spots left
@zacktanzx Yes sir, 💯
When, we look at "VANS" vs "NKE", "LULU" vs "ALO & VUORI",
We can notice some key points..
1) Consumer is holding/resilient
2) Customer is ready to pay for "New products" (even, when the price is higher)
3) Customer is not buying outdated products (NKE, & LULU)
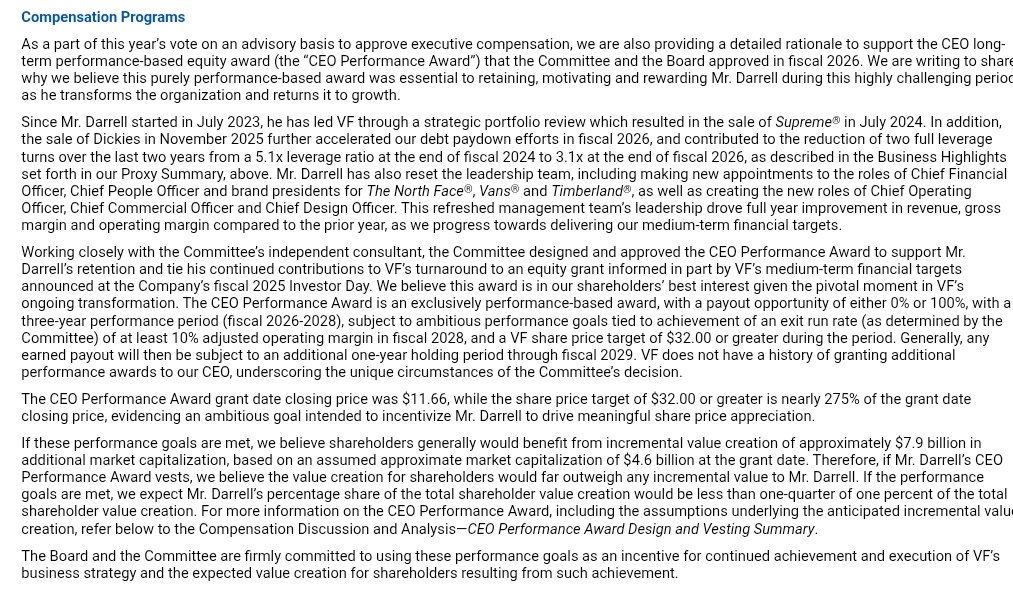
$VFC
Reporting Earnings Tmrw.
*Will beat on Top and Bottom.
*Per Q3, 75%+ portfolio is in Growth Mode..
*Focus will be "VANS"
*"VANS" is the only drag on Stock..
The moment market smelled recovery, stock will fly...
*Upcoming year bringing us a lot of brand heat.
Bullish setup
A year back, I figured Q4 would be the turning point for $VFC, especially "VANS"-fresh products with better margins & more buzz. 75% of the business is in growth per Q3, & with "VANS" building momentum with cool/newness in products, will further set the stage.
Great year AHEAD🔥
@RecurveCapital Help me understand one thing, sir.
If we take an average
10 DCs=45-50 MW , and expecting 300M-350M
Basically 6M-7M per MW vs historically expected 14M-17M (or avg. 1.5B for all 24 DCs)
I get it, lots of factors to consider, but <10M, when DC demand is through the roof. Why?
$MU hit $817+ today..
I was bullish on Micron since 2022, and bought it at $55.
But Big Question?
Have 3 oligopolies (Represents 90%+ mkt share in DRAM/NAND) learned any lessons from their past Boom/Bust cycles.
I don't know,
Let's wait and see 👀
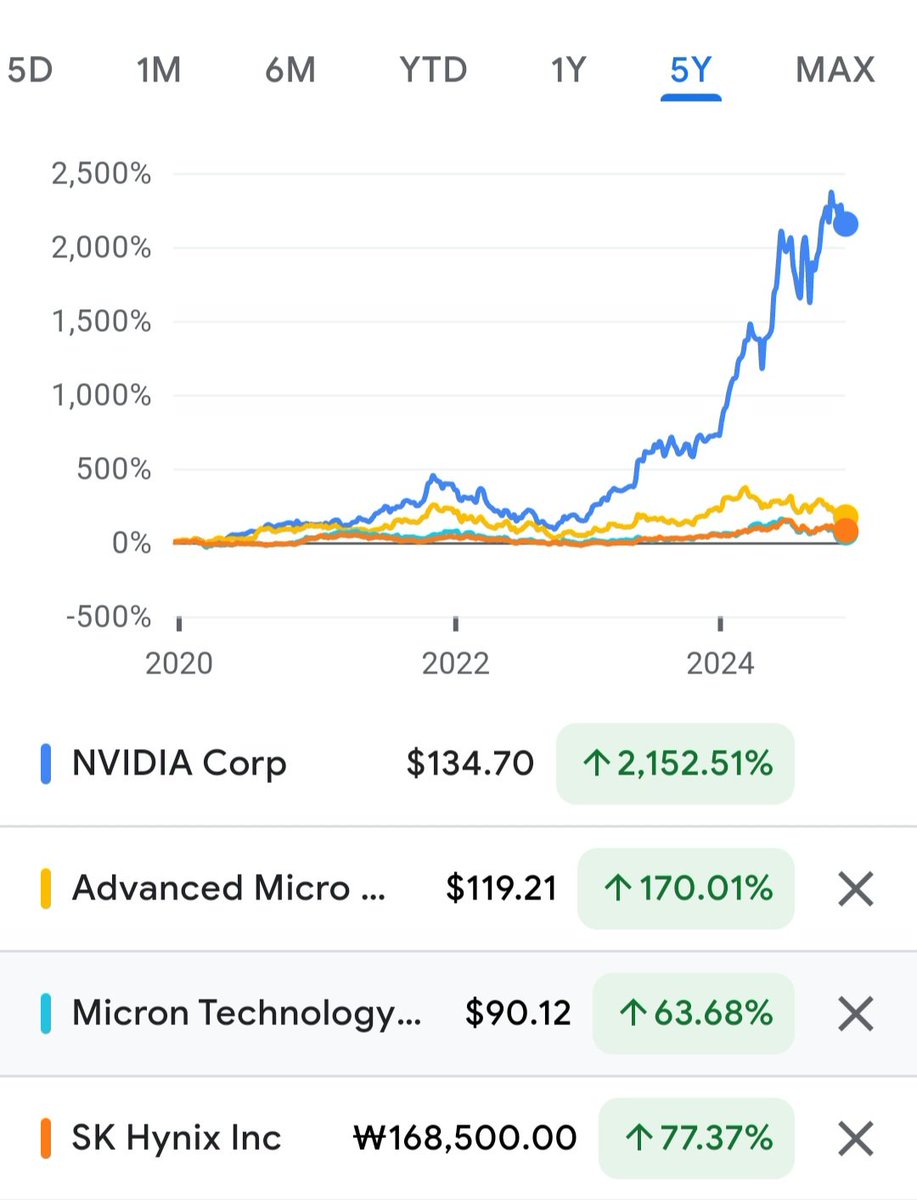
Market is pricing $MU like it has peaked its earnings just like every cycle, but it seems pretty undervalued if we compare them to others. Market hates MU, whereas valuations are tripling every year for Nvda. MU seems like a long and promising bet.
Morning thought 💭
Overall, it was a great conference call, provides us a lot of insights into future.
Management is hitting on all cylinders & ready to announce guidance raise in Q2,
Execution has been exceptional.
Congrats Cooper Standard
Bullish 🔥
$cps Earnings call takeout
*Margin Expansion ✔️
(12% GM, UP 40 basis points)
Margins will countinue to expand as older businesses are replaced with newer businesses.
Chairman Edwards said, "We expect our return on invested capital to be well over 20% at the end of our 2028.
$cps Earnings Focus
*Focused on margin expansion with stable volume (10%+)
*New Business Wins (Higher CPV)
*Business in China picking up(CAGR of 15%+ through 28)
*Production Trends (+/-)
*Lost Production Recovery (from late '25)
*Oil Impact (i.e. Raw material cost and offsets
*Oil Impact
we are in excess of about 70% covered on contractual indexes with our customers or otherwise negotiate on a regular cadence—every quarter or every six months—with customers to claw that back. So we think any increases will be adequately addressed.