📣 User protection & fund security are our top priorities! 🛡️
🚨Since Jan 2023, we've been actively speaking out against @zebpay due to concerns raised by our users.
We've been flooded with DMs, messages & emails from users sharing their issues related to @zebpay@zebpaysupport should address these user problems promptly and prioritize their resolution!
For more info, watch this 👇
https://t.co/TzGb3h0Hn8
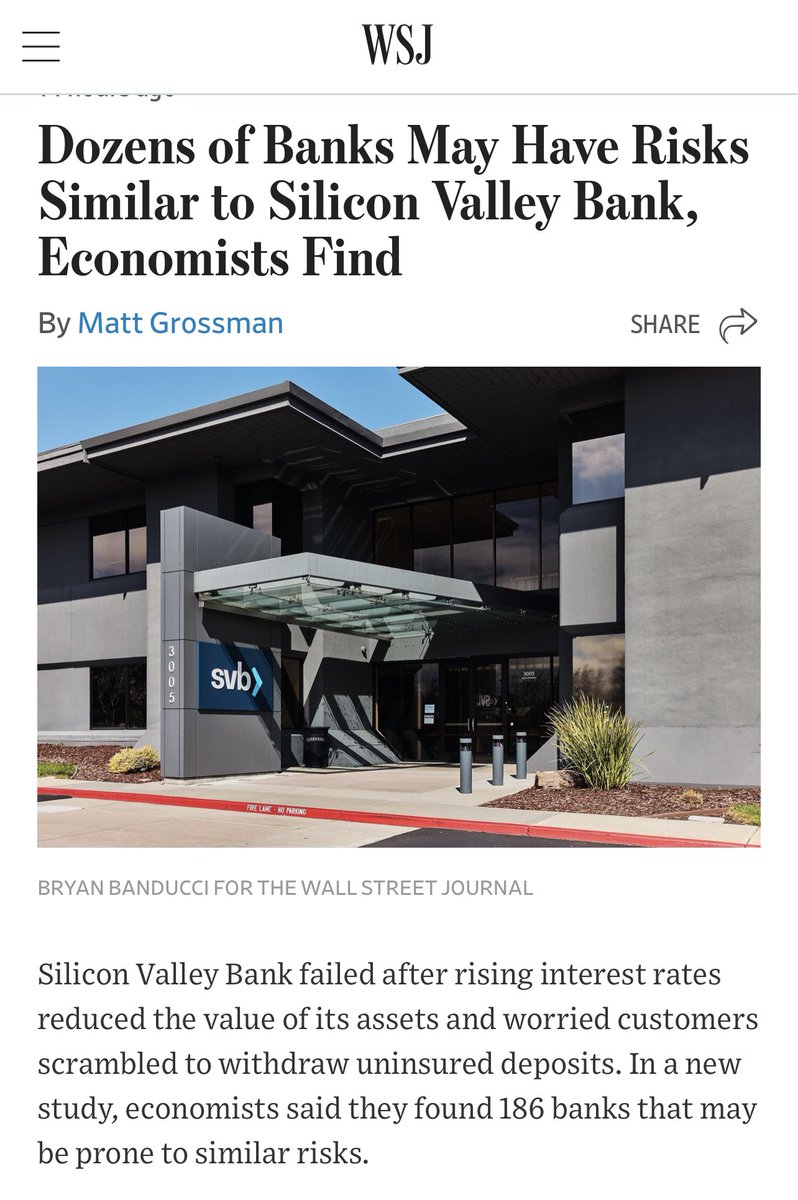
As this week progresses, just remember that the Fed *knew* back in September that its rate hikes had silently killed 300+ community banks.
They just didn’t notify depositors. Preferring instead to let everyone find out in chaotic bank runs.
https://t.co/i3xMQGss8z
Dalio predicted the Fed would monetize the debt.
But not how or when.
It's now.
They're doing it in the most chaotic way possible.
100+ insolvent banks get printed money.
Who gets paid? First come, first served.
But who keeps value? Those in Bitcoin.
https://t.co/GX2lFWEAGo
I’m joining a Twitter space now to talk about the rationale.
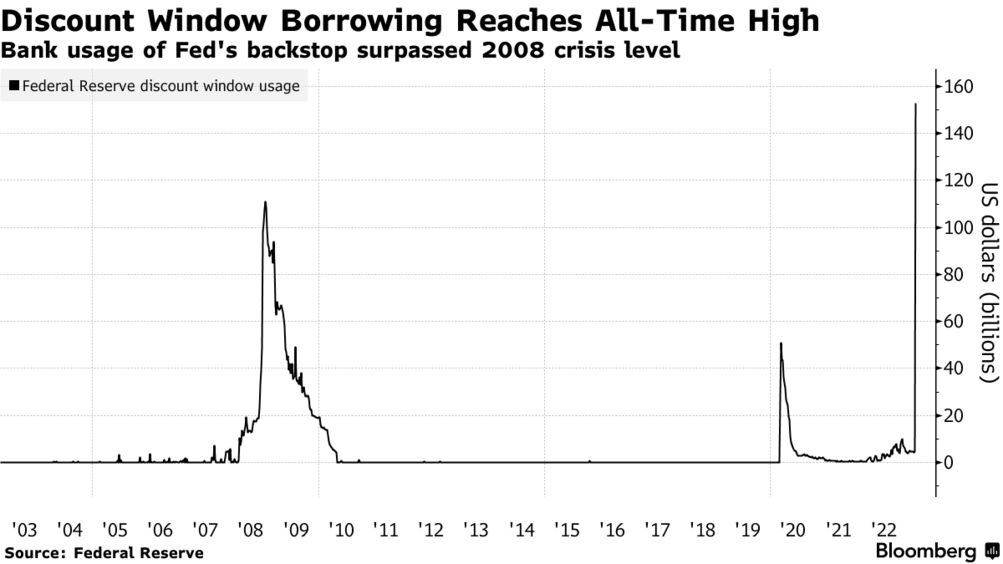
In short, the Fed has chosen to monetize the debt in the messiest way possible: an orgy of money printing and bank runs. $150B has already hit the banks and more is on the way.
My bet is a way to ring the fire alarm and help you get to the exit in time: Bitcoin. The only global safe haven.
They're finally admitting it's a banking crisis.
That it was caused by Fed rate hikes, not tech.[1]
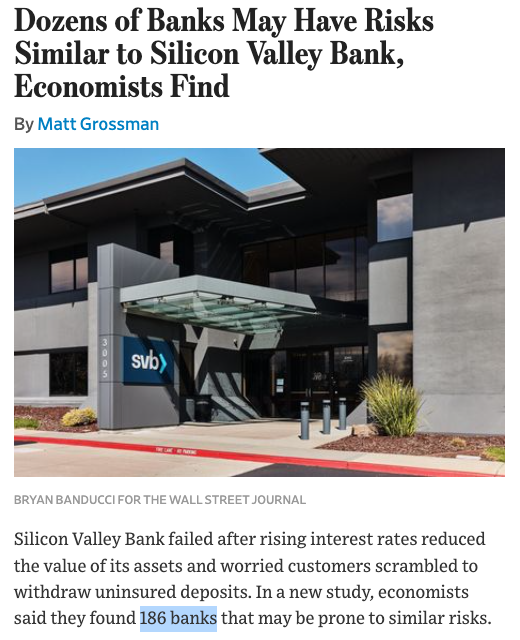
That there are 100+ insolvent banks, not one.[2]
That this is already beyond 2008 in key ways.[3]
And that printing is going literally vertical.[4]
This week promises to be crazy.
[1]: https://t.co/hD6HbzmLpg
[2]: https://t.co/x6TKfmUlHl
[3]: https://t.co/WhSgF9fRHL
[4]: https://t.co/XJ96585HuX
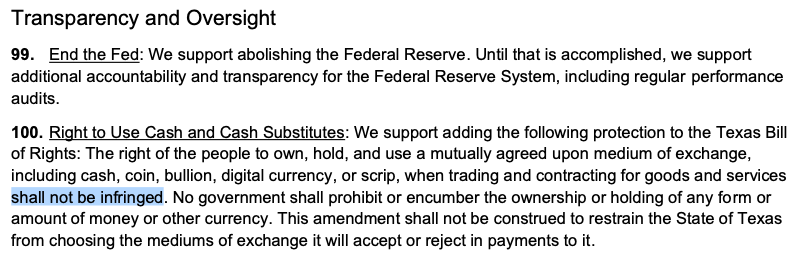
The right to buy, sell, send, and receive Bitcoin shall not be infringed.
This is already part of Texas GOP's official platform.
Other states can copy this language.
Along with Ending the Fed.
They're all going to need it soon.
https://t.co/vK0F7elb5s
The can can't be kicked any longer.
This crisis won't be like the others.
BTFP was $25B on Mar 12.
Then suddenly $2T on Mar 16.
In reality it's unlimited.
Holding assets in dollars anywhere means devaluation.
But Bitcoin is a global safe haven.
#Bitsignal
The Fed made 100+ banks insolvent.[1]
Monday will see huge withdrawals.
But moving to big banks is a trap.
Trillions will be printed, and you will be diluted.
You need an asset that can't be seized.
Bitcoin is the only global safe haven.
#Bitsignal
[1]: https://t.co/UYC335FCYI
@IIICapital Read thread and references.
All the banks are insolvent.
Withdrawing to a G-SIB is a trap.
You’ll still get hit by devaluation.
The only true withdrawal is Bitcoin.
The exit from the fiat system.
PS: as I predicted, many more banks are now coming up dead. #Bitsignal
Here are the remaining references, as Twitter has a limit on the number of links in one post.
I am moving $2M into USDC for the bet. I will do it with Medlock and one other person, sufficient to prove the point. See my next tweet. Everyone else should just go buy Bitcoin, as it'll be much cheaper for you than locking one up for 90 days.
Terms of the bet: ideally someone can set up a smart contract where BTC is worth >$1M in 90 days, then I win. If it's worth less than $1M in 90 days, then the counterparty gets the $1M in USD.
HYPERBITCOINIZATION
We have to define hyperinflation in BTC vs USD terms because all other fiat currencies can and will be inflated away. That is hyperbitcoinization.
This is the moment that the world redenominates on Bitcoin as digital gold, returning to a model much like before the 20th century. What's going to happen is that individuals, then firms, then large funds will buy Bitcoin. Then sovereigns like El Salvador (@nayibbukele) and tiny crypto friendly countries.
The big move will be when a US state like Florida or Texas, or a "normal" country like Estonia, Singapore, Saudi, Hungary, or UAE buys BItcoin. And when @narendramodi tells India's central bank to buy Bitcoin, even as a hedge, it's over.
Why will it be so fast? Well, hyperinflation happens fast. We've seen digital pandemics (COVID), digital riots (BLM), and digital bank runs (SVB). Everything will happen very fast once people check what I'm saying and see that the Federal Reserve has lied about how much money there is in the banks. All dollar holders get destroyed.
The thing is, people are still tuned to an analog world where things get gradually worse rather than all at once. But there isn't much forewarning for a digital event — it's 1 and then it's 0. Just like the bank runs, except this is the central bank.
There are however two sources of forewarning. First is the chart of the long-term depreciation of USD vs BTC, from less than $1 USD per BTC to $25k USD per BTC. Much of the smart money has been voting against the dollar since the financial crisis. The end is a digital drop off a cliff, almost invisible on the chart — but highly visible in the world.
This tweet is the second forewarning. It'll be ignored and mocked by people who still trust the US establishment, even after the last few years. Who can't imagine that the US banks and media could be lying to them to this extent.
But they are. Just as they did in 2008, and over the last ten years. The digital devaluation of the dollar is coming and it's going to be intense.
[9]: Patient on hikes Nov 3 2021: https://t.co/EQl3oiRZxS
[10]: Renominated Nov 22 2021: https://t.co/nFChGDIeKZ
[11]: Yellen admits not a tech issue: https://t.co/isHN3j3P3D
[12]: FDIC admits rate rises rekt banks: https://t.co/eIbCwBl2kr
[13]: Presidents don't like hikes: https://t.co/wnEZOVQz97
[14]: https://t.co/GqzU0Q1W2A
Just as in 2008, the bankers lied.
This time, the central bankers, the banks, and the bank regulators have lied to all dollar holders and depositors.
This isn't your typical fractional reserve situation. The problem is that there isn't enough in the banks on a mark-to-market basis to cover withdrawals. They knew this through all of last year, and communicated it internally in their coded language.
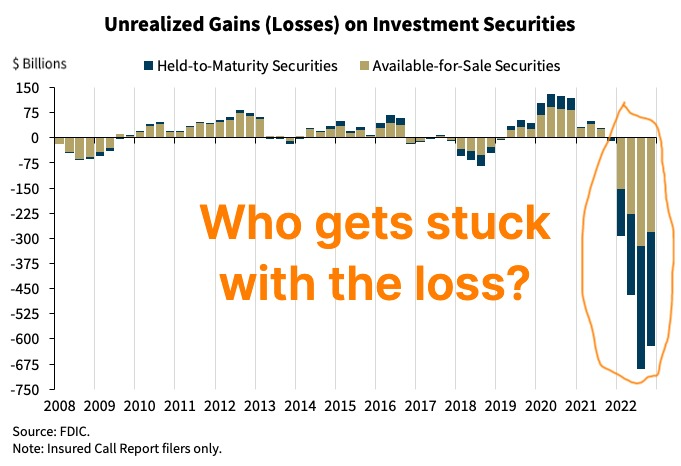
It's obvious from the graphs (see below). The central banks, the banks, and the banking regulators all knew a huge crash was coming — the phrase is "unrealized losses" [1,2,3,4,5]. But they never notified you, the depositor.
Instead the regulators allowed banks to hide their literal insolvency in footnotes[6], until one guy figured it out[7].
It's Uncle Sam Bankman Fried. Just like SBF used your deposits to buy shitcoins, using accounting tricks to fool himself and others into using the money, so too did the banks.
They all used the deposits to buy the ultimate shitcoin: long-dated US Treasuries. And they all got rekt at the same time, in the same way, because they bought the same asset from the same vendor who devalued it at the same time: the Fed.
Specifically, as NYT admitted, banks "binged" on enormous amounts of Treasuries and other long-term bonds in 2021 when the flood of printed money cut off their typical demand for loans, and because they thought the Fed would keep interest rates low forever.[8].
And they had good reason to believe this. Powell said he'd be "patient" on rate hikes as late as Nov 3 2021[9]. Then he got renominated on Nov 22 2021[10], and hiked rates much faster than anyone had expected — which even Yellen[11] and the FDIC[12] admit caused the current banking crisis.
Why did Powell delay? Probably for political reasons. Presidents don't like rate hikes[13], especially running into the election year of 2022. And Powell thought he could wait and just be like Paul Volcker[14], who was "firm" and then defeated inflation.
But the world isn't an 80s rerun. Hiking from ten years of near zero interest rates in the 2010s was a surprise attack on every dollar holder. Economics isn't politics - the kind of insane flipflops you see in politics don't work when there are actual contracts involved.
So anyone who bet on long-term Treasuries got killed in 2021. And now, anyone who bets on short-term Treasuries is going to get killed in 2023. The absolute worse place you can be is to have large amounts of assets locked up in three month treasury bills. The ~5% interest rate offered by big banks (G-SIBs) is a trap. Most fiat bank accounts are now a trap, for those countries whose central bankers followed the Fed.
Check my references, I've provided quite a few.
If you trust US bankers and US media, ignore me.
Otherwise buy Bitcoin and get your coins off exchanges.
#Bitsignal
[1]: Fed, Sept 22: https://t.co/U4xeA0TAq9
[2]: FDIC Nov 22: https://t.co/NPj6jde3uG
[3]: FDIC Mar 6 23: https://t.co/1cctxQ27KI
[4]: Fed Feb 1 23: https://t.co/knQzUIKJI2
[5]: Bank CPAs, April 22: https://t.co/OlEnfFqb1N
[6]: Insolvency in a footnote: https://t.co/7b8oCBuFpp
[7]: Discovered online: https://t.co/oaVtf9f57Y
[8]: Banks bingeing on bonds, but not because they want to Aug 25 2021: https://t.co/OTfWwVwIqK
The record shows that the entire US banking system — the Fed, the banks, and the bank regulators — knew by 2022 that they had lost the money of many millions of depositors.[1,2,3,4]
Banks tried hiding the losses via hold-to-maturity accounting tricks (should be called hide-to-maturity).[5] And regulators allowed them to bury the fact of their literal insolvency in footnotes[6].
But this just deferred the judgment for a bit. In a sense, the entire bill for many years of printing was coming due all at once. Hundreds of billions of dollars in losses for the central bank, the commercial banks — all of it had to be imposed on someone.
But who? Who would be both *saddled* with billions of losses and *blamed* for billions in losses?
Well, who's the outgroup to the US establishment? The tech community! We're largely immigrants. We're not historically political. You hate us. We know that.
So you come up with the fiction that some H1B programmers are responsible for diligencing their employer's bank statements but poor ol' Jerome Powell is responsible for nothing at all.
Unfortunately for you, the record shows that the Fed and FDIC knew that hundreds of banks across the country were insolvent, and they didn't notify depositors.
Still time to send a push notification telling them that the US banking system lost their money! Though of course you're going to print it instead with BTFP. Hope that works out for you.
[1]: Fed Sept 22: https://t.co/U4xeA0TAq9
[2]: FDIC Nov 22: https://t.co/Yx90LqrCdm
[3]: Fed Feb 23 2023: https://t.co/knQzUIKJI2
[4]: FDIC March 6, 2023: https://t.co/rzCeGKd7Ys
[5]: https://t.co/OlEnfFqb1N
[6]: https://t.co/7b8oCBuFpp
It's the digital equivalent of fine print. Public without actually being disclosed.
Do you think the depositors of those community banks know that the Fed destroyed their savings?