@stwboerse Zu der Diskussion hier noch ein Hinweis: nachdem jetzt die Software Kurse enorm gesunken sind wird sich das Thema vermutlich verschärfen. Es werden mehr Aktien für die SBC notwendig für gleichbleibenden Nutzen der MA. Da unterscheiden sich die Alternativen drastisch. CSU > NOW
Treasury buybacks are accelerating:
The US Treasury has bought back a record $138 billion in bonds YTD.
This significantly surpasses the $79 billion repurchased during the entire 2024.
This buyback program aims to boost liquidity and manage cash, as deficit spending continues to surge.
In July, the Treasury said it would buy back 10- to 30-year Treasuries TWICE as often.
As a result, Bloomberg’s measure of Treasury liquidity has materially improved over the last year.
The world’s largest bond market can no longer function without intervention.
@margsrethe74273@SBetschinger Es sei denn es gibt nichts zu verteilen. Dann könnte schon wichtig sein, wie man dahin kommt etwas zum Verteilen zu finden. Und vielleicht ergibt es Sinn nach einem Schlüssel zu verteilen, der sich am Beitrag zum Erfolg orientiert. Dann könnte es stetig was zu verteilen geben.
BREAKING: In shocking footage of Trump in 2020 that is now going viral, Trump says it’s against the law for a president to call in the National Guard on his own: “We can't call in the National Guard unless we're requested by a governor.” MAGA = 🤡.
André Agassi trifft den ukrainischen Ex-Tennisspieler Andrei Medvedev, den er 1999 im Finale von Paris geschlagen hatte. Statt gleich über dieses Spiel zu sprechen, dass ihm den Karriere Grand Slam brachte, beginnt Agassi so! 👇
Großen Respekt!
DEAN: What's the tariff on bananas?
LUTNICK: Generally 10%
DEAN: Walmart has already increased the cost of bananas by 8%
LUTNICK: If you build in America, there is no tariff
DEAN: We cannot build bananas in America
MY OPEN LETTER TO PRESIDENT TRUMP
The frustrating part is that I was on board for a reset. Truly. I’ve said it publicly. I’ve written about it in this very feed. I understood the need for a detox. For decades, the U.S. economy played the part of the rich guy at the table -- picking up the check for a global order that no longer worked in our favor. We hollowed out our industrial base. We enabled unfair trade imbalances under the illusion of diplomacy. We subsidized demand for cheap imports while outsourcing the hard questions about how our domestic workforce would adapt.
Eventually, that had to stop. It was unsustainable -- financially, politically, and morally. We couldn’t keep pretending that a consumption-led economy held together by zero-interest rates and global fragility was a long-term solution. I wanted a rebalancing. I welcomed the idea of a harder, smarter America-first policy that pushed for fair treatment, reciprocal agreements, and a real industrial strategy rooted in technological superiority, national security, and capital formation. That would’ve been leadership.
But that’s not what this is.
What you’ve rolled out isn’t detox -- it’s whiplash. This isn’t strategic decoupling. It’s scattershot retaliation dressed up as reform. There’s no roadmap. No operational playbook. No clear articulation of where this ends or what the metrics of success even are. It’s not an attempt to responsibly unwind America’s role as the global shock absorber -- it’s a brute-force attempt to disorder the existing system with no viable alternative in place.
You can’t replace a fragile supply chain with chaos and call it resilience. You can’t build American industry by torching the scaffolding that underpins capital flows, labor mobility, and global coordination -- especially when the U.S. itself no longer has the domestic capacity to meet its own industrial needs. You talk about bringing jobs home, but the U.S. doesn’t have the labor force, permitting structure, or wage flexibility to stand up full-scale manufacturing at speed. And now -- after years of deportation policies and underinvestment in vocational training -- you’ve made the labor gap even wider.
Capital isn’t going to rush to fill that void just because you raised tariffs. It’s going to wait. It’s going to sit on the sidelines and preserve optionality. Because right now, no CEO can confidently model a five-year capex plan. No board can greenlight supply chain onshoring when they don’t know whether a tariff rate will double next quarter based on your Twitter account or some arbitrary trade deficit formula.
That’s the issue. This wasn’t rolled out as part of a comprehensive American renewal strategy. It wasn’t coordinated with the Fed. It wasn’t communicated clearly to Treasury. It wasn’t backed by a labor reskilling program or any form of public-private manufacturing incentive beyond empty slogans. It was dropped like a bomb -- seemingly designed more to shock than to build.
And in the absence of credible structure, capital is retreating -- not realigning.
I was ready to endure the pain of a thoughtful, structured reset. Most long-term investors were. We’ve lived through tightening cycles. We understood that globalization, as it stood, had reached a breaking point. But this isn’t a correction of imbalances. This is a rupture without scaffolding.
What you’ve created isn’t reindustrialization. It’s an intentional sabotage of capital planning. No executive is going to build a factory with four-year political horizon risk, a floating tariff regime, and no labor certainty. No investor is going to fund expansion in a market where the basic cost of imports can change weekly based on what country has a current account surplus that week. The system you’ve launched isn’t designed for certainty. It’s designed for control.
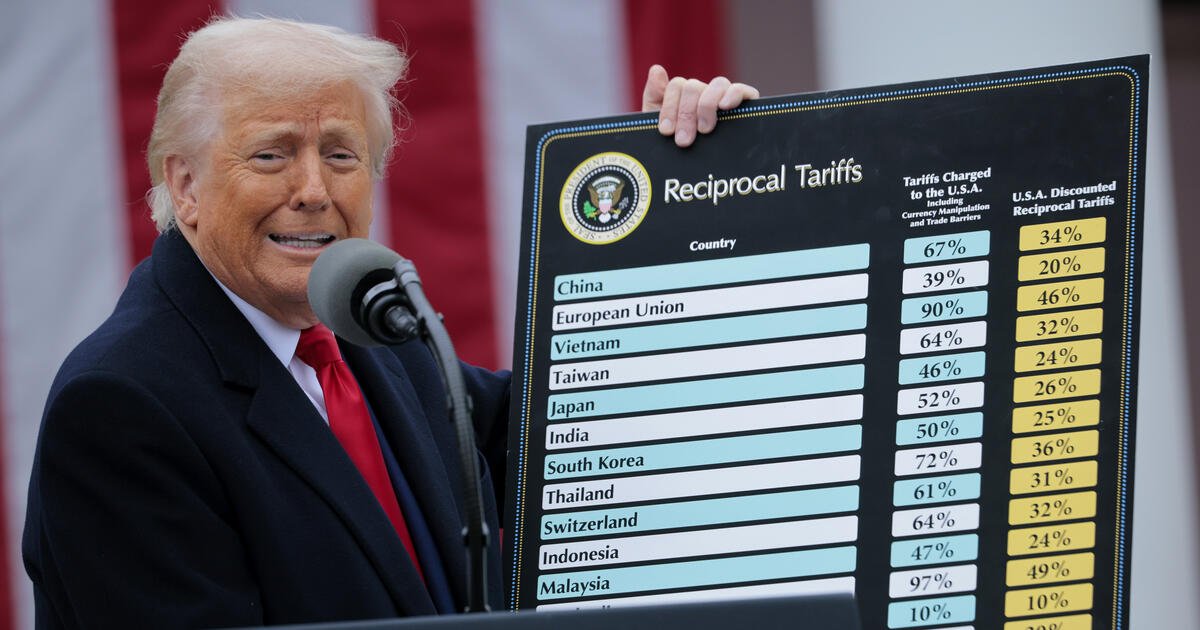
And the irony is -- we’re not even punishing bad actors. We’re punishing everyone. Allies. Poor countries. Longstanding partners. Israel gets slapped with 17% tariffs while dismantling their own to support American imports. Vietnam gets hit with 46% because it’s become too productive. Lesotho, one of the poorest countries on Earth, faces a 50% tariff because it doesn’t buy enough U.S. goods -- as if that were a sign of unfairness rather than poverty. It’s incoherent. It’s cruel. And it undermines any claim to moral high ground.
You say this is about protecting American workers. But no worker is helped by policy so erratic that no employer wants to hire. No consumer is helped when import costs rise and domestic capacity doesn’t exist to replace them. No investor is helped when the cost of capital spikes in the face of weaponized uncertainty.
This is not a plan to make America stronger. It’s a gamble that markets and allies will blink first. It’s brinkmanship with no floor.
And the most maddening part? There was a path. A real one. A version of this policy that could’ve worked -- not in headlines or soundbites, but in practice. A path that applied pressure with purpose, that aligned economic force with long-term national interest, that sent a clear message to adversaries and partners alike without destabilizing global commerce or blindsiding capital allocators.
You could’ve gone after China -- hard -- and had the backing of nearly every serious investor and strategist on the Street. Not just because of trade deficits or currency suppression, but because China has been actively undermining our economy and our people. I would’ve supported a four-year plan to end all dependence on Chinese manufacturing unless they stopped stealing American IP (DeepSeek). No more games. Make it explicit: if they don’t comply, we’ll back Taiwanese independence and bring the entire global semiconductor economy with us. No ambiguity. No half-threats. As I see it, China is at war with us -- and our policy should reflect that.
With the EU, you could’ve played it clean. Match auto tariffs percent-for-percent. That’s fair. And then leave the rest alone -- especially goods and services. We run a huge surplus on services with the EU. It props up some of our biggest competitive advantages -- enterprise software, consulting, cloud, defense tech, streaming, media IP. Tariffing the EU outside of autos would be like shooting your own foot for balance. We’re not in a trade war with Europe. We're in a competition for global enterprise dominance -- and right now, the U.S. is winning.
That’s what real strength would’ve looked like. That’s what an America-first trade doctrine could’ve achieved. You’d be rebuilding the system from the inside out -- not just throwing bricks through the windows and calling it a redesign.
Investors would’ve backed it. CEOs would’ve planned around it. Global partners would’ve respected it -- even if they didn’t like it. And capital would’ve flowed toward American resilience instead of retreating from American unpredictability.
But instead of that, you went with chaos. And now, confidence is shattered. Not because the numbers are bad -- but because no one knows what the numbers mean anymore.
That’s the cost of burning down the rules without building new ones.
So no, this is not the detox we needed. It’s not strategic decoupling. It’s not a path to renewal. It’s a slow, loud dismantling of the very foundation that has allowed American capital, innovation, and enterprise to dominate for decades. And it didn’t have to be this way.
But now we’re here. And the market is reacting accordingly -- not to the fundamentals, but to the sense that the future may no longer be modelable. That’s not a trade. That’s an exit.
I don’t want this post to be hyper-political. This isn’t about red or blue. It’s not about the 2024 election cycle. It’s not about ideology. It’s about strategy. It’s about execution.
It’s about understanding that when you're the United States -- when you sit at the helm of the global economic engine -- every policy you roll out reverberates through capital markets, supply chains, boardrooms, and governments. Words become signals. Signals become pricing. Pricing becomes pain -- or progress.
And I hope -- for the sake of the markets, for the sake of businesses trying to plan, and for the future we’re all investing into -- that it’s not too late to recalibrate.
Because we don’t need more noise.
We need a plan.
@Tiefseher Du meinst bestimmt nicht den MSCI World, sondern den von deinem Kollegen Holger geliebten gehebelten NASDAQ ETF. Darauf trifft Vermögensfalle zu, die jetzt auch schmerzhaft zuschnappt.
WOW. Forward bookings from Canada to the U.S. have fallen by more than 70 percent for each month through the end of September, compared to the same period last year. April has seen the steepest decline, with just 296,000 bookings — down 76 percent from 1.3 million.
And if you think it's only Canadians who no longer want to visit the U.S., you're sorely mistaken. Many Europeans have canceled their planned vacations to the States as well—a trend that will result in a devastating blow worth many billions of dollars to the U.S. economy and cost thousands of Americans their jobs.