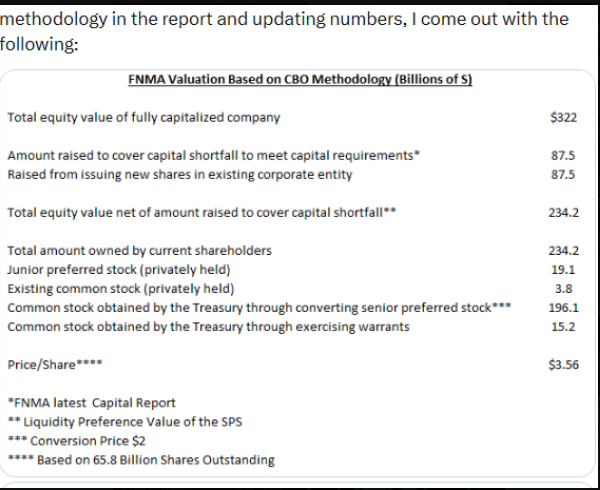
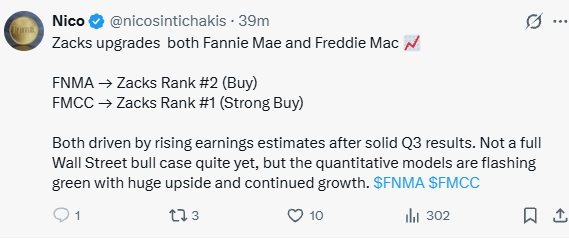$FNMA $FMCC
The F2 Earnings Fallacy: Getting the Numbers Right and the Investment Wrong
With Fannie and Freddie, you can get the earnings analysis exactly right and still get the investment very, very wrong. Earnings tell you what the businesses generate; policy determines how much of that value ultimately belongs to existing shareholders.
Strong profits don’t tell you how Treasury’s senior preferred stock will be treated, how much dilution common shareholders will face, or when conservatorship will end. Different policy outcomes can produce radically different valuations for the same earnings stream.
For example, my last valuations were:
Extreme dilution: $1.50 per share
SPS cancellation: $40 per share
That’s roughly 2,567% upside from the extreme dilution scenario to the cancellation scenario: ($40 − $1.50) ÷ $1.50 × 100.
Much of what passes for “analysis” here simply assumes SPS cancellation and builds a valuation around that outcome. But assuming the most consequential variable will be resolved in your favor isn’t the same as analyzing it.
Suppose someone makes that assumption and also correctly predicts earnings will come in 20% above expectations. Holding the valuation multiple and other assumptions constant, their $40 target becomes $48.
But if extreme dilution occurs, that same 20% earnings improvement takes the $48 valuation to just $1.80.
They nailed the earnings forecast, yet their $48 target is still $46.20 above the valuation implied by the policy outcome.
Earnings matter, but the precision of your earnings forecast becomes almost irrelevant if you get the policy outcome wrong. In this example, stronger earnings add just 30 cents under extreme dilution, while the wrong policy assumption produces a $46.20 valuation gap. You can refine the earnings estimate all you want; it won’t rescue a valuation built on the wrong policy assumptions.
@63andConcerned Ray, I don’t know who the fuck SI is. I spent three years covering this piece of shit as an analyst at my last job and wrote about it extensively. I’m making the same points I made back then.
@63andconcerned Ray, you went from institutional demand to my dating history in three sentences. My $1.50 estimate assumes extreme dilution. If you think institutions will rush in at that price, what do you think they’ll see that my valuation misses?
As for my dating history, let’s just say I’ve had my hog smoked by more women who’d wouldn’t have given you a second glance, but that assumes you’d get a first.
$FNMA $FMCC
As my Dad (Not to be confused with @ScottCoverleySr who I have been told was smart enough to lose a $3million lawsuit to Tim Palagria) used to say, "Some people are bigger assholes than others"...He never met @FannymayFnma but this is exactly the kind of guy he was talking about:
“Nothing says ‘sound investment thesis’ like threatening officials with prison if it doesn’t work out.”...
The bull case now involves a hostage negotiation. Incidentally this is "For entertainment purposes only"
$FNMA $FMCC
Just asking for a friend...Do the quantitative models know F2 is in conservatorship and has everything to do with political/policy analysis and almost nothing to do with earnings?
$FNMA $FMCC
Now that we've established the SPS has been "repaid" lets give it back to the "American People"... I Can't tell you how hilarious it is when guys use that term to describe shareholders!