Some good performance from PF stocks till now:
1. Aimtron Electronics: 2x now
2. Prizor Viztech: 5x now
3. V Marc Industries: 2.5x now
4. Sunlite Industries: 2.5x now
5. Utssav Gold CZ: 2.5x now
6. Purple United: 1.5x now
7. Krishna Defence: 2x now
8. Monolithisch: 1.5x now
9. Cosmic CRF: 1.5x
Hoping others to join party soon...
: 🚀🌕
The BSE SME IPO Index is almost back at its all-time high @ 1,19,100 📈
It crashed early this year, but has fully recovered and is now approaching its previous peak of ~1,21,600.
Once the break out is done, the next resistance levels sit at ~1,51,000 and then ~1,98,400 (based on Fibonacci)
Tighten your seat belts folks! 🚀
Note: Fibonacci is a tool to measure potential resistance.
Cosmic CRF 🚆
Excellent execution happening quietly under the hood.
A beast in hibernation for now. The day it wakes up, this one is going to fly high. 🤞
: 🚀🌕
#cosmicCRF#cosmic CRF
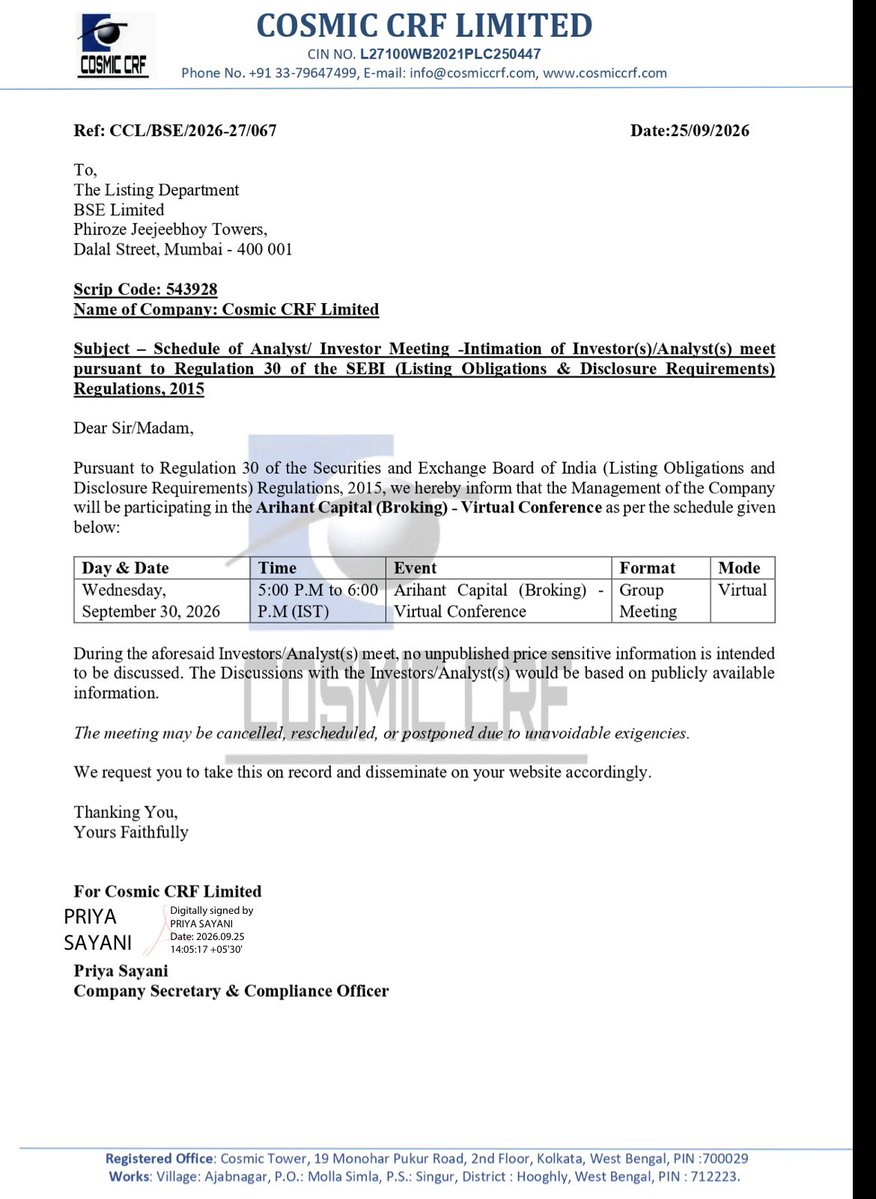
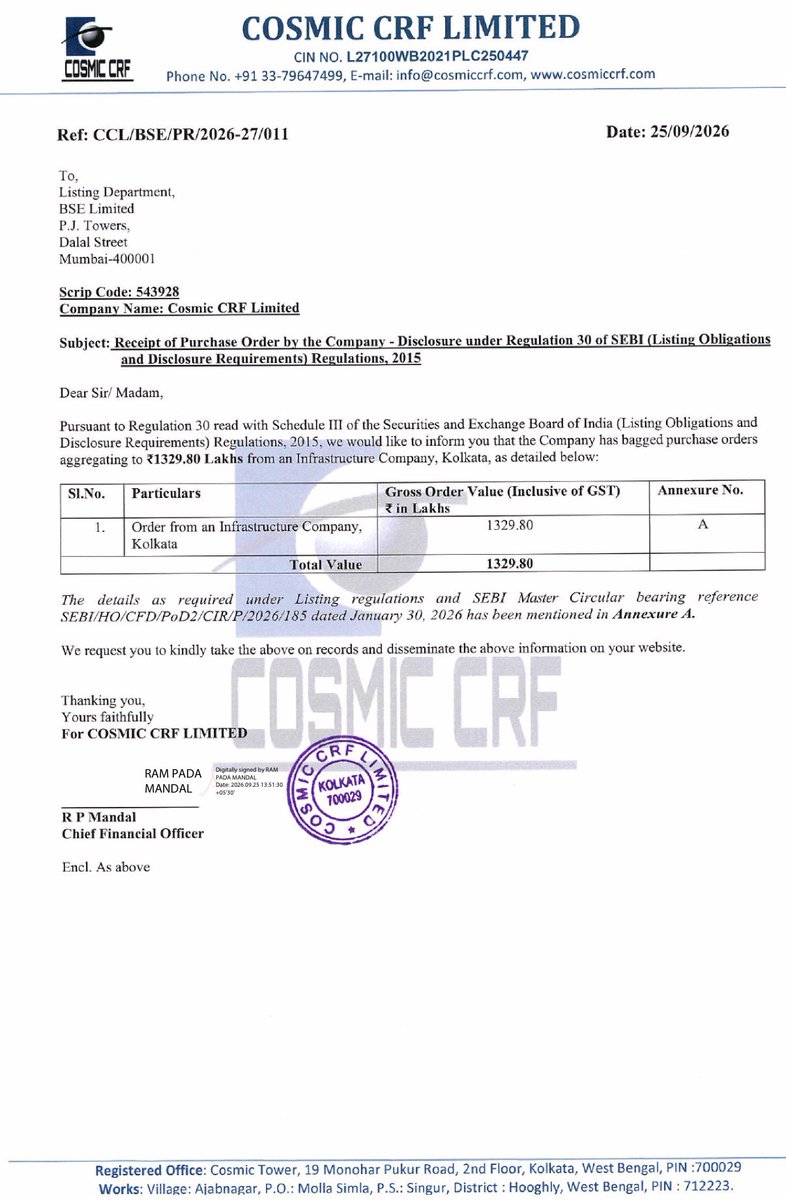
2 new announcement from cosmic CRF…
1. Investor meet on 30th Sep
2. 26.32 Cr new order 🔥
*** END***
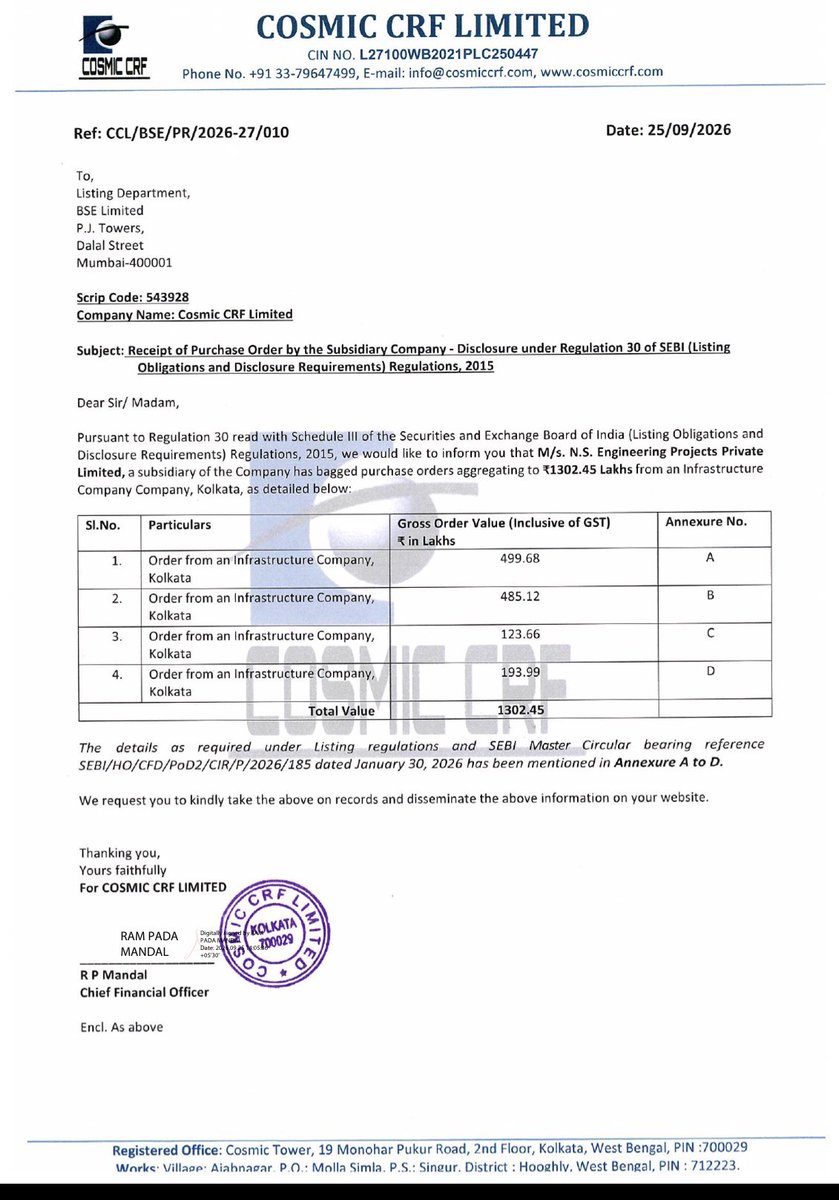
Kolkatta industrial revolution started… Flood of orders from Kolkatta Industries…
Har Har Mahadev …
Added Utssav CZ Gold as my Janmashtami utsav pick. Stock is in ESM so liquidity is thin.
Once ESM lifts and the festive utsav begins, this can go bonkers.
It is already 2x from my initial buy & is at 63D EMA.
Upward averaging :)
: 🚀🌕
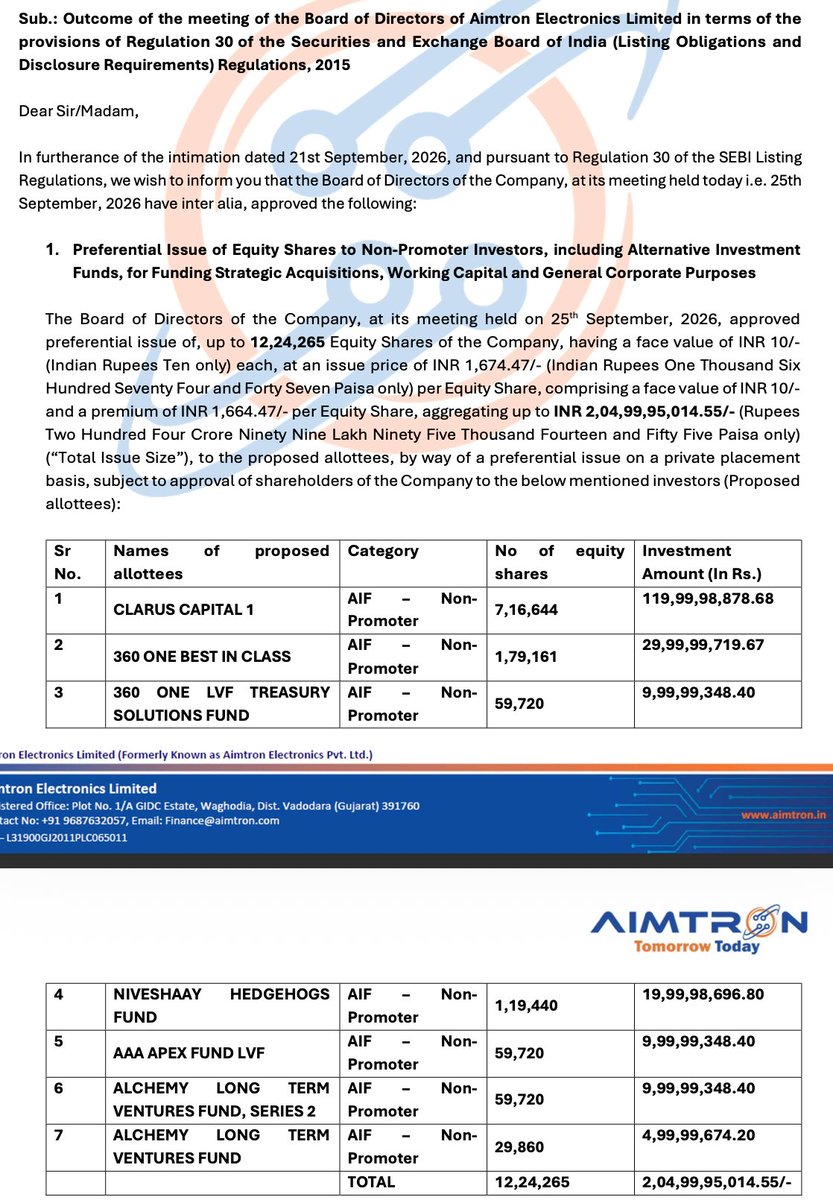
Aimtron Electronics
The Board just approved a ₹205 Cr fundraise and it's 7 marquee institutional funds writing the cheque.
💰 Raise: ₹204.99 Cr
📊 12,24,265 shares @ ₹1,674.47 (preferential)
🏛️ Backers:
· Clarus Capital
· 360 ONE
· Niveshaay
· AAA Apex
· Alchemy Long Term Ventures
The mission: Global expansion via acquisitions & JVs, plus working capital & growth.
When this many smart-money funds line up at once, it's worth paying attention. 📈
Note: Holding since 650/- levels and did upward averaging till 1550/-
Added to existing positions:
1. Aimtron Electronics
2. Monolithisch
3. Purple United
Took new position in:
1. Neetu Yoshi
Plenty of tempting setups out there right now, but no cash left to deploy 🙁
Stock markets are full of endless regret.
I still remember selling US stocks to move the money into Zelio E-Mobility at ₹330-340 levels, but at the last moment I changed my mind and bought something else instead.
And of course, Zelio never disappoints. It's already 3x since that day 😐
What's the one regret that still pinches you every day?
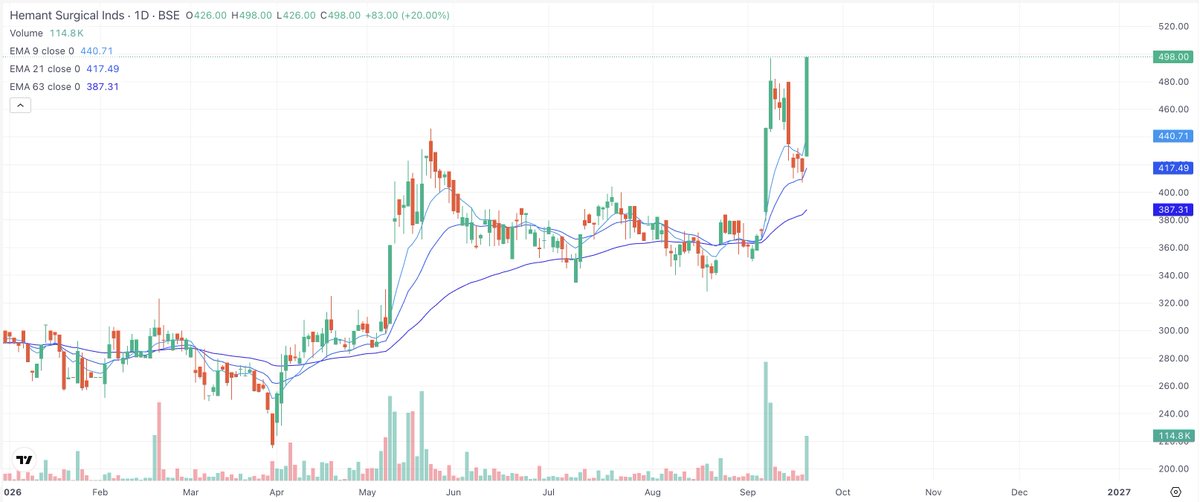
Hemant Surgical Industries
What a stellar rally!
50% returns in a week 📈
Booked a few lots and rotated capital into:
Sunlite Recycling - available around 21D EMA
Sunlite is already 3x from my initial buy..
Upward Averaging :)
Added Hemant Surgical Industries at 21D EMA Levels
Rocket today, 20% up 📈
I was short on capital so I couldn't take the full position, but even a partial ride to the moon counts..
: 🚀🌕
Nifty Smallcap 100 & Nifty Smallcap 250 showing nearly identical chart structures.
Both hovering around the 9 EMA on weekly - a retest of the 21 EMA on the weekly charts looks likely from here.
Healthy correction..
Added to existing positions:
1. Aimtron Electronics
2. Monolithisch
3. Purple United
Took new position in:
1. Neetu Yoshi
Plenty of tempting setups out there right now, but no cash left to deploy 🙁
Added Adisoft Technologies today @ 200-210 levels.
Detailed Summary:
What it does
- The problem: a factory's machines and robots don't naturally share data with each other or the office.
- Adisoft: the layer that ties the floor together, running the line, checking quality, tracking every part, and feeding live data into the company's core systems.
- The edge: it runs on the machines themselves in real time, not just software on a screen.
Products
- Production control, quality checks, part tracking and traceability, and ERP integration.
- Hardware from Mitsubishi Electric, Omron and Keyence, programmed and integrated by Adisoft.
Moat
- Mission-critical systems that control whole shops, so customers stay with proven integrators.
- Peers each specialise in one shop type (press, weld, paint or assembly). Adisoft's data layer works across all shop types, giving wider scope per customer.
- In-house, reusable design/software library, so margins improve with every repeat order.
- Often the only qualified bidder, wins over 95% of tenders. Maintenance staff can run it themselves (no "black box"), which pure IT/MES rivals can't match.
Trigger
- FY27 guide about ₹215 Cr (roughly 30% growth), aiming for ₹500 Cr+ by FY30.
- Order book ₹38.5 Cr in-hand plus ₹57 Cr pipeline; about ₹30 Cr already done in Q1 FY27.
- New 25,000 sq ft facility live by November 2026, lifting capacity to about ₹650 to 700 Cr.
AIOI Japan JV (24%)
- Joint venture with AIOI Systems Japan, a global leader in digital picking (65 countries).
- Opens warehouse and e-commerce automation, and acts as an overseas springboard.
Tailwind and diversification
- India's industrial automation market is growing ~14% a year (low robot density, policy support), so every new smart factory is a possible customer.
- Expanding beyond autos into pharma, white goods, printing and e-commerce; overseas by following Indian OEMs abroad.
Vs peers (company's own FY26 benchmarking)
- Adisoft: ₹166 Cr revenue, 13.5% PAT margin, 31.5% ROE, 15.0x TTM P/E.
- Patil Automation: ₹150 Cr revenue, 10.1% PAT margin, 27.3% ROE, 36.4x TTM P/E.
- Affordable Robotic: ₹118 Cr revenue, 5.9% PAT margin, 6.6% ROE, 33x TTM P/E.
So Adisoft is the most profitable and highest-ROE of the three, yet the cheapest on P/E.
Valuation (from guidance)
- Adisoft: ₹215 Cr guide at ~14% margin ≈ ₹29-30 Cr profit. At ~₹350 Cr value, ~12x forward.
- Patil Automation: ₹260-270 Cr guide at ~10% margin ≈ ₹26-27 Cr profit. At ~₹650 Cr value, ~22-24x forward.
So Adisoft trades at roughly half the multiple, with better margins. Adisoft near its lows, Patil Automation near its highs.
Institutional
- Motilal Oswal bulk-bought 1,20,800 shares at ₹212 (about ₹2.6 Cr)
Risks
- Top 5 customers are about 80 to 85% of sales (single largest ~65%), the main risk to watch.
: 🚀🌕
Added Hemant Surgical Industries at 21D EMA Levels
Rocket today, 20% up 📈
I was short on capital so I couldn't take the full position, but even a partial ride to the moon counts..
: 🚀🌕
Pramodini Medicare
Pramodini majorly operates CT and MRI machines inside government hospitals under long-term Public-Private-Partnership (PPP) contracts. It is a steady, profitable business, running at roughly a 50% operating margin.
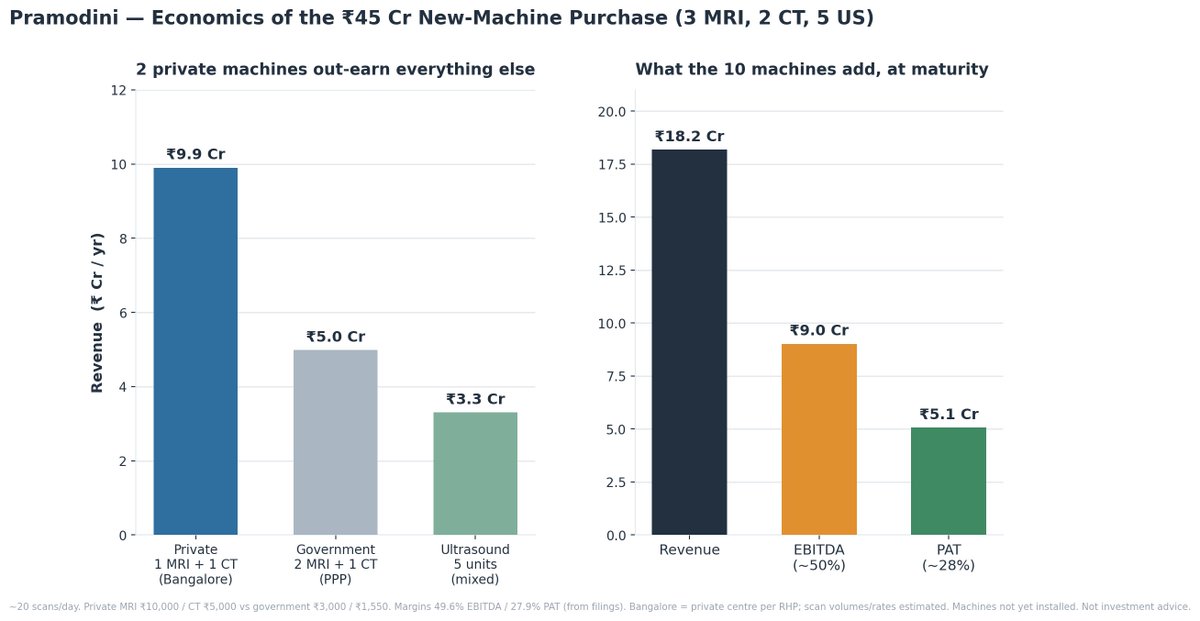
It has raised ₹45 Cr to add 10 new machines: 3 MRI, 2 CT, and 5 ultrasound. Where they go matters - 2 go to a new private centre in Bangalore, the rest to existing government-hospital centres. A private scan earns about three times more than a subsidised government one.
Example: each machine does about 6,600 scans a year (~20 a day).
Private (Bangalore Pvt-Pvt, conservative market rates):
1 MRI × 6,600 × ₹10,000 = ₹6.60 Cr
1 CT × 6,600 × ₹5,000 = ₹3.30 Cr
Private Total → ₹9.9 Cr
B2G (government PPP, contracted rates):
2 MRI × 6,600 × ₹3,000 = ₹3.96 Cr
1 CT × 6,600 × ₹1,550 = ₹1.02 Cr
B2G total → ₹5.0 Cr
Ultrasound (5 machines, mixed):
5 × 6,600 × ₹1,000 = ₹3.30 Cr
Total ≈ ₹18.2 Cr.
PAT at 28% is ~5.1 Cr.
That is the whole investment lever. The more Pramodini grows its private business (its own centres and private-hospital tie-ups) versus subsidised government work, the more each machine earns.
My take: a business with a durable government moat, but the growth is steady rather than explosive, so it is not a candidate I am investing in personally.
Also, the machines haven't even been installed yet.
For context, Krsnaa Diagnostics operates in the same space and trades at around 17x earnings (P/E).
🚨ANOTHER BLACK SWAN EVENT! KORE DIGITAL💣3270 investors are in for serious shock and LOSS OF CAPITAL.
🚨KORE DIGITAL SCAM EXPOSED: SEBI INTERIM ORDER EXPOSES TOTAL FRAUD by Kore Digital Ltd & its promoters Ravindra Doshi, Chaitanya Doshi & Kasmira Doshi by publishing fraudulent financial statements and also 🔴DIVERTING entire Rs.43Cr Preferential Amount.
🔴Kore Digital & Its Promoters are banned from dealing in shares of Kore Digital.
🔴They are banned from raising funds from the securities market in any other name or form
🔴SEBI has ordered Forensic Examination of Accounts.
🔴NSE has been asked not to allow MIGRATION to Mainboard due to the scam.
🔴The Statutory Auditors have been referred to
National Financial Reporting Authority for appropriate actions for involvement in the scam.
@SEBI_updates has to be appreciated for the Interim Order.
BUT IT HAS NOT FILED POLICE
COMPLAINT REGARDING STEALING OF Rs.43Cr INVESTOR MONEY . THIS HESITATION OF SEBI TO PROMPTLY PROCEED WITH CRIMINAL COMPLAINT IS ACTUALLY CAUSING MORE AND MORE SCAMS. Why @SEBI_updates ????
Added to existing positions:
1. Aimtron Electronics
2. Monolithisch
3. Purple United
Took new position in:
1. Neetu Yoshi
Plenty of tempting setups out there right now, but no cash left to deploy 🙁
@mohannd0202 - Natural rubber prices at a 10-year high: https://t.co/vCKFOAMItj
- Rising demand for recycled rubber
- Horizon's new pyrolysis-oil capacity is live, reclaimed-rubber capacity coming soon
These were my filteration critera. Let me know what you think.