⚖️ GST order set aside for violation of natural justice.
In M/s Shakti Industries v. DGGI, Lucknow, the taxpayer said it was unable to file its reply on the GST portal.
FOR MORE DETAILS:https://t.co/YfJsw1g6KN
So, it submitted its detailed reply by email to the address provided by the Adjudicating Authority.
But the final order recorded that no reply had been filed.
The Allahabad High Court took note of this.
The Court held that once the reply was submitted to the email address provided by the authority, it was required to be considered.
Ignoring the reply violated the principles of natural justice.
The adjudication order dated 25.03.2026 was set aside and the matter was sent back for fresh proceedings.
Important lesson for taxpayers:
A proper opportunity of being heard is not just a formality.
And for professionals — always preserve proof of replies, emails, attachments and delivery. 📩
Case: Writ Tax No. 2810 of 2026
Allahabad High Court | 19 August 2026
#GST #GSTIndia #GSTLitigation #NaturalJustice #TaxLitigation #CGSTAct #IndirectTax #LegalIdea
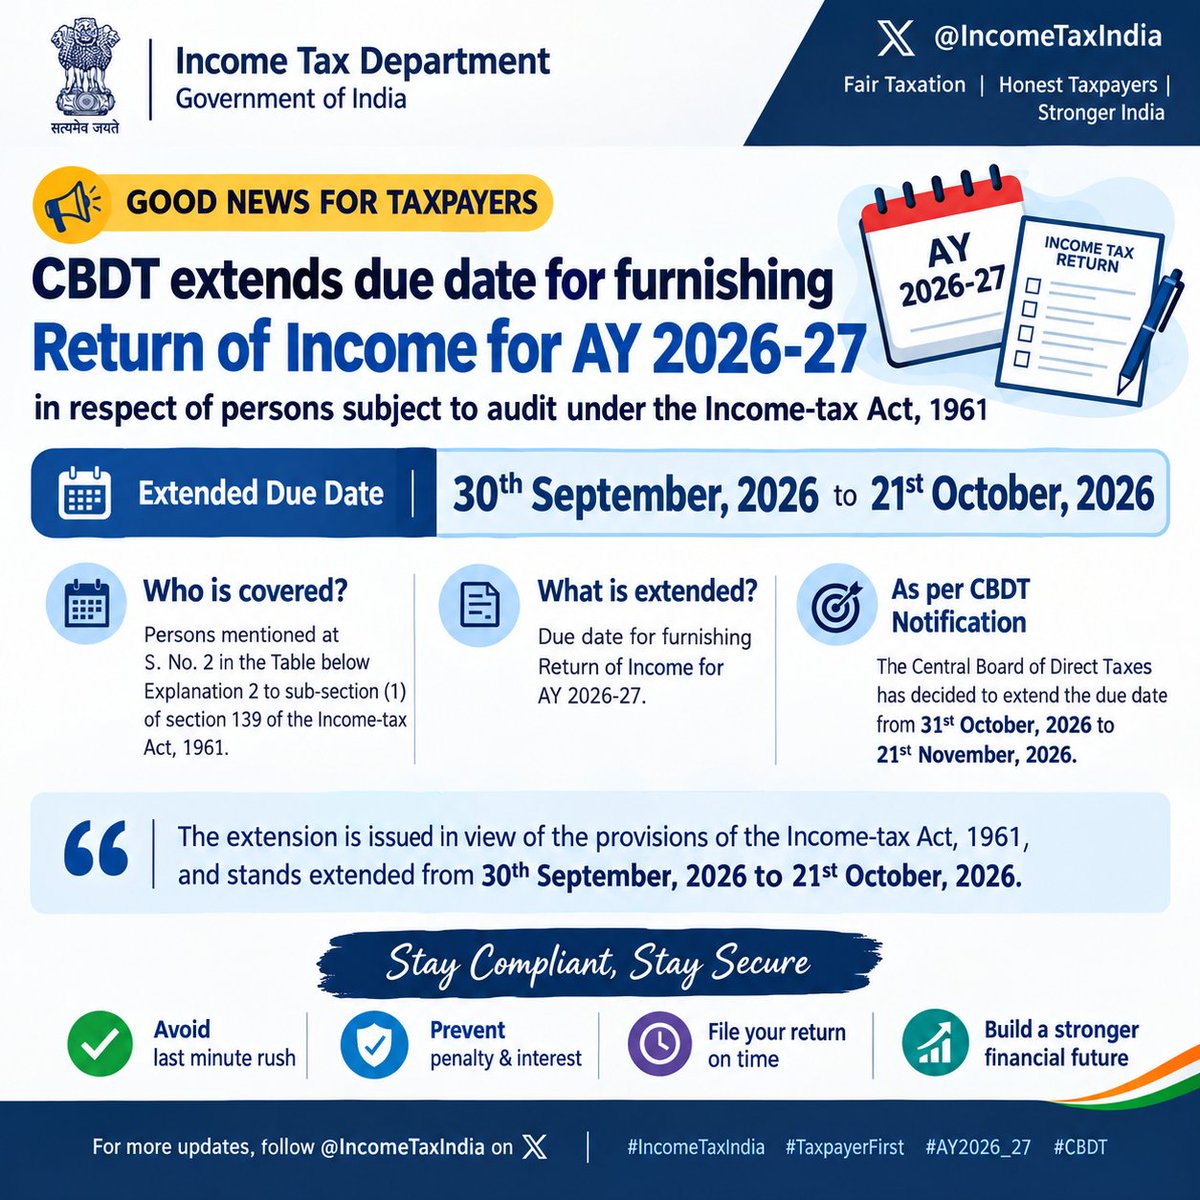
📢 IMPORTANT TAX UPDATE | AY 2026–27The CBDT has extended the due date for filing the Income-tax Return for AY 2026–27 in cases covered under the tax-audit provisions.🔹 Original due date: 31 October 2026
🔹 Extended due date: 21 November 2026The corresponding specified date for furnishing the tax-audit report has also been extended from 30 September 2026 to 21 October 2026.✅ Taxpayers and professionals should use the additional time to ensure:
• Proper reconciliation of books & GST
• Accurate tax-audit reporting
• TDS/TCS reconciliation
• Correct computation of taxable income
• Timely filing without last-minute errorsExtension of time is not a reason to delay compliance—use it for accuracy and proper review.Official update: Income Tax Department — Official X Post#IncomeTax #CBDT #AY202627 #TaxAudit #IncomeTaxReturn #TaxCompliance #DirectTax #TaxProfessionals #TaxUpdate #IncomeTaxIndia
Very disappointed with the service experience of @DRSAgarwal.
It has been almost a month with no proper response. The surveyor is neither answering calls nor visiting to inspect the matter.
Unfortunately, my experience with Agarwal Packers & Movers has been extremely poor.
TAX AUDIT 2026 FY 2025-26 | AY 2026-27
Due date: 30 September 2026 Not 31 October. Not “sometime in October.” 30 September.
The CA files the report. You still have to approve it. Miss either step and the file is incomplete.
Save this calendar
•Tax audit report (3CA/3CB + 3CD) → 30 Sep 2026
•ITR for audit cases → 31 Oct 2026
•Form 3CEB (TP) → 31 Oct 2026
•ITR for TP cases → 30 Nov 2026
This year is still under the Income-tax Act, 1961. New Act + new Form 26 start from FY 2026-27. Do not mix the two.
Who needs tax audit?
Business Turnover above ₹1 crore OR above ₹10 crore only if both cash receipts and cash payments are ≤ 5%. Non-account-payee cheque/draft = cash.
Profession Gross receipts above ₹50 lakh
Also if you declare income below the presumptive rate. Companies: audit is not optional.
What changed this year (share this part)
1Shorter audit season Non-audit business ITR is now 31 August. Your real audit window is one month. Plan like it.
2Form 3CD is stricter
◦MSME dues + 43B(h) delay
◦Settlement / compounding spend
◦Coded loan-deposit reporting
◦Share buyback details
◦44BBC for cruise operators
3Penalty is real Late / no tax audit → 0.5% of turnover, cap ₹1.5 lakh (Sec 271B). Losses and scrutiny risk sit on top of that.
Do this week
•Freeze turnover + 5% cash workings
•Age MSME bills
•Match books vs GST vs AIS
•Upload early. Approve the same day.
•ITR numbers must match 3CD. Word for word.
30 September is 29 days away. Books first. Portal second. Approval last.
Save. Share with your CA. Tag the founder who still thinks “October is fine.”
#TaxAudit2026 #FY202526 #AY202627 #Section44AB #Form3CD #CA #IncomeTax #MSMEs #ITR2026
Thank you to everyone who retweeted, quoted and shared this post: https://t.co/FjjT7fqL2V
Your replies and shares made the last-day MCA-21 outages visible — login failures, timeouts and stalled filings on the closing date of CCFS-2026.
Update: MCA has now extended the Companies Compliance Facilitation Scheme, 2026 (CCFS-2026) to 15 September 2026 vide General Circular No. 04/2026 dated 31 August 2026. All other terms and conditions remain unchanged.
Use the extra window. Hope the portal stays stable this time.
@MCA21India
#MCA #MCA21 #CCFS2026 #ROCFiling #CompanySecretary #CharteredAccountant #Compliance #EaseOfDoingBusiness
Income Tax Portal Issue ⚠️
Is anyone else facing the “Invalid Password” error on the Income Tax Portal today?
The same password was working perfectly this morning, and I was able to successfully download TIS/AIS. Now, without changing the password, the portal is showing “Invalid Password.”
@IncomeTaxIndia@FinMinIndia — please look into this issue.
Fellow tax professionals, are you also getting the same error? Please comment if you’re facing it too.
#IncomeTax #IncomeTaxPortal #AIS #TIS #CBDT #TaxProfessionals
GST notice to a dead taxpayer.
MORE DETAILS :- https://t.co/guyHd1BdZv
Death: 29 July 2020
GST notice: 26 June 2025
GST order: 4 December 2025
Gujarat HC: Both quashed.
But here's the important part:
The Court did not say the tax liability can never be recovered.
It only said the department must proceed in accordance with law against the legal heir.
Lesson:
Before fighting the tax amount, check whether the proceeding itself is legally valid.
You paid GST to your supplier.
He didn't pay the Government.
Can YOU lose ITC?
more details:- https://t.co/atMAfvhdUU
Gujarat HC has answered an important challenge to Section 16(2)(c) of the CGST Act.
In Maruti Enterprise v. Union of India & Ors., the Court upheld Section 16(2)(c).
ITC is subject to the statutory conditions.
And the buyer carries the burden of establishing eligibility.
But here's the important part:
Genuine buyer ≠ fraudulent buyer.
The Court observed that ITC can be denied where the recipient knew or ought to have known that the purchase was connected with fraudulent tax evasion.
The Court also recognised the pain for genuine purchasers and called for better legislative and technology-based solutions.
And Rule 37A/Section 41 provide a reversal + re-availment mechanism when the supplier eventually pays the tax.
Tax lesson:
Vendor compliance is no longer just your vendor's problem.
Check.
Reconcile.
Document.
And put an ITC indemnity clause in your vendor agreements.
Because sometimes your biggest tax risk is sitting in someone else's GST return.
#GST #ITC #GSTLitigation #Section16 #TaxPlanning #GSTCompliance #IndirectTax
Freedom is earned. Nation-building is sustained. 🇮🇳
On this 80th Independence Day, let's remember that every honest taxpayer contributes to a stronger India.
���� Every GST return filed on time.
📄 Every Income Tax Return submitted correctly.
🤝 Every compliant business.
These are not just legal responsibilities—they are contributions to India's progress.
At Legal Idea Consultancy P. Ltd., we are proud to help businesses and individuals stay compliant while building a stronger nation.
This Independence Day, let's pledge to celebrate freedom with responsibility.
🇮🇳 Happy Independence Day!
Jai Hind!
From :-@chetansoniji @Sidkacholiya and Legal Idea Team
#IndependenceDay #India #HarGharTiranga #JaiHind #GST #IncomeTax #TaxCompliance #TaxPlanning #MakeInIndia #DigitalIndia #ViksitBharat #CA #CharteredAccountant #LegalIdea #NationBuilding
Tax Saving ≠ Investment Planning
This is where many people get confused.
They invest ₹1,50,000 just because someone said:
“You’ll save tax.”
But the better question is:
“Would I make this investment even without the tax benefit?”
Tax saving should be a benefit of your financial decision — not the reason for a bad investment.
Think in this order:
Need → Goal → Risk → Return → Lock-in → Tax Benefit
Not:
Tax Benefit → Invest → Regret
A good investment can help you build wealth.
A good tax plan can help you keep more of that wealth.
The best strategy is to make them work together.
#TaxPlanning #TaxSaving #Investments #PersonalFinance #IncomeTax #WealthCreation #FinancialPlanning
🚨 Can GST ITC be denied just because the supplier's registration was cancelled later?
The Madras High Court says the answer isn't that simple.
If the supplier was GST registered at the time of supply, filed returns, paid tax, and the buyer has genuine invoices, the department cannot mechanically deny ITC without properly examining the transaction.
The Court found an important flaw.
The department rejected ITC only because lorry receipts and weighment slips were not produced.
But it ignored:
✅ Supplier was registered when goods were supplied.
✅ Tax invoices contained vehicle numbers.
✅ Supplier had filed GST returns.
✅ Taxes were reportedly paid.
The Court held that these facts deserved proper verification before confirming the demand.
The assessment order was set aside.
The matter goes back for fresh consideration.
The takeaway?
Missing documents may raise questions. They don't automatically prove a fake transaction.
#GST #InputTaxCredit #ITC #MadrasHighCourt #GSTLitigation #TaxUpdate #CaseLaw #LegalIdea
Never reply to a tax notice before answering these 3 questions.
What is the notice really asking?
Not the section. Not the fancy wording. The real issue.
What proof do we actually have?
If the papers are weak, the reply will be weak too.
What happens if we answer it the wrong way?
Because one careless reply can turn a small notice into a bigger mess.
Most people rush here. That is where the damage starts.
Send this to your finance team.
#IncomeTax #GST #TaxNotice #TaxCompliance #LegalIdea
🚨 CBDT Gives Relief to Charitable Trusts & Institutions
Missed the deadline for filing Form 10AB to renew approval under Section 80G?
There's some relief.
CBDT has condoned the delay for eligible trusts and institutions that filed Form 10AB electronically between 1 October 2025 and 31 March 2026.
Even if your application was rejected only because it was filed late, it will be treated as if the delay has been condoned and reconsidered on merits.
But don't read this as:
"Late filing is now okay." 😅
It isn't.
This circular removes a genuine hardship. It does not guarantee approval under Section 80G. The application will still be examined on its merits.
A missed deadline shouldn't end a genuine case—but compliance should never become a habit of "we'll do it later."
#CBDT #80G #Form10AB #CharitableTrust #NGO #IncomeTax #TaxUpdates #TaxCompliance
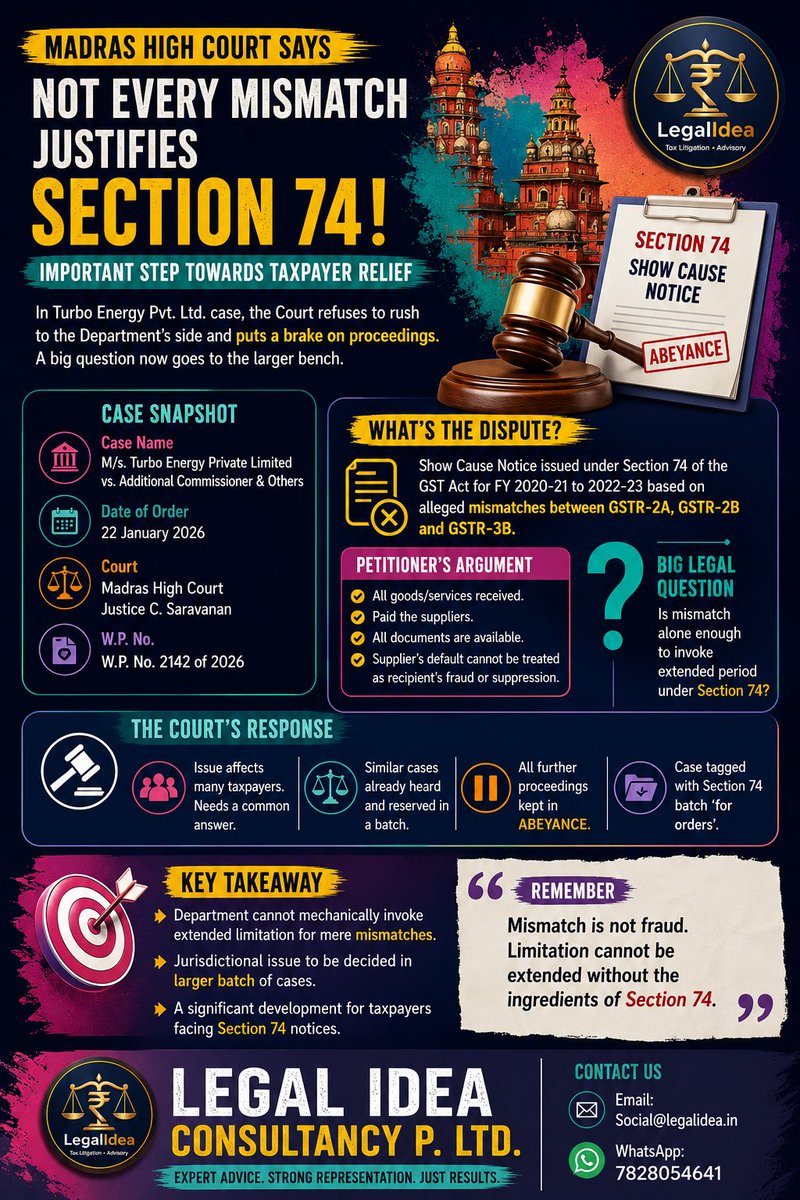
🚨 Can GST authorities use the extended limitation period under Section 74 just because there's a mismatch between GSTR-2A/2B and GSTR-3B?
The Madras High Court isn't convinced.
In Turbo Energy Pvt. Ltd., the Court noticed that this issue affects a large number of taxpayers and deserves a common ruling.
Instead of allowing the proceedings to continue, the Court directed the department to keep all further proceedings in abeyance until the larger batch of Section 74 cases is decided.
The bigger question is now before the Court:
📌 Is a return mismatch enough to invoke Section 74?
📌 Or must the department first establish fraud, wilful misstatement or suppression?
This batch of cases could shape the future of GST litigation.
#GST #Section74 #MadrasHighCourt #GSTLitigation #GSTR2B #InputTaxCredit #TaxUpdate #LegalUpdate
🚨 The Supreme Court isn't banning AI. It's warning us against trusting it blindly.
This case started as an insolvency appeal.
It ended with one of the strongest judicial statements on the use of AI in Indian courts.
The problem wasn't AI.
The problem was fake case laws, non-existent citations and AI "hallucinations" finding their way into a judicial order.
The Supreme Court drew a line:
✅ Use AI to assist.
❌ Don't use AI to replace legal thinking.
The Court declared zero tolerance if lawyers or judges cite AI-generated precedents without verification.
Even one fake precedent can taint the entire decision.
The Court also directed the Bar Council of India to frame guidelines and consider disciplinary action against advocates who submit such material.
The takeaway?
AI can draft.
AI can summarize.
AI can research.
But responsibility still belongs to the human signing the document.
That's not just good law.
That's good professional ethics.
#SupremeCourt #ArtificialIntelligence #LegalTech #AI #Law #CaseLaw #LegalResearch #IBC #Judiciary
🚨 A big ruling for lawyers, insurers, tax professionals and every business owner.
Your Income Tax Return is evidence. But it's not always the whole story.
In a landmark judgment, the Supreme Court has finally settled an issue that different High Courts were deciding differently:
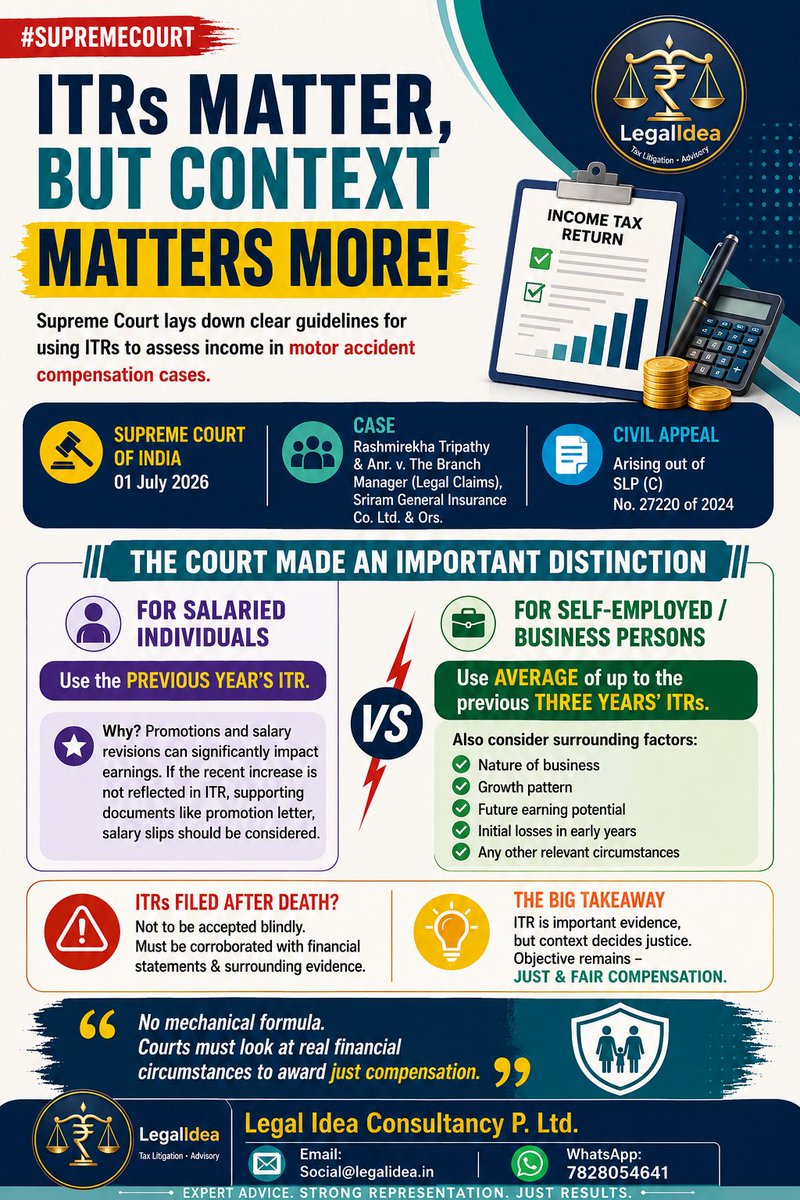
Which ITR should be used to determine income while calculating motor accident compensation?
The Court made an important distinction.
👨💼 If the deceased was a SALARIED employee:
Use the previous year's ITR.
Why?
Because promotions, salary revisions and increments can significantly change earnings. Looking too far back may understate the person's actual income. If the promotion is recent and not fully reflected in the ITR, supporting documents like the promotion letter and salary records should also be considered.
��� If the deceased was SELF-EMPLOYED or running a BUSINESS:
There is no one-size-fits-all formula.
The Court said the average of up to the previous three years' ITRs should normally be the starting point.
But don't stop there.
Courts must also look at:
✔ Nature of business
✔ Growth pattern
✔ Future earning potential
✔ Initial losses in expanding businesses
✔ Other surrounding financial circumstances
Because businesses don't grow in straight lines. Some years are exceptional. Some are difficult. Justice cannot depend on one year's numbers alone.
The Court also sounded a note of caution.
If an ITR is filed after the death, it should not be accepted blindly.
It must be tested against financial statements and surrounding evidence to rule out inflated claims.
My biggest takeaway?
This judgment isn't really about tax.
It's about how tax documents are used as evidence.
An ITR is important.
But context is equally important.
The Supreme Court has moved the law away from mechanical calculations and towards fair compensation based on real economic circumstances.
That is likely to become the guiding principle for MACT cases across India.
Case: Rashmirekha Tripathy & Anr. vs. The Branch Manager (Legal Claims), Sriram General Insurance Co. Ltd. & Ors.
#SupremeCourt #MotorAccidentClaims #IncomeTax #ITR #MACT #Compensation #TaxProfessionals #InsuranceLaw #LegalUpdate #CaseLaw
🚨 GST Update: AATO Amendment Timeline Revised
GSTN has changed the timeline for amendment of Aggregate Annual Turnover (AATO) details for FY 2025-26.
Earlier:
📌 Amendment window was available in May.
Now:
✅ Taxpayer Amendment Window: 01 July 2026 to 31 July 2026
✅ Tax Officer Review: 01 August 2026 to 15 August 2026
Why this matters?
AATO impacts various GST portal functionalities and compliance processes. A small mistake in turnover reporting can create unnecessary issues later.
Before submitting:
✔ Check turnover figures carefully
✔ Verify amended details
✔ Keep supporting records ready
GST compliance is not only about filing returns — it is about filing the right data at the right time.
#GST #GSTUpdate #GSTN #TaxCompliance #IndirectTax
🚨 GST JURISDICTION SHIFT: Can a taxpayer escape proceedings after shifting business location?
CBIC has finally clarified an important confusion faced by taxpayers and GST officers.
📌 Circular No. 255/01/2026-GST dated 25 June 2026
A common question:
“अगर GST registration दूसरे state/jurisdiction में transfer हो गया, तो क्या पुराने officer की action खत्म हो जाएगी?”
Answer: NO.
The principle is simple:
✅ Action taken by the old jurisdictional officer when they had valid jurisdiction will continue to remain valid.
Whether it is:
• Investigation
• Audit
• Show Cause Notice
• Adjudication Order
• Appeal proceedings
Migration of taxpayer will NOT invalidate the earlier valid action.
But…
After migration, the responsibility shifts.
The new jurisdictional officer will:
➡️ Continue pending proceedings
➡️ Implement earlier actions
➡️ Handle further legal steps
➡️ Represent matters before appellate authorities/tribunals
Important protection for taxpayers:
The old jurisdiction cannot continue taking fresh action after migration. Any new issue must move through the current jurisdictional authority.
💡 Practical Impact:
Businesses shifting their principal place of business should not assume that pending GST matters disappear. At the same time, authorities must follow proper jurisdictional boundaries.
GST litigation is not only about tax liability — jurisdiction and procedure often decide the strength of a case.
Follow Legal Idea Consultancy for practical GST & Tax updates.
#GST #GSTUpdate #GSTLitigation #CBIC #TaxLaw #IndirectTax #GSTIndia #News