Soldier to Millionaire helps soldiers build wealth through discipline, investing, and strategic use of military benefits so they can achieve financial freedom.
$781,000 at a 4% withdrawal is $31,240 a year, or $2,603 a month. Multiply your yearly spending by 25 and you have your target. Cut $500 a month and the target drops $150,000.
#TSP
https://t.co/0WvE50ppxF
Same 20 years, same $6,000 High-3. Legacy pays a $3,000 pension. BRS pays $2,400. But the TSP match adds $492 a month back, so the real gap is $108. Run your own numbers. #MilitaryFinance
https://t.co/dq8tEuSBqr
The S&P 500 fell 34% in 33 days in 2020 and still ended the year up 18.4%. Selling in March locked in the loss. I hold because of one idea from The Intelligent Investor. #investing
https://t.co/CGQtrvjlFX
A promotion's ~$200/month raise, invested in an S&P 500 index fund at 10%, grows to about $143,650 in 20 years. Count your SGT/SSG points before the board does.
https://t.co/JkZvCeiTcQ
I never had to decide to save. The money was gone before I saw it.
$500 a month automated for 20 years at a 10% average return is about $380,000. Skip 5 months a year and it is a different story. #MilitaryFinance
https://t.co/JAVADDaVmd
Park $50,000 in cash to dodge a predicted crash and, at 8% a year, you give up about $8,320 in two years. I've held through 2018, 2020 and 2022. Keep buying. #Investing
https://t.co/2BjAPhbltu
A 5% down payment on a $300K house costs about $20,000 in PMI before you reach 80% equity. I put 20% down and paid $0. Here is the math, including the honest case against it.
#MilitaryFinance
https://t.co/XWZ7OuE5oj
The market fell 34% in 33 days in 2020. I sold nothing and bought on payday. $50K became $33K on paper, then a new high by August. Selling is the only way to make a paper loss real. #investing
https://t.co/yNA0xOKfyu
A 1% advisory fee on a plain $1,000 a month costs you $215,456 over 30 years. Same market, same risk, same money in. Only who got paid changed. #Investing
https://t.co/kpDIMqpHWl
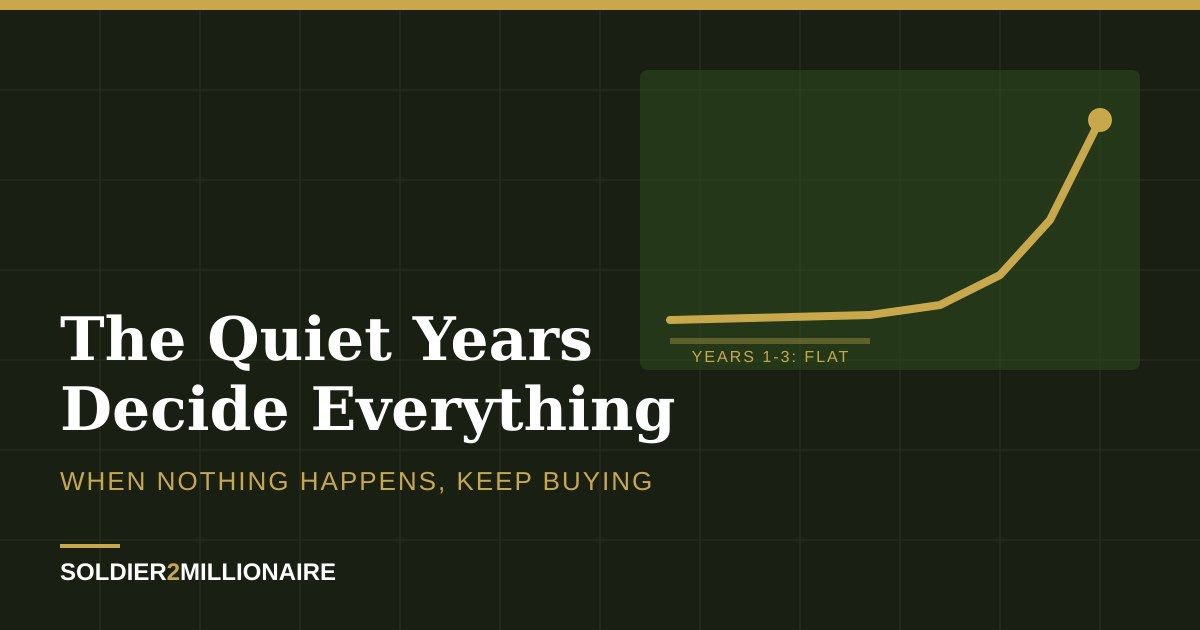
$72,000 in, $83,600 out after 3 years. $192,000 in, $292,000 out after 8. The quiet years look like nothing and decide everything. Keep buying. #investing
https://t.co/ypi6moPvj5
$14,860 in interest on a $45,000 truck at 9.9%. Invest that $831 a month instead and it could be $81,570 in 6 years. #MilitaryFinance
https://t.co/UBuJCBEqZR
2008: duffel bag, nothing else. Age 30: back to $20 in my account. $781K later, the difference was a system that ran every payday, not motivation. #TSP
https://t.co/Eb3B8UMSHq
I sold back 42 days of leave for $3,660 and moved it into index funds the same day. Left alone, that single check turns into six figures. Most soldiers spend it in a week. #TSP
https://t.co/fWox7uxZHH
A private texted me at 0200 about a $600 repair bill. I didn't answer with a spreadsheet — I asked him 3 questions instead. #MilitaryFinance
https://t.co/5OmvCA1dP4
A soldier I mentor lost $6,480 to one line on his LES he stopped reading. Not a bad trade. A TSP % that quietly reset after a PCS. Five lines, thirty seconds, every payday. #TSP
https://t.co/gUcah83yF0
I paid off my house in 2yr9mo, $13,500 total interest. Motivation had nothing to do with it — the payment was automatic and I ignored it. #TSP
https://t.co/uXu0YXkLkC
A soldier I mentor almost left $9,000 in tax-free combat pay sitting in a checking account. TSP has a second contribution limit that kicks in the moment your pay goes tax-exempt — almost nobody checks it. #TSP
https://t.co/0qEIR6sQwX
At 30 I had $20 to my name — after a decade of working 3 jobs and living lean. Scarcity taught me to survive, not to build wealth. Here's the difference, and what changed it. #MilitaryFinance
https://t.co/M2YWIfLs3R
Soldiers who PCS get up to 15 tax-free years to sell a house, not 5. Most never claim it and hand the IRS thousands they never owed. #MilitaryFinance
https://t.co/1r8zOW8QtC