In senior housing, how we approach rent setting and modification can make or break our communities' financial health. We use these six approaches to consistently deliver results when thoughtfully applied:
1) Undercut the Market - When occupancy is the priority, this approach drives leasing velocity to reach stabilization quickly. Effective during lease-up or after census challenges, but watch the long-term revenue trajectory and have a plan to rebuild.
2) Match Market Rates - The steady approach that maintains competitive positioning. Won't stand out, but won't be left behind either. Works well in balanced markets where dramatic moves aren't necessary. Can be challenging to balance what "match" means for RevPOR when base rents are disclosed but triangulating care fees is a bit of an art.
3) Premium Positioning - For communities with superior amenities, services, or locations that genuinely warrant higher rates. This approach maximizes revenue potential but requires delivering consistently exceptional experiences. Many times make sense to use #1 before getting to this point.
4) Growth-Oriented - Strategic rate increases while carefully monitoring occupancy impacts. This forward-looking approach works best in high-demand markets or for properties with established waiting lists. Different from #2 as we're pushing ahead of the field a bit.
5) Conservative/Defensive - Protecting occupancy in challenging markets by prioritizing retention and stable census over rate growth. Sometimes maintaining status quo is the smartest play.
6) Custom Parameters - When standard approaches don't fit the unique situation, crafting targeted strategies based on specific market conditions, demographics, or property attributes.
Those are all relative to the competition. Within a building we can see additional breakdowns (e.g. amenity/level/segmented pricing), but those are only as good as the unit data on hand.
These approaches aren't mutually exclusive - reality is often a blend of elements from multiple strategies based on the specific market conditions and property lifecycle stage. At the end of the day, these are all attempts to find the market and maximize selling.
Did we miss any?
@joepohlen Eh, there's a range in SoCal. You can certainly get a lot higher than $10k, but there are plenty of nice/new options in the mid range.
And there are places in Dallas/Houston that are $10k+++.
Owner hates operator, operator hates owner. A tale as old as time.
The right senior housing operator partnership requires clear expectations on both sides. We facilitate productive agreements by defining performance metrics, reporting requirements, fee structures, communication protocols, and strategic alignment measures that prevent future misunderstandings.
The gap between property ownership and operational excellence in senior housing is real. While owners use brokers to sell properties and operators hire recruiters to find leadership, the critical matchmaking between owners and operators remains largely unaddressed.
This is why we're launching a seniors operator selection advisory . . . most of the non-core senior housing assets are paired with the wrong operator. Owners pick someone they know, or the people they met at the last conference, and that isn't the right crew for their asset.
This is why we're launching a seniors operator selection advisory . . . most of the non-core senior housing assets are paired with the wrong operator. Owners pick someone they know, or the people they met at the last conference, and that isn't the right crew for their asset.
American Dynamism is still alive in senior housing.
Many of the people who executed the (later) feats in this video live on in senior housing communities across the country. Walk in and you'll see veteran patches, NASA mission hats, and pictures of adventures most of us only dream about.
I view it as a highlight of my career to provide care for these great makers and doers of the last century.
Owners only want one than and it is...
...an operator who is aligned. Selling or refinancing might not be options, but a transition is. We’ve built our practice around this: finding the operator who’ll restore value and setting up the deal to make it stick. Let’s talk.
Sophos Equities advised on over $130M in senior housing loan originations in Q4 2024! Proud to bring clarity and expertise to a dynamic industry in a turbulent time.
Looking forward to attending ASHA next week to discuss senior housing acquisition and asset management. Please reach out to schedule time if I have not already set up a meeting.
🚨🌊Hurricane Helene Senior Housing Alert: If you are an operator who doesn't have evacuation experience, my lines are open to help. I performed disaster response through multiple hurricanes and wildfires for a national operator. Be smart.
“My IC has approved going hard on a distressed senior housing loan purchase on Monday morning. I know you are a senior housing expert - can you gut check my numbers?” (It was a Friday in the early evening.)
I received this call from a distant friend/colleague with this urgent question. Sub-institutional firm, but very well established in CRE.
He proceeded to describe the deal in generalities, and less than a minute in I had pinpointed which property he was referencing. They were using a best-case scenario, outdated cap rate study. Margins were overly optimistic. Their view of exits was . . . rosy. Layering in our realistic-but-not-doomsday metrics, he realized they were overpaying by 2-3X.
I’ve seen this scenario unfold too often recently. Senior housing is a phenomenal investment space when done correctly. However, it is challenging to do back-of-the-napkin analysis that comes close to the actual valuation. There are too many inputs relative to most other CRE product types.
Sophos provides both outside expertise and horsepower. We’ve consulted for multiple debt funds that like the space but wanted a specialist to opine, someone who lives and breathes senior housing every day unlike their generalist teams. We’ve also provided extra horsepower to teams with existing expertise who needed to work through organizational transformation, a lumpy transaction, etc.
(We're still buyers, but taking a Blackstone owner + advisory approach.)
"Find me a lender that says they don't have any distress in their portfolio, and I'll show you a liar."
. . . lender discussions while hunting for NPLs (lender's words, not mine). Chucked my crystal ball out the window a while ago.
Installation #1 – Asset Mgmt Advisory
(In response to many questions recently about what we do.)
Problem: There was a flood of owners who developed/acquired senior housing in the late 20-teens (or started devs that opened during COVID) who were not product specialists. The NAREIT index demonstrated healthy returns, and outside investors flooded in. Many of these underestimated the need to establish 1) good operating partners 2) with the right terms/structure. Or they elected to self-operate. These assets still have not stabilized and are in an environment where they cannot sell and cannot refinance. The operating environment is not getting simpler any time soon.
Solution: These assets need new operators who have tested their mettle during COVID (a lot of wheat/chaff separation occurred that was not obvious in the late twenty-teens) and can provide fresh operating excellence. @SophosEquities leads the operator selection process, budgeting process, and coordinates the transition (PR, systems, licensing, etc.). We also structure an incentive management agreement that aligns interests and meets owner goals (short-term refinance/exit vs. long-term hold). For those not in the industry, going with a friends’ friends’ operating company does not work. There is a dramatic level of market-by-market, asset-by-asset nuance. Owners need to ace the selection of the operator and transition/regulatory counsel (can be separate parties) and they have one shot at getting this right.
Common Objections:
1) “This process costs too much.” Call me back in 6 months then when you have lost that much or more, have a lender breathing down your neck, and now still need to pay for the transition.
2) “Why do I need to hire Sophos for this?” To quote The Social Network, “If you guys were the inventors of Facebook, you'd have invented Facebook.” In the year 2024 the time for action has been around for a while, and owners have one shot to get this right. We wouldn’t be having a conversation if this had been a self-fix issue.
3) “I self-operate and don’t want to give up the mgmt fee revenue.” Not sure your lender sees things the same way.
At the end of the day, senior housing is an ops business that happens to be wrapped/financed as real estate. Partner with the wrong operator, and the real estate is impaired. This is not a multi-family quick fix – these ships take time to turn. The best time to start would have been years ago, the second-best time is today.
I understand this is strongly worded, but it is the result of hundreds of conversations that are rooted in a denial of the current operating environment and capital markets realities. Only once the problem is identified can the solution be executed. We can work past these issues and partner to a stronger future.
Inspired by Barrett Linburg's post. There is a niche cabal of senior housing people on this platform that represent operators, investor, lenders, and service providers. I present to you the list of some of the toughest real estateurs on X.
This is separate from the private list I maintain that houses all of you lurkers. These are only the public ones. Follow along for industry insights and Joe Pohlen's famous bingo/poker nights.
https://t.co/ol7Gxhlmvp
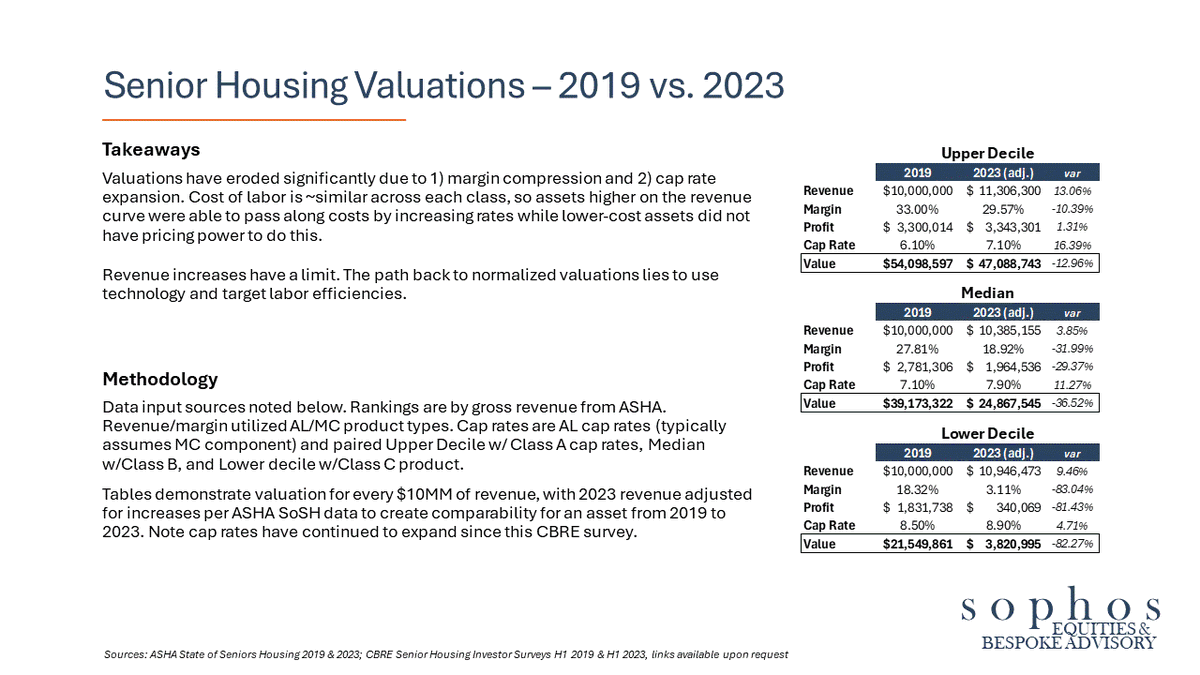
Macro pressures have driven valuations of seniors housing down over the last four years. This creates opportunity:
1) for acquisition of properties at a reset basis and
2) for owners to realign with the correct operator on their existing properties.