Not a financial advisor. Do your own DD and trade at your own risk. My posts are never buy or sell recommendations and are for informational purposes only.
I’m guessing this would be another one that gets litigated if they try to keep the termination fee. Considering the market, this probably has more upside than most other pre-DA SPACs.
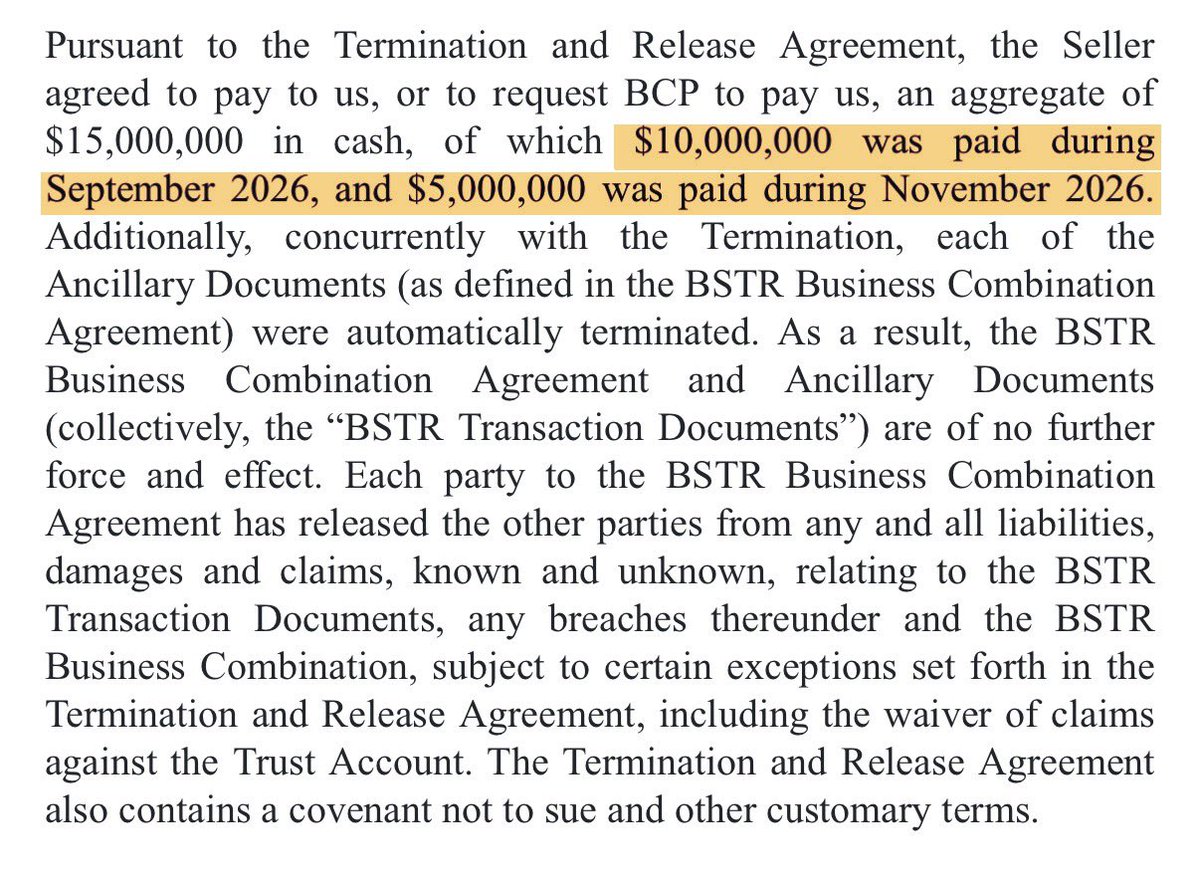
$CEPO is trading below its ~$10.86 NAV. I expect NAV to be ~$10.92 at the Jan 8th deadline. They received a $15M termination fee in Sep/Nov & unlike $DYNC, they did not say who gets it. Earn short-term treas rates + NAV discount & just 40% of the break fee would be another $0.30.
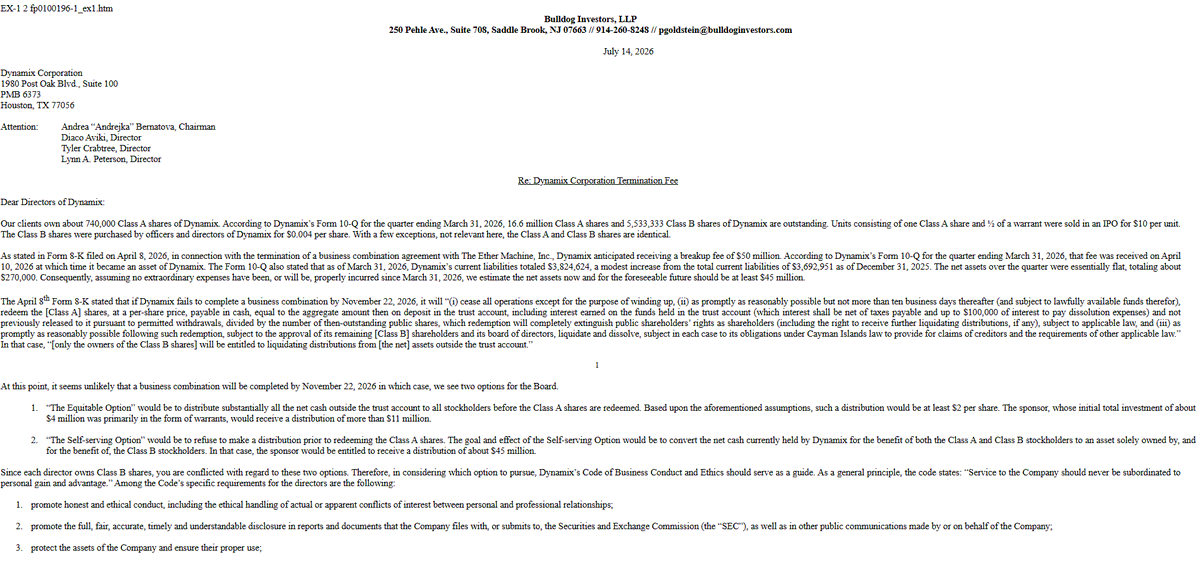
$DYNC should be interesting with a sub-2% risk for possible $1+ upside. Deadline is 11/22/2026 & I expect NAV to be ~$10.75 w/o breakup fee. Several SPACs have been litigated over breakup fees & settled in shareholders favor.
$BCSA $5M breakup fee $2.2M settlement (44% to trust.)
$AEXA is back near all-time lows and closest to NAV it’s been with a sub-2% premium above its ~$10.42 NAV. It was above $11 just a couple weeks back. It looks like one large ARB fund wants out today.
$AEXA is finally down to a more reasonable 2-3% NAV premium down from as high as an ~18% premium. It’s right around all-time lows and the closest to ~$10.40 NAV it’s ever been. I do like that it’s a warrantless SPAC that has options already.
$NTWO now has less than 20% of the float $AGLT has with 3M shares remaining after extension. They just raised an additional $20M 2 weeks ago from Mark Cuban and Tiger Global. Reversals aren’t possible, as the payment was made on the 3rd. It currently trades near its ~$10.86 NAV.
$CCXI now trades within 1% of its ~$10.30 NAV. I like the current R/R for possible press release upside in an attempt to mitigate redemptions or just an overall market bounce. The NAV redemption floor remains through the middle of next week.
$AEXA is finally down to a more reasonable 2-3% NAV premium down from as high as an ~18% premium. It’s right around all-time lows and the closest to ~$10.40 NAV it’s ever been. I do like that it’s a warrantless SPAC that has options already.
So far they haven’t filed for an extension. If they do without offering a distribution of the breakup fee to shareholders, I wouldn’t expect it to be approved.
$DYNC should be interesting with a sub-2% risk for possible $1+ upside. Deadline is 11/22/2026 & I expect NAV to be ~$10.75 w/o breakup fee. Several SPACs have been litigated over breakup fees & settled in shareholders favor.
$BCSA $5M breakup fee $2.2M settlement (44% to trust.)
$CND $20M breakup fee $13.08M settlement (65% to trust)
$FST $33M breakup fee $12.5M settlement (38% to trust)
$PACX $32.5M breakup fee $13M settlement (40% to trust)
If just 40% of the $50M goes to the trust, that would be an extra $1.20 per share at liquidation.
$WLCOW currently trades below $0.30, with targets including AI and robotics. They mention robot/robotics 28 times in their prospectus. I believe this is the cheapest warrant that mentions robotics as a target sector. The deadline is June 2028. High R/R. https://t.co/7f50KLl1Mz
$PTOR is currently my largest position. It trades $0.20+ below its ~$10.19 NAV. Targeting Automation/AI. OpenAI board member is a director. Former Inflection Point CFO and board member are on the team. Over $900K spend increase last quarter. https://t.co/A8hNvQ1nHn
The Churchill team has 2 other SPACs currently searching for a deal. $CXII which trades 6% above ~$10.05 NAV and $CCIX which trades near its ~$10.88 NAV, likely due to upcoming deadline. If we see an extension filing CCIX could catch up some with CXII plus its 13M shares smaller.
I expected an extension filing by now for $CCIX. We are 24 days out until the August 6th deadline. I’m personally leaning toward liquidation now but still have some commons since NAV is ~$10.89.
“Calcalist has learned that two Israeli quantum computing companies, Quantum Art and Classiq, are in advanced negotiations to go public on Wall Street through mergers with SPACs”. https://t.co/EvxjRzxo2i