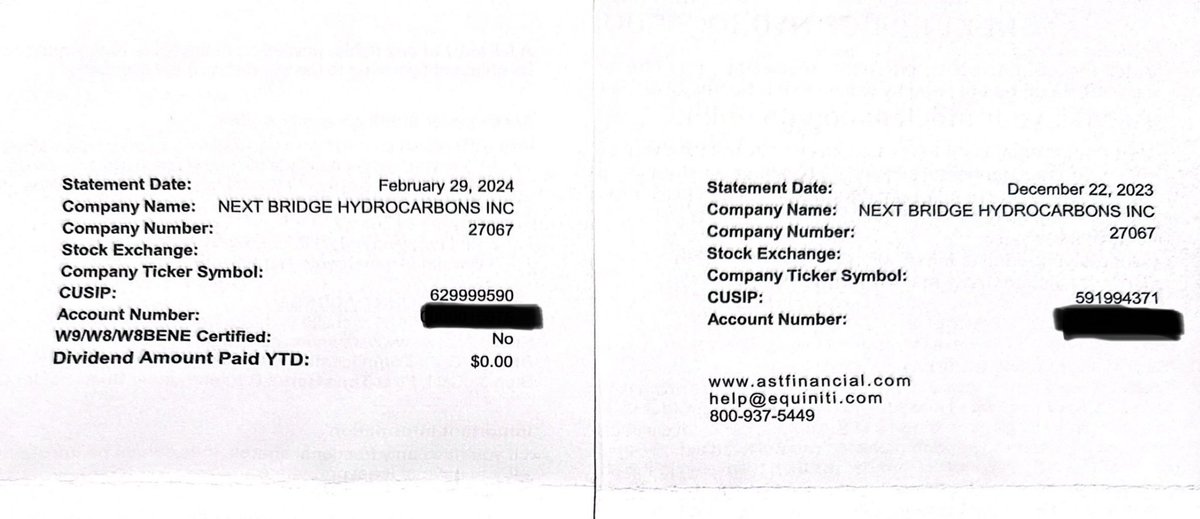
#MMTLP Have you heard of AST having 2 different cusip’s for nextbridge? They opened a second account for me and said it was because when E*trade sent over second batch they had my middle initial included. I was just looking at the statements and they have different cusip. December statement 591994371 and February statement 629999590. Both came from E*Trade. Wondering if anyone else has had this situation?
.@cvpayne 🖤
Thank you for your support of The MMTLP Army and our fight for transparency. You were there for us on Day 3...it's DAY 1412!!! #Relentless
Betting Greg McCabe gives better answers than "we'll see"....
MMTLP MMAT TRCH NBH
Next Bridge Hydrocarbons CEO Greg McCabe to appear on “Making Money w/ Charles Payne” on the Fox Business Network. We are pleased to announce Chairman and CEO Greg McCabe will be live, in-studio with Fox Business host Charles Payne for an interview this Monday, October 26, 2026.
Tune in to @FoxBusiness on October 26th at 2:00 PM EST!
@nbhydrocarbons CEO Greg McCabe joins @cvpayne live in studio on Making Money with Charles Payne to discuss the $MMTLP financial scandal. Don't miss it! 🇺🇸🫡
We’ve weathered the steepest drops and celebrated the highest peaks, but the true strength of the $MMTLP community has always been measured in our unbreakable patience all while knowing that the next wave of momentum is incoming.
So….it should be a good remainder of the week leading into the weekend trending.
🇺🇸🫡
FINRA and the SEC see what companies do to protect themselves and their investors as threats.
If Overstock and MMTLP are examples of just trying to cause a short squeeze (which courts have ruled is not illegal), you leave out the fact that illegal shorting/counterfeiting is what creates the conditions for short squeezes in the first place.
The irony is that if short squeezes occur, it shows that the regulators weren't protecting the company and their investors, so preventing short squeezes protects the reputation of the regulators.
$MMTLP #MMTLP 👀
The questions raised about Slocum deserve serious answers. What if there’s a connection nobody saw coming? It might explain a lot about Slocum’s obsession with MMTLP and McCabe. 🤔
Funny how the pieces start looking different when the right questions get asked.
"Conflict of interest" Interesting phrase, isn't it? 🤠
Especially when people are so QUICK to question everyone else's motives.
Or perhaps the more interesting words are MONEY, BUSINESS, LOYALTY and REVENGE.
Welcome to West Texas.
If you've watched Taylor Sheridan's LANDMAN, starring Billy Bob Thornton, you'll appreciate why I find the politics of the oil business, fascinating (and want nothing to do with it).
In smaller sized places like Midland, Texas, business relationships can span generations. Families know families. Competitors become partners. Partners become adversaries. And yesterday's commercial dispute can cast a long shadow over tomorrow's relationships. Reminds me the birthplace of Vendettas, ancient Greece (Crete and Mani).
Crete has a deep-rooted vendetta tradition, although “birthplace” is more poetic than historically precise. Blood feuds arose in multiple societies, including Crete and Mani (located South of Sparta).
The distinctly Cretan mechanism was collective honour: an injury to one person could be treated as an injury to the entire family. Responsibility, and the OBLIGATION to retaliate, could then pass across generations, with families alternating between victim and perpetrator. Anthropological research on mountainous Crete documents precisely that pattern.
Now, here's something worth examining.
Meet the Slocums.
In February 2022, Texas news outlets reported that Tom Slocum Jr., then running for Texas Railroad Commissioner, was a cousin of John Harvey Slocum, who was running for Texas House District 14.
Interesting family connection.
Now consider the historical court records involving VON Directional Services and VON Energy Services.
Federal litigation filed in April 2017 by Scientific Drilling International named both companies as defendants.
The docket subsequently recorded bankruptcy notices involving VON Directional in July 2018 and VON Energy in February 2019.
Another federal case identifies a John H. Slocum in litigation involving the VON businesses.
These are matters of public record.
And then we have Tom Slocum, who has been particularly vocal in his criticism of Greg McCabe, a central figure in the Next Bridge Hydrocarbons and $MMTLP story.
Here's where the conversation becomes educational.
When evaluating someone's commentary about a business dispute, I believe there are three important questions:
1. FOLLOW THE MONEY.
Who stands to gain or lose financially from the outcome?
2. FOLLOW THE RELATIONSHIPS.
Are there previous business dealings, professional associations, family connections or financial interests that might provide useful context?
3. FOLLOW THE HISTORY.
Have the parties previously been involved in commercial disputes, litigation or failed ventures?
These questions do not presume wrongdoing.
They help distinguish independent analysis from commentary/trolls/opinions that might be influenced by interests the audience cannot see.
And there's a fourth question that's sometimes overlooked:
WHEN DOES A COMMERCIAL DISAGREEMENT BECOME PERSONAL?
Anyone who has spent time building businesses knows that money and reputation can provoke powerful emotions.
A failed deal can destroy a friendship. A lawsuit can leave lasting resentment. A bankruptcy can affect an entire network of business relationships.
Occasionally, business disagreements can become personal vendettas, especially in smaller places like Sicily, Crete, Sparta, Midland Texas.
That doesn't establish that this has happened here. But it is precisely why understanding the historical relationships matters.
So, Tom, I have just a couple straightforward questions:
1. Are there any historical business dealings, financial interests or personal relationships relevant to your criticism of Greg McCabe that shareholders should understand?
2. Can we establish the complete history between the relevant businesses and individuals, rather than relying on selectively presented narratives? Specifically, is Mr J H Slocum your cousin (1st or other degree) by blood? Are you aware if G McCabe was one of the 99+ creditors that formed the committee to take Mr Slocum down?
Remember, i am not passing judgement here, just want to understand where you are all coming from.
If the answer and the data reveals no "conflict of interest", excellent! I will be more than happy to take this post down and issue an apology when requested.
THE BIGGER LESSON FOR SHAREHOLDERS:
Don't confuse opinions with credibility.
Don't mistake confidence for independence.
And never assume that the loudest person in the room is necessarily the one with the least at stake.
Investigate the incentives. Examine the documents. Understand the relationships.
Because sometimes the most important part of a story isn't what somebody is saying.
It's what they may have experienced LONG before they started saying it.
As for West Texas?
They've already made a television series about what happens when oil, money, family, POLITICS and business rivalries collide.
It's called LANDMAN.
And sometimes the real business world has more complicated relationships than anything Hollywood could ever write. 🍿
I'll leave just three public records and sources below (there is plenty more for those who want to look further).
1.https://t.co/bSrflPd8zB
2. KBTX reported during the 2022 Texas Railroad Commission Republican primary that “Tom Slocum, Jr.” was an engineering consultant and added that he was “the cousin of John Harvey Slocum,” who at the time was running for Texas House District 14. https://t.co/4FgkjoCSfd
3. the bankruptcy chronology is quite specific. VON Directional Services filed a voluntary Chapter 11 petition on July 9, 2018 in the Southern District of Texas, case 18-33794. It was converted to Chapter 7 on September 25, 2018 after the unsecured creditors' committee sought appointment of a Chapter 11 trustee and the parties instead agreed to conversion. Public docket summaries show the case as an asset case and record its eventual termination in April 2025: https://t.co/KOGij8t2iv
#MMTLP #MMAT #MarketIntegrity #BlueLedgerAI
ALL HAIL MegaTRAUDT, LEADER OF THE DECEPTICONS! 🤖 😂
Another victory lap, Supreme Commander? Brilliant!
But before you "transform" yourself into the champion of justice, there's a rather inconvenient question about which side you're actually fighting for. Let's talk about those conflicts of interest you are so concerned about...
Or are we watching the rather unusual spectacle of a prospective plaintiff auditioning for the defence?
There is a magnificent irony here. You are just publicly celebrating Authentix's lawyers attacking the Trustee and her litigation team, right?
AUTHENTIX, Scott.
The very party whose conduct and potential liability YOU may be expected to investigate and pursue, if you succeed in acquiring the estate's claims, right?
Let that sink in.
You're bidding to acquire litigation rights, after Spears solicited MMAT shares for your standing, supposedly to pursue accountability for shareholders (and don't forget the creditors), yet you're applauding the legal arguments of a potential defendant.
Now, I'm not suggesting you have struck some secret arrangement. Lets stop and consider how extraordinary that looks.
So let's apply YOUR conflict-of-interest test to YOU.
If you win the bid, will you pursue Authentix (and 24M) with the same enthusiasm you are currently displaying in attacking the Trustee?
What happens if the evidence leads directly to Authentix? Will you litigate aggressively, negotiate a convenient settlement (like the $70k you asked McCabe to pay you or the $650k that Spears asked Brda and McCabe for?), or quietly decide there's nothing worth pursuing?
Who exactly is funding your bid? Where is the $200,000 coming from, and who is underwriting the potentially millions more required to litigate?
Will your financial backers have any influence, approval rights or veto power over which defendants you pursue and how or when you settle, will the Trustee have any say?
Will you disclose all financial relationships and arrangements that could affect your independence?
Because from where I'm sitting, you're doing a remarkably good job of cheering on the very lawyers (who ALSO ARE REPRESENTING CITADEL as you are VERY well aware), you might eventually have to face across the courtroom.
If I were any of the defendants, I would be very pleased with your performance so far.
Now, about that little $3 million history lesson you offered your audience.
You mean In re Meta Materials Inc. Securities Litigation, Case No. 1:21-cv-07203, before Judge Carol Bagley Amon?
The securities litigation arising in substantial part from the short-seller report and allegations concerning the Meta–Torchlight combination whose only purpose was to manipulate our stock?
The one where, on September 29, 2023, a federal judge GRANTED our motion to dismiss ALL claims against ALL defendants, finding that the plaintiffs had failed to adequately plead a false statement or material omission, or a strong inference of fraudulent intent?
THAT case?
Yes, the parties subsequently settled. The announced $3 million covered TWO class actions, with at least $2.85 million expected to come from insurance.
MegaTraudt, you conveniently omitted both the dismissal and the distinction between settling litigation and admitting liability.
Funny how someone who professes such devotion to justice can be so selective with the facts.
For the record, I prefer to defend all such case through to its conclusions on the merits. But legal strategy, insurance considerations and obviously the "grand plan" of my removal by the MMAT Board behind my back in Oct 2023, who then offered settlement-hush money, to buy TWO years of my SILENCE, are not quite as entertaining as your storytelling. And trust me I have ALL the receipts.
Now, back to the important question.
You keep demanding that everyone else explain their relationships, lawyers, funding and motives.
Excellent. Let's start with yours.
You want to be trusted to pursue the estate's claims independently, you have asked for my help several times in the past, yet you're taking public victory laps alongside the arguments of lawyers representing a potential target. Hold on to you tractor there bud!
Perhaps there's a perfectly innocent explanation.
I'm all ears.
Because creditors and shareholders deserve someone prepared to follow the evidence, rather than someone who appears more interested in attacking the people currently pursuing it, including external counsel; the Trustee; forensic accountants; and key material witnesses (beyond myself)...
So, Scott: Who funds you? Who controls the litigation? And will these two defendants receive the same scrutiny you demand of everyone else?
Or, let me repeat: are we watching the rather unusual spectacle of a prospective plaintiff AUDITIONING for the defence? More than meets the eye, eh? 🤖
https://t.co/akzxsOBY40
PS> My best regards to Auxier, at least he served his country unlike others who profit from it like good mercenaries.
FIVE YEARS AGO TODAY. October 13, 2021. 🕵️♂️
Five years since the DELETION of FIGI identifiers and retrospective alterations to $MMAT's historical filing records, which was uncovered by one of our most tenacious shareholders (and BlueLedgerAI's co-founder & CEO) @tianastoddart 🔥TGGG
Five years later, the questions remain:
🔎 WHO authorised the changes?
🔎 WHAT exactly was removed, altered or reassigned?
🔎 WHEN were those changes actually made, and what do the original audit logs show?
🔎 WHY would historical securities identification records need to change retrospectively?
A FIGI is not just another ticker symbol. It is part of the infrastructure used to identify and reconcile financial instruments across systems, and was developed by Bloomberg @business
You can change a ticker. You can change a CUSIP. But you CANNOT simply rewrite history and expect nobody to ask questions.
If the changes were legitimate, the original records, timestamps, authorisations and audit trails should establish that.
If they weren't, the implications deserve serious scrutiny.
Five years. The records should speak for themselves.
Give @BlueLedgerAI and @tianastoddart a follow for more insights across all public issuer tickers and global identifier reconciliation.
$MMAT $MMTLP #MarketIntegrity
⏰THE MMAT 100-SHARE QUESTION🔥:
Inside an Attempt to Acquire Bankruptcy Standing in the Meta Materials Case.
An unusual seven-page stock transfer package, an urgent solicitation, and a shareholder willing to go on the record raise questions about WHO was attempting to acquire INFLUENCE in a multimillion/billion-dollar bankruptcy proceeding....and HOW.
A curious proposition:
On May 10, 2026, an MMAT shareholder says he received an unusual proposal from none other than...
Danielle Spears.... who, based on the attached docs, was allegedly acting on behalf of... you guessed it... Scott Traudt 🤣😂
The objective, according to Spear's message and the attachment (see below) was not conventional investment:
“I found a way for you to sell me 100 of your shares so I can have automatic standing in the bankruptcy. Please let me know if you are willing. I'll pay you above market value just to have them”
The proposed quantity was modest: just 100 shares in Meta Materials Inc., but the stated objective is anything but ordinary.
The shares were being sought, according to the message, to obtain standing in federal bankruptcy proceedings.
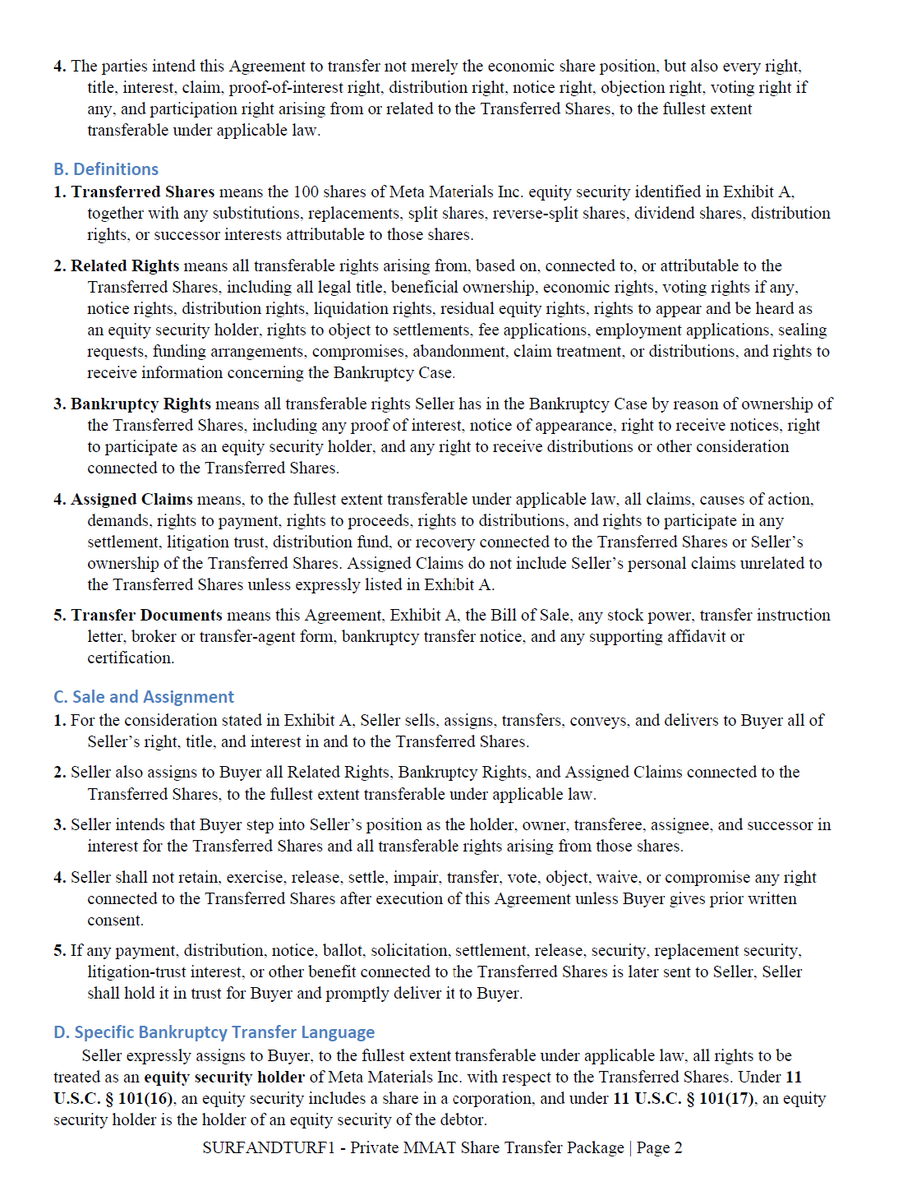
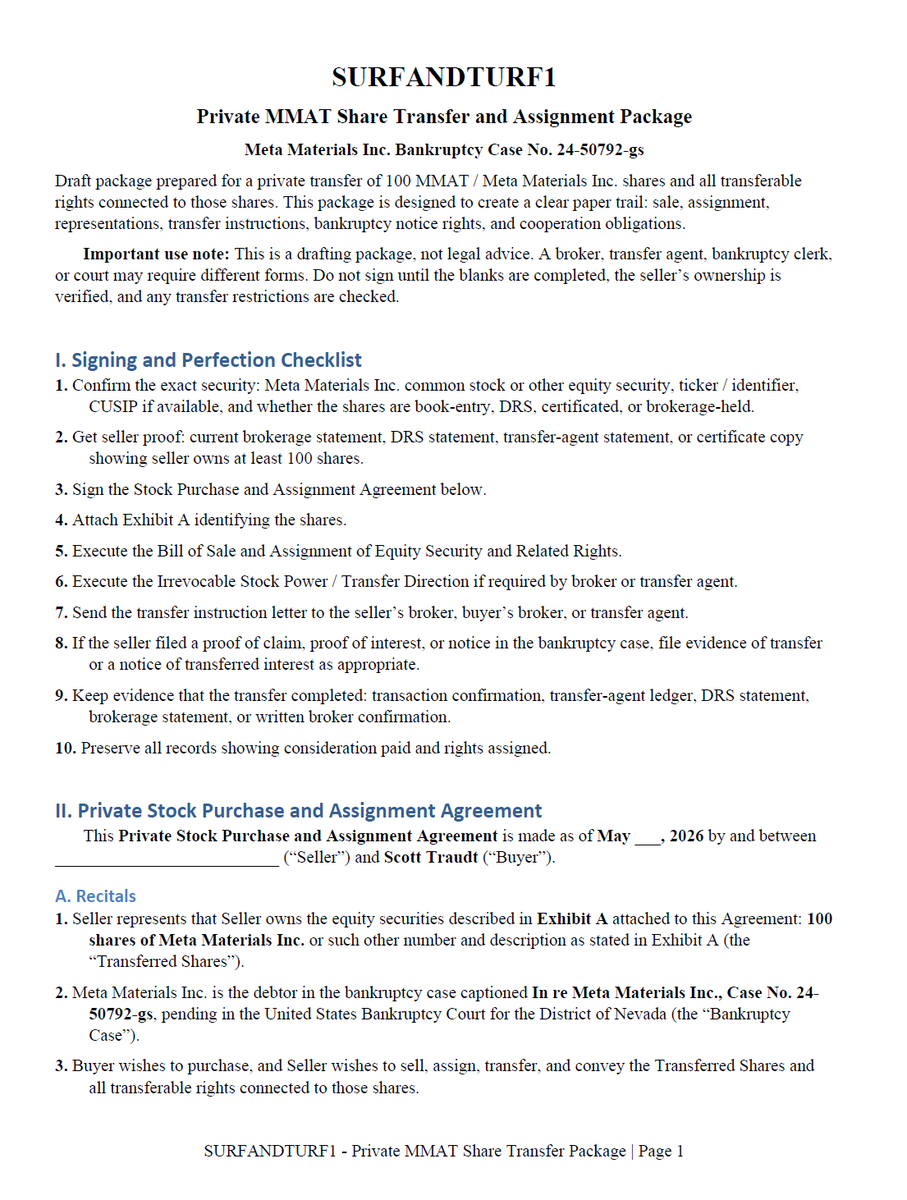
Spears also supplied our shareholder directly with a seven-page document titled:
"SURFANDTURF1 — Private MMAT Share Transfer and Assignment Package".
SOURCE for the full PDF: https://t.co/8Qqz0rYMaS
Unlike the message referring to shares being sold to Spears, however, the document identifies a different purchaser: Mr Traudt.
Q: Who was actually supposed to buy the shares, Spears, Traudt or someone behind the scenes who is acting through them, and what is the relationship between them?
The document shows this is more than a simple stock purchase... see for yourselves.
The SURFANDTURF1 package is dated for execution in May 2026 and identifies the buyer as Scott Traudt.
Its structure is unusually expansive for a transaction involving 100 shares.
The proposed agreement seeks not only the securities themselves but also a collection of TRANSFERABLE RIGHTS associated with the MMAT's bankruptcy proceedings.
These include rights to receive notices, participate in proceedings, object to settlements, challenge fee applications, address funding arrangements, and pursue certain claims or distributions.
The agreement attempts to transfer these rights to the fullest extent permitted by applicable law.
Separate exhibits provide a bill of sale, stock-transfer instructions, a proposed notice for filing with the bankruptcy court, a seller certification, and a buyer's reservation of rights.
The package even addresses how the buyer might respond if the trustee CHALLENGES the acquisition as an attempt to manufacture standing.
On page seven, the author (Traudt? Spears? a 3rd person?) supplies suggested arguments for responding to precisely that objection.
The document is not simply concerned with whether 100 shares can move from one account to another.
It is concerned with what the buyer might subsequently be able to do in court.
An urgent Wednesday deadline:
Additional messages by Spears reinforce the apparent emphasis on bankruptcy participation.
“I need shares immediately” one message states.
Another adds: “We need to get it done this week, filed by Wednesday if possible”
These messages were exchanged on May 10 and so the Wednesday referenced would have been May 13, 2026.
Why that date mattered will be interesting to discusss since the deadline corresponded to a specific hearing, planned objection and anticipated filings in the bankruptcy case.
The messages indicate urgency. They also suggest that obtaining and documenting the shares was viewed as a prerequisite to some anticipated bankruptcy activity.
The precise nature of that activity remains an important unanswered question.
The metadata connection:
A forensic examination of the supplied PDF identified an embedded creation date of May 10, 2026.
Its creator and producer metadata identify PDFium, a PDF generation engine commonly associated with Chromium-based applications.
The document contains no named human author.
The creation date is significant because it corresponds to the date of the solicitation reported by the MMAT Shareholder.
The combination of the recorded creation date, the intended buyer's name, and the MMAT Shareholders' account of receiving the document directly from Spears supplies a testable chain of evidence.
The regulatory question: Was someone acting as an unregistered broker?
The communications raise a separate securities-law question.
Section 3(a)(4)(A) of the Securities Exchange Act of 1934 defines a broker, broadly, as a person engaged in the business of effecting securities transactions for the account of others.
Section 15(a) generally requires qualifying brokers to register, unless an applicable exemption or exception applies.
Was Spears tricked into a potential Section 15(a) violation by Traudt, or was she a willing participant, and was she compensated for her "work"?
The distinction is important.
A private individual buying shares for their own account is not necessarily acting as a securities broker.
An unpaid individual helping arrange a single transaction is also not automatically required to register.
But repeated solicitation of shareholders (our MMAT Shareholder was one of at least three others), negotiation of purchases, participation in completing transactions, or acting as an intermediary for another purchaser can become HIGHLY relevant to the broker-registration analysis, and a whistleblower report.
Here, the proposed purchaser named in the written agreement is Scott Traudt, while the solicitation described by the MMAT Shareholder was allegedly communicated by Spears.
That creates legitimate questions:
1. Was Spears soliciting shares for Traudt or for herself?
2. Who prepared and approved the acquisition package?
3. Were other shareholders approached using the same document? (I know of at least 3).
4. Were any purchases completed? (We already now know that Traudt has acquired shares from Auxier)
5. Did Spears receive compensation, reimbursement, a prospective benefit, or any other consideration?
6. Did anyone involved hold the registration required for the activities actually undertaken?
These questions do not establish an unregistered-broker violation... yet.
They identify matters that could be examined by the @SECGov and local securities regulators if corroborating evidence establishes activity within their jurisdiction.
A broader contradiction:
The timing of these disclosures is notable.
In recent public posts, Traudt has sharply criticised the Meta Materials Chapter 7 trustee, questioned proposed litigation-claim transactions, and accused several individuals associated with the $MMAT and $MMTLP controversies of improper conduct.
In one post concerning today's October 13 bankruptcy hearing, Traudt characterised the trustee's proposal as an effort to "give Greg McCabe another $45 million".
He also publicly described his intention to object and advance alternative proposals.
The contrast is worth examining...
Traudt has demanded scrutiny of others' motives and financial arrangements.
At the same time, a document naming him as purchaser expressly seeks to acquire bankruptcy-related participation rights through a proposed 100-share transfer.
Did he know of the shareholder solicitations?
Did he authorise them?
What procedural advantage, if any, was intended?
SIDENOTE: i had no idea that bankruptcy standing can simply be... purchased⁉️⁉️⁉
The mere existence of an executed private agreement does not automatically entitle the buyer to EVERY right claimed within it.
There are differences between OWNING an equity security, being A RECOGNISED HOLDER, asserting a transferable LEGAL CLAIM, and demonstrating STANDING to seek particular relief.
Furthermore, a seller cannot transfer rights they do not own, including claims that may belong to the bankruptcy estate itself.
That distinction is particularly relevant to "SURFANDTURF1".
The package attempts to assign a broad array of claims and procedural rights, but its own language repeatedly acknowledges that transfers are limited by applicable law.
A bankruptcy court would therefore need to evaluate the actual completed transaction and the legal basis for any specific standing or participation asserted.
THE WITNESS:
Our MMAT Shareholder indicated that he is willing to provide an on-the-record account of the solicitation and document transmission and i have connected him to the trustee along with the evidence.
That is important.
An authenticated original conversation and a sworn declaration could establish what was said, who sent the proposed acquisition package, when it was transmitted, and whether additional representations were made.
Such evidence could assist the Chapter 7 trustee in determining whether further inquiry is warranted.
It could also support a referral through the SEC's established reporting channels, should the facts raise a credible concern about an applicable securities-law violation or even a deferral to the DOJ if there is more nefarious coordination happening behind the scenes with the "real" sponsors.
The materials reviewed for this report do not establish that regulators have opened an investigation or that any party has been found to have violated securities law.
The questions that now demand answers
The existence of SURFANDTURF1 is UNDISPUTED as a matter of the supplied document's contents.
The PDF names Scott Traudt.
It proposes the acquisition of 100 MMAT shares.
It seeks associated bankruptcy participation and objection rights.
It contains a ready-made court notice.
And it anticipates the possibility that someone will challenge the transaction as MANUFACTURED standing.
Our Shareholder's reported account adds a second dimension: direct delivery of the package by Spears and communications explicitly discussing acquiring shares for bankruptcy standing.
Together, these materials justify a very close examination of the acquisition arrangements.
The central questions are no longer merely theoretical.
Who authorised the solicitation?
Who was the intended ultimate purchaser?
How many shareholders were contacted?
What transactions were actually completed?
And how were any acquired interests subsequently presented to the bankruptcy court?
I would take it a step further:
It would be great to know TODAY at the hearing, where did the $200k ($100k x2) that Traudt put forward as an offer for the two cases come from? His own money? Can he show us the bank transfer into the LLC?
These are questions the relevant parties can answer, and that the trustee or the regulators can assess against original evidence.
THE BOTTOM LINE:
FOLLOW THE SHARES. FOLLOW THE MONEY. FOLLOW THE MOTIVES.
One hundred shares. Seven pages of legal documentation. A proposed bankruptcy strategy. An urgent filing deadline. And a witness prepared to speak.
For a transaction involving an apparently negligible economic interest, that is a remarkable amount of machinery.
But perhaps we have been asking the wrong question.
Is this really about protecting MMAT shareholders? Or are these efforts creating additional disputes, delaying the administration of the estate, and consuming resources that could otherwise be directed towards pursuing those responsible for its losses?
In my opinion, repeated procedural battles and related legal activity may already have cost the bankruptcy estate more than $500,000 in professional time and expenses, putting the massive Billion-dollar+ stock manipulation case against Citadel, Virtu and Anson at jeopardy.
That is my estimate, not an independently audited amount attributable to any particular individual. The trustee's fee applications and billing records deserve examination to determine what these disputes have actually cost.
And if those costs are substantial, shareholders deserve to know whether they have affected the economics of the trustee's decision to sell the Authentix and 24M litigation claims.
The proposed transaction would provide the estate with $250,000, plus 20% of net recoveries after specified expenses, while transferring responsibility for future litigation costs to the purchaser.
Was that the best possible commercial outcome? Were alternatives available? And how much of the trustee's resources have been diverted into dealing with procedural disputes rather than prosecuting recoverable claims?
Those are serious questions.
Personally, I wish I had the capital to submit a competing bid for those litigation claims, pursue them commercially, and structure the recoveries to maximise the estate's benefit.
Because that should be the objective.
Recover value. Hold responsible parties accountable. Maximise distributions.
Not simply generate another round of expensive legal arguments.
And what about Greg McCabe?
Conviction. Interesting word. A few months ago I was told to check out the Fort Worth SEC's "team of accusers"... the ones who put this "novel" case together... with a simple search on LinkedIn.
They have ALL since magically disappeared from their positions. But they did not get promoted. Most were fired, and at least one could not get a new job. That tells me all I need to know about THEIR conviction.
On the other hand, I impatiently await my day in court, with none of these "originators" around to face me, while they try to keep everything under a seal... how convenient... now that i have access to my laptop with all the corporate communications. But that's ok. Once all this is behind us, we will deal with the internet foot soldiers, trolls, and their bosses. This is a complex case, and we are only scratching the surface.
Now... for some true DOJ "conviction" I am keeping a close eye on the (incredible) Atlas Trading case, which touches many stocks including $MMTLP/ $TRCH. Those boys declared victory after winning in court for allegedly defrauding their fellow retail investors (~$100 million actually found/gained in their combined accounts), while one of their crew members pleaded guilty.
PS.1: Did you know? According to some legal industry experts, "novel" cases are launchpads to transition into a bigger career in the legal industry, where they get to charge $1000+ per hour to defend those who they were once ligating against, on the exact same topics (e.g. recent crypto cases)...
PS.2: We all know how "convicted" short sellers are... you got to love their passion... especially after they pay 3rd parties to manipulate stocks with fake reports (not applying a real long/short strategy, but applying a simple disclaimer that washes all their sins under US law) while their hedgefund buddies guarantee success using spoofing, front running and other illegal actions off the exchange. You only need to look at the multiple cases against Anson, including the class action lawsuit brought forward against them by the MMAT Trustee... Makes you wonder how much $$$/hr does "conviction" sell for these days?
or is it sold $$$ per post? 🤣perhaps $$$ per space call?🤣 It is money funneled through intermediaries and offshore accounts. It's a well oiled machine operating for decades, globally.
The MMTLP community and the MMAT trustee are already cleaning up after their mess, and now @BlueLedgerAI enters the arena. More to follow!
PS.3: Very much looking forward to next week.
As a Greek, I must say, the backdrop is hard to beat 🇬🇷
But beyond the magnificent Parthenon and Acropolis, (love him or hate him) @SecRubio's words on duty, honour and sacrifice resonate deeply with anyone who has served, anyone whose family lives with the cost of service.
I just returned from DEFSEC Atlantic and was reminded that those of us in Aerospace & Defense are working hard to make sure our men and women in uniform come home safely.
The ancient Greeks gave us the vocabulary of heroism. Our servicemen and women remind us what those words actually cost.
Some lessons are 2,500 years old. Others are learned every single day. Have a blessed weekend.
FINRA @FINRA and the SEC @SECGov both have mission statements of “protecting investors”, yet they’ve gone out of their way to shield institutions that have knowingly harmed investors. MMTLP proves how far they’re willing to go to “protect”.
Zero accountability. Zero transparency.
Next Bridge Hydrocarbons @nbhydrocarbons has irrefutable evidence of ongoing securities fraud in the distribution of UNREGISTERED, COUNTERFEIT SECURITIES. CEO Greg McCabe has requested numerous meetings with the @SECGov@SECPaulSAtkins.
SEC's repsonse: 🦗🦗🦗
MMTLP....Elon knows!!!
Dear @VP:
Yes! 🤝 Drill Baby Drill‼️
But undo the 4 years of regulatory robbery that took place under Gary Gensler? @SECGov 👇
$MMTLP is an American travesty, right? It’s time for answers. Make it right! 🙏 Defend the future of American Investments! 🇺🇸
https://t.co/tkBPGFkijZ