As you should know by now, we called the top and the bottom on $ASTS
The correction has been clean and the structure looks healthy
Now I see the possibility of primary Wave 3 starting Target: $259, a +330% move from current levels
The only thing that would invalidate this is a new lower low under $52
NFA
$LEU is currently the answer to the future US nuclear supply chain
Within nuclear power, the focus is shifting to SMRs over classical nuclear plants due to
• Lower upfront costs
• Faster build times
• Passive safety systems
Companies such as:
$OKLO
$NNE
$BWXT
. . .
Require a material whose supply chain is still underdeveloped
→ HALEU: high-assay low-enriched uranium (enriched between 5% and 20%)
$LEU is currently the main answer to that problem
Today, Centrus is mainly a nuclear-fuel merchant
It buys enrichment from suppliers such as TENEX and Orano, then sells:
• SWU enrichment services
• Uranium
• Enriched uranium product
Under medium and long-term contracts with nuclear utilities
Currently profits are driven by the existing LEU business
The future thesis is that Centrus transforms from a merchant into a domestic producer of:
• LEU for existing reactors
• HALEU for advanced reactors (very limited qualifications)
• US-origin uranium for national-security missions
Centrus’ qualifications are difficult to replicate:
• Only US facility licensed to produce HALEU
• Only deployment-ready US-origin enrichment technology
• Operating 16-centrifuge demonstration cascade
• >1,900 kg of HALEU UF6 produced
• Existing facilities in Ohio and Tennessee
• Fluor as EPC partner
But the demonstration cascade is not yet a commercial plant
The biggest challenge is moving from 16 operating centrifuges to the high-rate manufacturing and operation of thousands
The expansion plan targets:
• First new capacity: 2029
• HALEU capacity: 12 MT/year sometime after 2030
• Additional LEU capacity to support existing reactors and feed the HALEU cascades
They got a $900M fixed-price DOE HALEU contract which was bullish for funding
Commercial validation is building:
• X-energy: Definitive LEU + HALEU agreement with prepayments and deliveries beginning in 2030
• Oklo: LOI covering up to 5 Aurora powerhouses with potential deliveries from 2029
• Oklo: Exploring a HALEU deconversion JV beside the Piketon plant
• TerraPower: MOU supporting the Natrium reactor
• KHNP + POSCO: Exploring investment in the Ohio expansion
The reported backlog is $4.5B, but it needs to be separated:
• LEU backlog: $3.7B
• Contingent expansion commitments: $3B
• Definitive but still contingent: $2.4B
• Existing non-contingent obligations: roughly $700M
• Technical Solutions backlog: $800M (should be partly discounted)
That final $800M should be heavily discounted because DOE does not currently intend to exercise the old HALEU production options
The potential is enormous if Centrus becomes the US-owned supplier serving commercial reactors, advanced reactors and national security
The stock has pulled back significantly, are you bullish $LEU?
We called the start of Wave 3 on $NBIS at $98
We called the top of Wave 3 at $279
We mapped the Wave 4 levels and the pullback played out perfectly, bouncing right off the 0.618 fib
Now I expect the move to Wave 5
Target: $407
The whole structure mapped from the beginning
Not bad
NFA
35K followers
That was our end of year goal for 2026
We reached it in September
When I started this account I was just a guy from Spain who believed retail investors deserved better
Better analysis, better education, better tools
And somehow, you found me
This number means more than I can put into words
Because behind every follow is a person who trusted me with something important, their time and their attention
I don't take that lightly, I never will
New goal: 80K by end of 2027
We're just getting started
Thank you, every single one of you 🙏
SC
$GRAB broke down lower
And now it's sitting at important support, with a valuation of
• 3.3x PS
• 26.7x PE
$GRAB is essentially the "Uber + DoorDash + a neobank" of Southeast Asia
They operate on 3 core pillars
DELIVERIES
→ GrabFood
→ GrabMart
→ GrabExpress
→ GrabAds
MOBILITY
→ GrabCar
→ GrabTaxi
→ GrabBike
→ Corporate mobility
FINANCIAL SERVICES
→ Lending
→ PayLater
→ Insurance
→ Payments
→ Digital banking
The expansion vectors are well known
• Taiwan → first market outside Southeast Asia if foodpanda deal closes
• Autonomous vehicles → Grab targeting thousands of AVs with partners by 2030
• Superbank → Grab now controls >50%
There are also rumors of a possible GoTo merger (not confirmed)
A Grab + GoTo combination could control 90% of Singapore and Indonesian ride-hailing
• Thought this comes with regulatory risk
What are your thoughts on $GRAB?
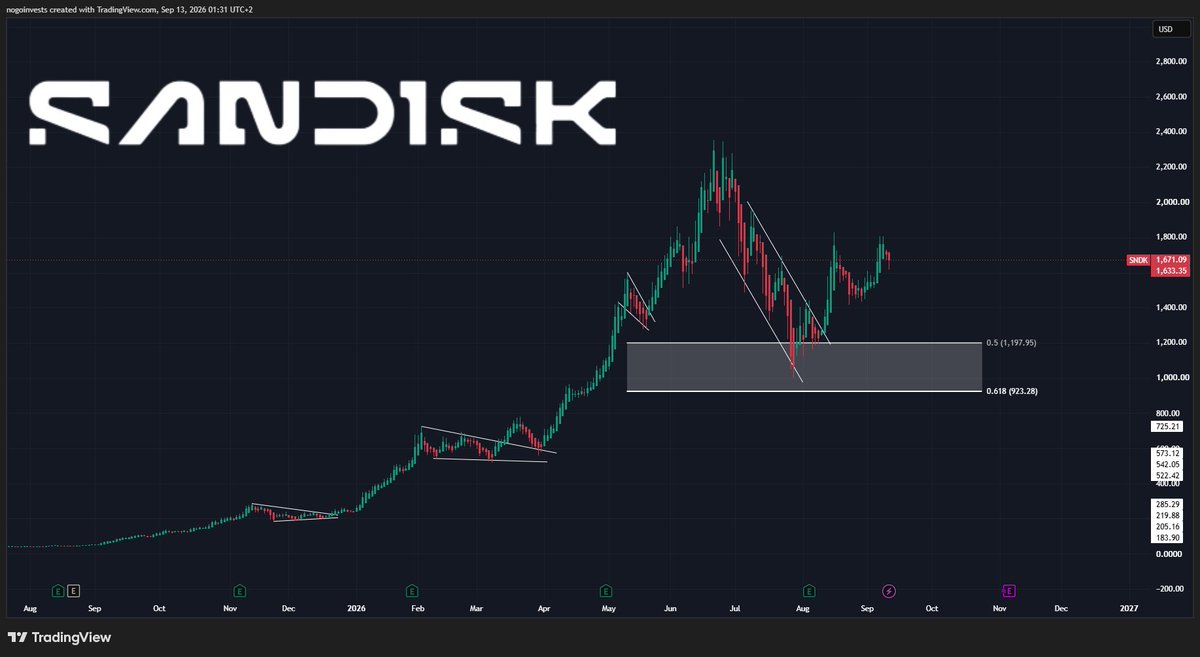
$MU vs $SNDK: both trade near 7x forward earnings
The question is clear: cheap or a peak-cycle trap?
Memory contract exploded (and continue to climb):
• Q1: DRAM +90–95%, NAND +55–60% QoQ
• Q2: DRAM +58–63%, NAND +70–75%
• Q3E: DRAM +13–18%, NAND +10–15%
Since Q4 2025, it implies roughly
• DRAM: +239–275%
• NAND: +190–222%
Micron’s latest quarter:
• DRAM pricing: +low-60s% QoQ
• NAND pricing: +mid-80s%
• Gross margin: 84.9%
• Next-quarter revenue guide: $50B ±$1B
Sandisk:
• Revenue: +51% QoQ
• 2/3 of growth came from pricing
• Datacenter revenue: +103%
• Gross margin: 84.6%
• Next-quarter revenue guide: $10.3–10.8B
Compare that with the normal 20-40% non-peak margins
This pricing is what is causing earnings to explode and continue to climb sharply
• $MU: 22.0x PE | 6.8x forward PE
• $SNDK: 22.1x PE | 7.6x forward PE
The most important information to answer the question is visibility beyond 2026
Micron expects both DRAM and NAND conditions to remain tight beyond calendar 2027
It has signed 16 take-or-pay customer agreements, generally running through 2030:
• Cover 20% of DRAM volume
• Cover 1/3 of NAND volume
• 14 agreements represent $100B of minimum contracted revenue
• Backed by $22B in deposits and financial commitments
• Pricing floors are designed to support gross margins well above Micron’s peaks in previous cycles
Sandisk has also signed long-term agreements with eight customers:
• Cover 50% of FY2027 bits
• Cover 2/3 of FY2028 bits
• Include committed volumes
• Structured pricing mechanisms
• Minimum financial guarantees
This means that even though these are peak-cycle margins, they are expected to continue into 2027-2028
Would you own $MU and $SNDK
Everyone is talking about the CLARITY Act
But what does it ACTUALLY change for crypto?
The biggest issue it tries to solve:
SECURITY
vs
COMMODITY
For years, crypto companies haven't had a clear answer on which regulator controls what
CLARITY would create a framework where:
• SEC → token fundraising + investment contracts
• CFTC → spot markets for qualifying digital commodities
• Exchanges → registration + custody + customer-protection rules
• Issuers → clearer disclosure + fundraising requirements
• DeFi → clearer rules around when intermediaries fall under regulation
Why is this important?
Because regulatory status determines:
→ Who can issue tokens
→ Where they can trade
→ Which exchanges can list them
→ What disclosures are required
→ Which regulator has jurisdiction
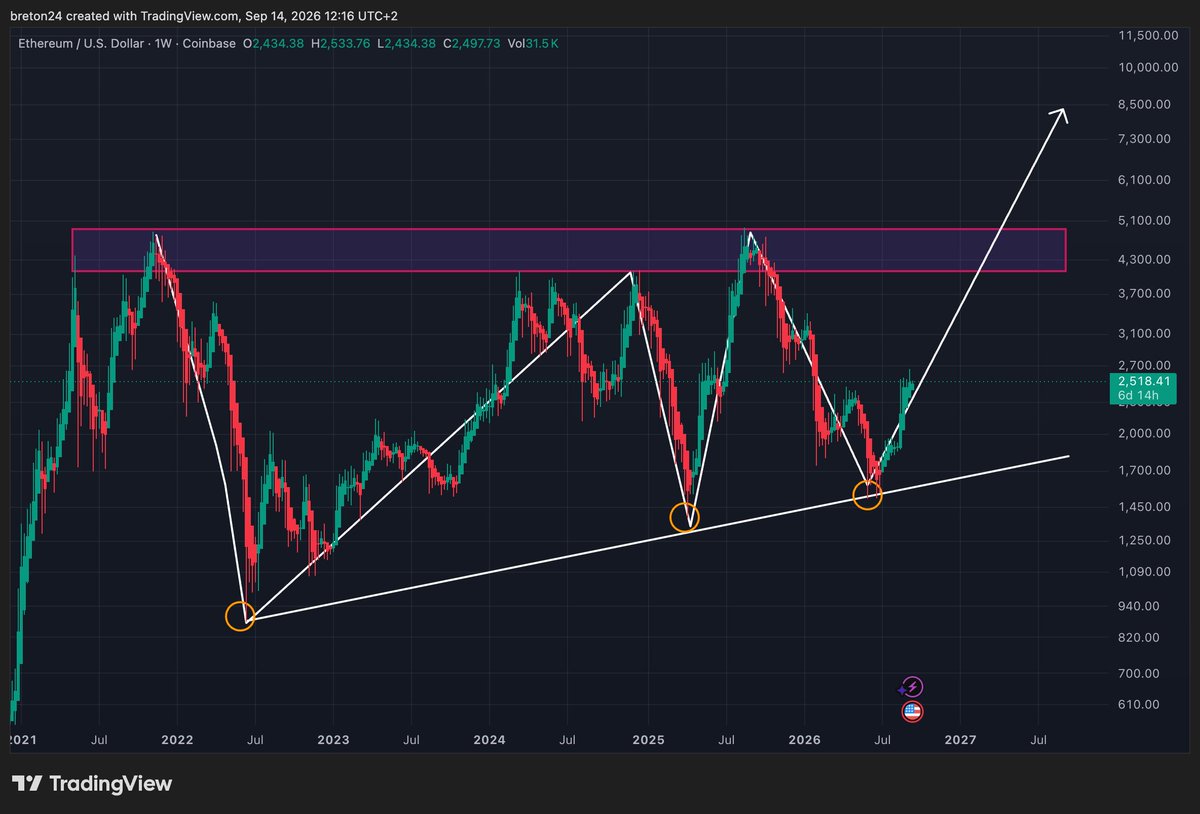
This could create a regulatory pathway for assets such as $ETH, $SOL and $XRP to be treated as commodities
The House already passed it 294–134
Now the Senate needs 60 votes to advance it on September 15
If it passes, it would be the biggest structural changes crypto has ever seen
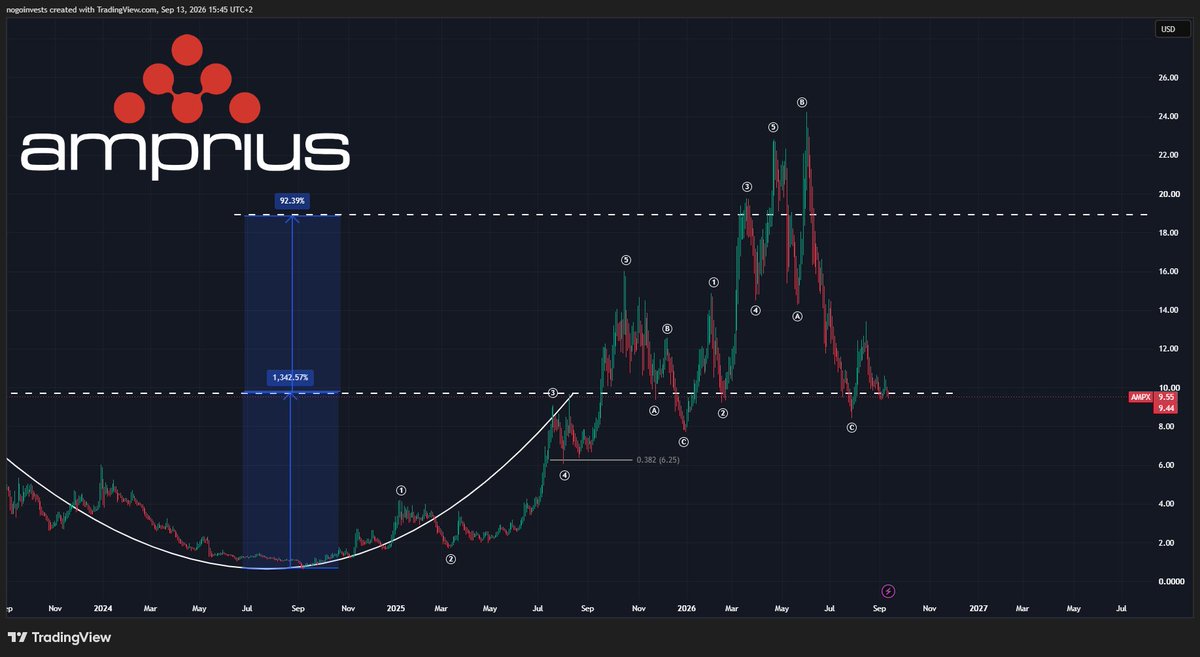
$AMPX didn't just reach the cup-and-handle target, it went even higher
Now price has pulled back to a better valuation
And unlike many “next-generation battery” companies, Amprius already has positive gross margins at its scale
Amprius silicon-anode cells can deliver:
• Up to 500 Wh/kg
• Longer drone flight times
• Higher payload capacity
• Rapid charging
• Much higher energy density than conventional graphite cells
But the KEY is understanding its two platforms:
SiMaxx
→ Proprietary silicon-nanowire technology
→ Extreme performance
→ More specialized manufacturing
SiCore
→ Conventional manufacturing equipment
→ Outsourced production
→ >2GWh annual capacity access
SiCore is the real growth engine today
Recent commercial wins:
• $24M European drone order
• $21M electric-mobility order
• $100M+ multi-year agreement with Stark Future
• $18.1M Defense Innovation Unit contract
$AMPX is currently trading at 9.9x end-2026 revenue
What are your thoughts?
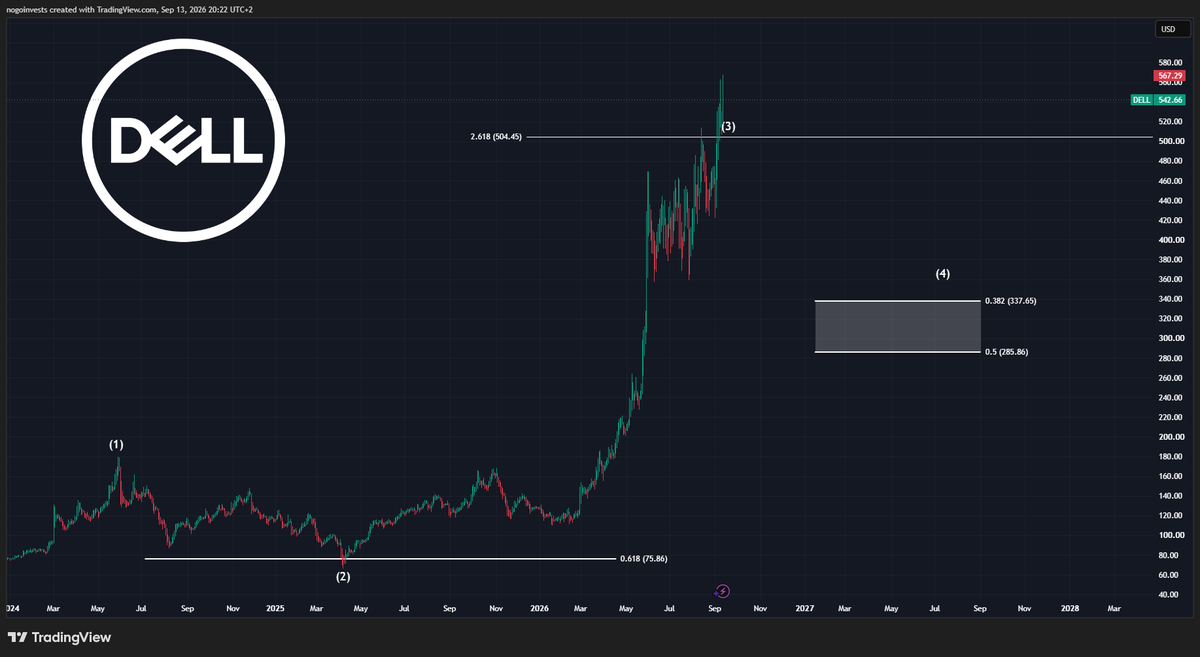
$DELL ended up reaching our extended wave 3 target
From our first mention in January 2025: +425%
The move went much futher than we expected
The original turnaround thesis was simple: AI server demand which
• Re-accelerates growth
• Recovers margins
Q1 + Q2 FY27 were the strongest accelerants
Q2:
• Revenue: $46.97B, +58% YoY
• Adj. EPS: $7.04, +203%
• GAAP gross margin: 20.9% vs 17.8% Q1
AI data-center
• AI-server orders: record $60.9B
• AI-server revenue: record $16.4B (+100% YoY)
• AI-server backlog: record $95B (+85% QoQ)
• Traditional servers/networking: $10.5B (+122% YoY)
• Storage: $4.85B (+26% YoY)
Guidance was also raised higher
• FY27 revenue: $167B → $192B
• FY27 AI-server revenue: $60B → $74B
• FY27 non-GAAP EPS: $17.90 → $25.50
After the push, we are more interested in a retracement lower
Do you think $DELL goes lower or higher first?
Weekly recaps dropping today, and this week is special
35% OFF ANNUAL, NO CODE NEEDED, EXPIRES SEPTEMBER 18TH
Deep technical + fundamental analysis on:
$SPY
$GRAB
$CRWV
$BABA
$TE
$SOFI
$CIFR
$AAOI
Link in bio
$TE is down 40% over the past six months
Now check institutional ownership over that same period
They've been loading while price has been falling
Cheap shares, smart money accumulating
NFA
$NIO showing an initial good reaction at the 0.887 fib level
If it continues holding here, this could be the bottom
Next target: a move toward the 50 MA
NFA
Nearly nobody is talking about the opportunity $NFLX is offering at current levels around $70
For me it's a no brainer long term
I'll be quoting this tweet one day
Remember this
NFA
Most people watch price action all day
And wonder why they can't hold anything long term
Because every time you watch, you give the price permission to change your mind
Conviction isn't built by watching price action
It's built by doing the research before the move, and trusting it when the price moves against you
Watch your thesis, not the price
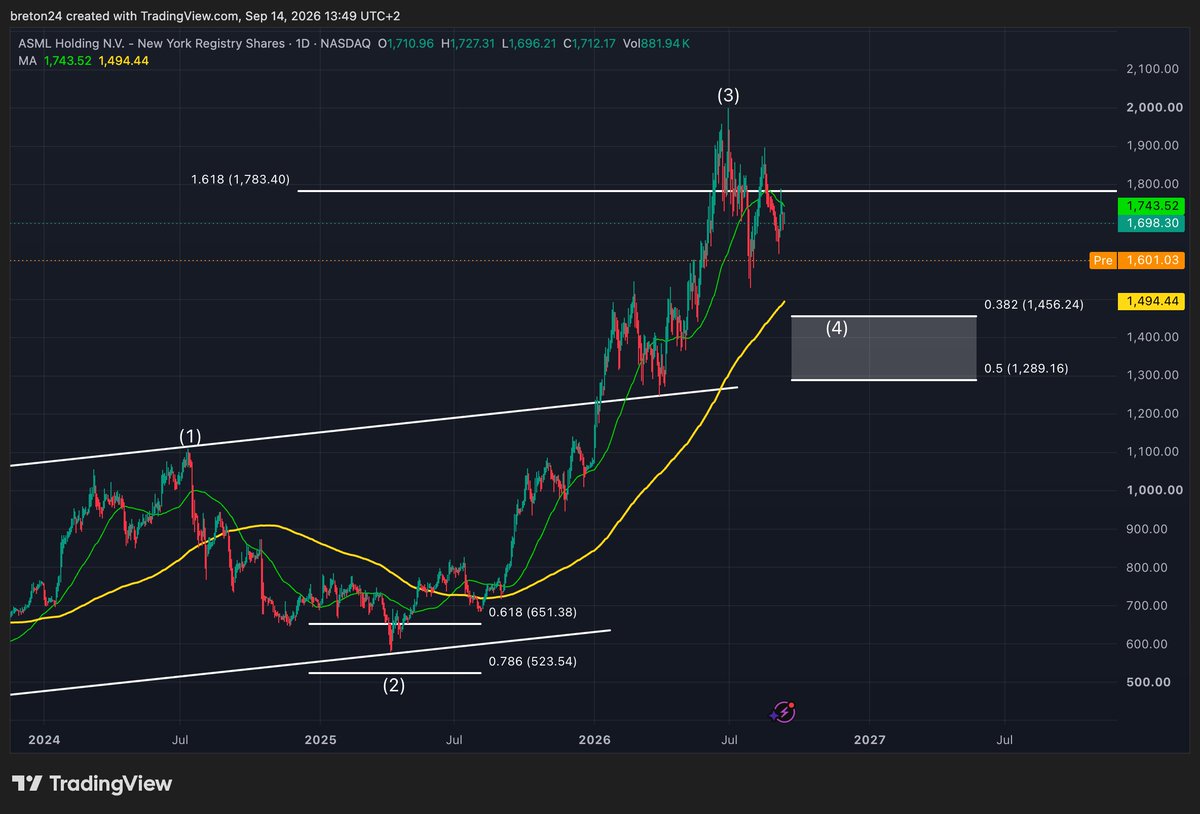
$ASML reached our Wave 3 target, a +150% move since we shared the chart
It has since pulled back, which is exactly what we expected
Wave 4 corrective move in play, this is healthy structure
The levels I'm watching for the correction:
The 0.382 and 0.5 fib levels
NFA