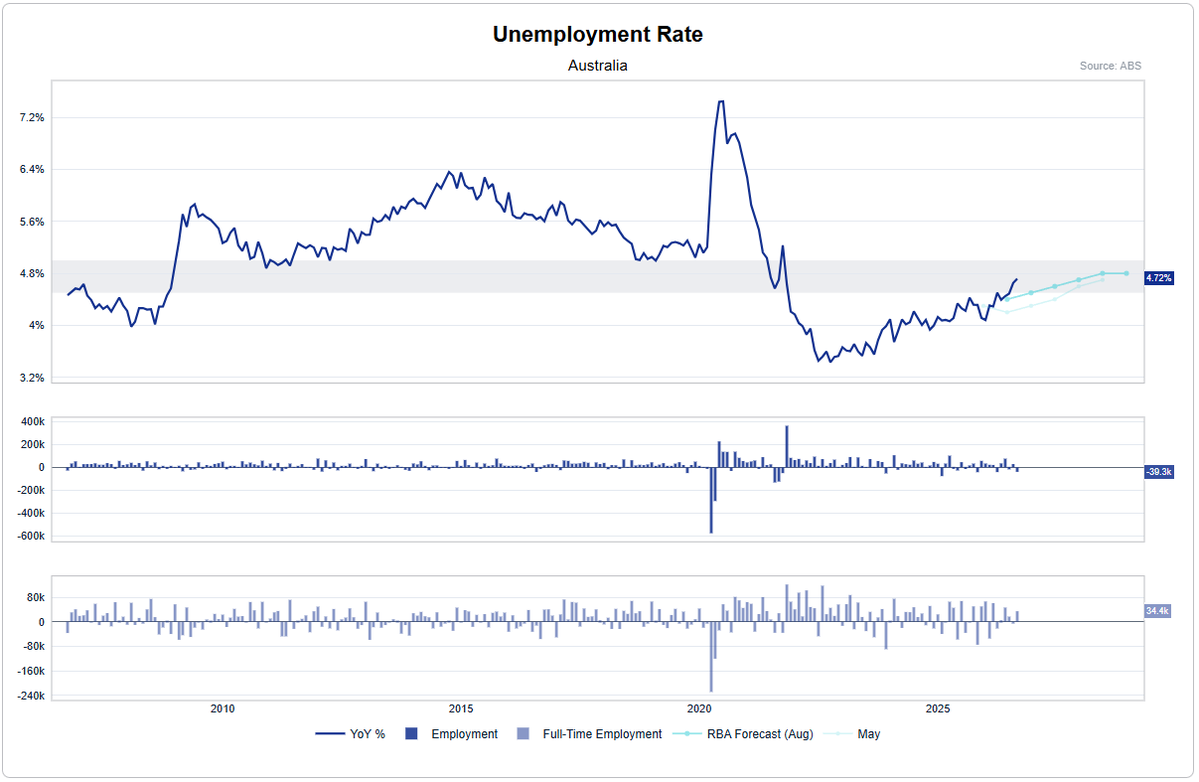
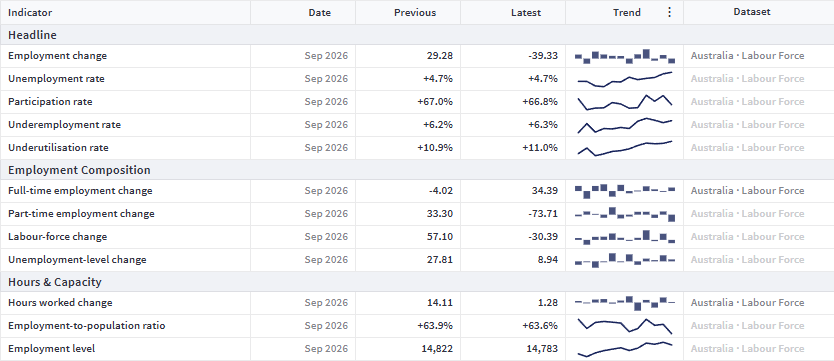
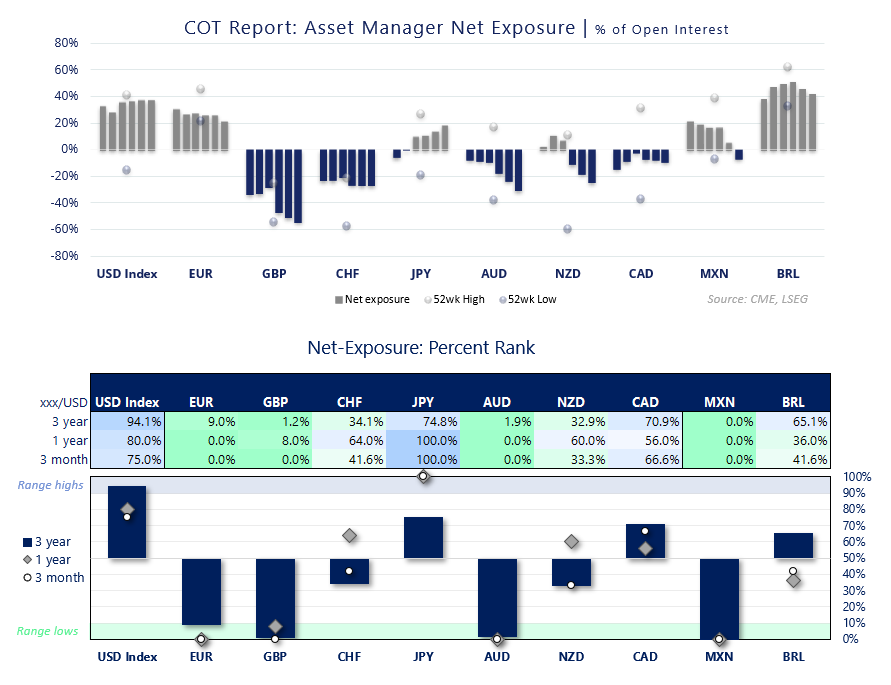
AU unemployment continued to accelerate beyond the RBAs forecast - rising to 4.7%.
A sharp decline of part-time jobs dragged the headling down to -39.3k, and hours worked was also soft.
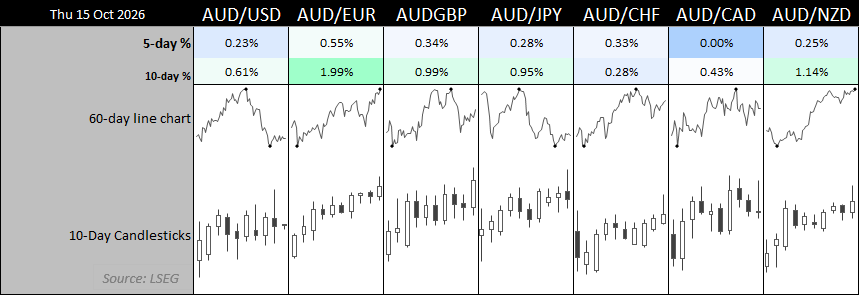
The Aussie is the weakest FX major as another nail goes into the coffin of another RBA hike.
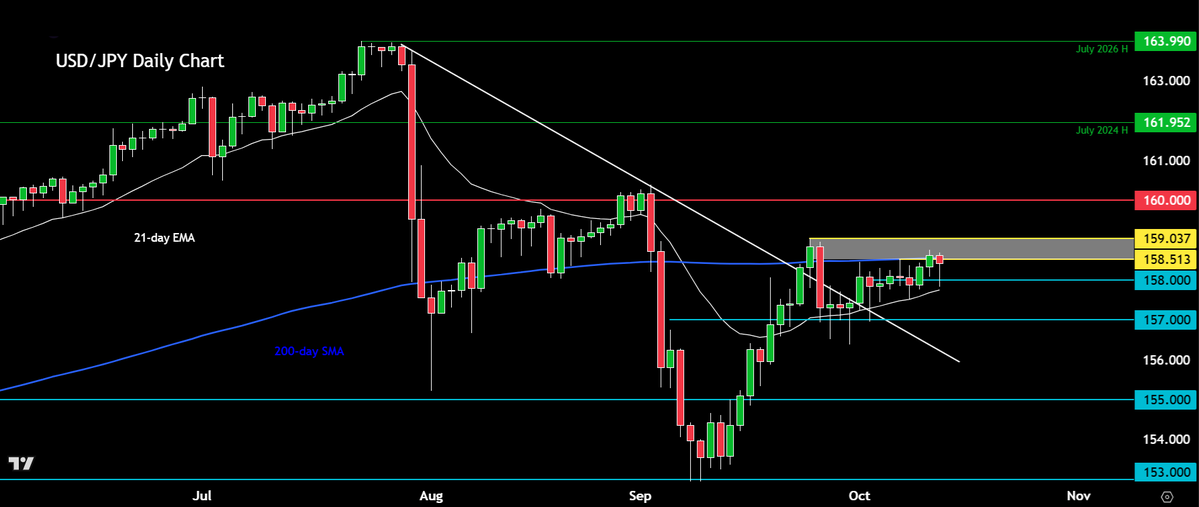
December remains the favoured time for the BoJ to hike, with OIS implying ~62% probability.
So far, we've seen a spike in Tokyo CPI, while import price inflation remains elevated at ~25% y/y. The BoJ's quarterly survey also shows 86.5% of households expect prices to rise over the next five years.
I'm not sure this is enough to get a decent bid for the yen though - unless services inflation and wage growth accelerate, another hike may simply be too well priced to provide much support.
Upcoming tests: national CPI (23 Oct), services PPI (27 Oct), Tokyo CPI (30 Oct) and wages (6 Nov).
China's factory gate prices increased to a four-year high of 5% y/y in September, thanks to higher commodity prices and energy costs. CPI remains subdued for now.
Note the Bloomberg Commodity Index remains elevated, suggesting PPI could have further to run, while the Baltic Dry Index points to rising sea freight costs.
It's probably more of a supporting feature for AUD/USD than a saviour at this point. The Aussie is still mulling a potential longer-term head-and-shoulders top.
AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
https://t.co/8fzzStaPLy
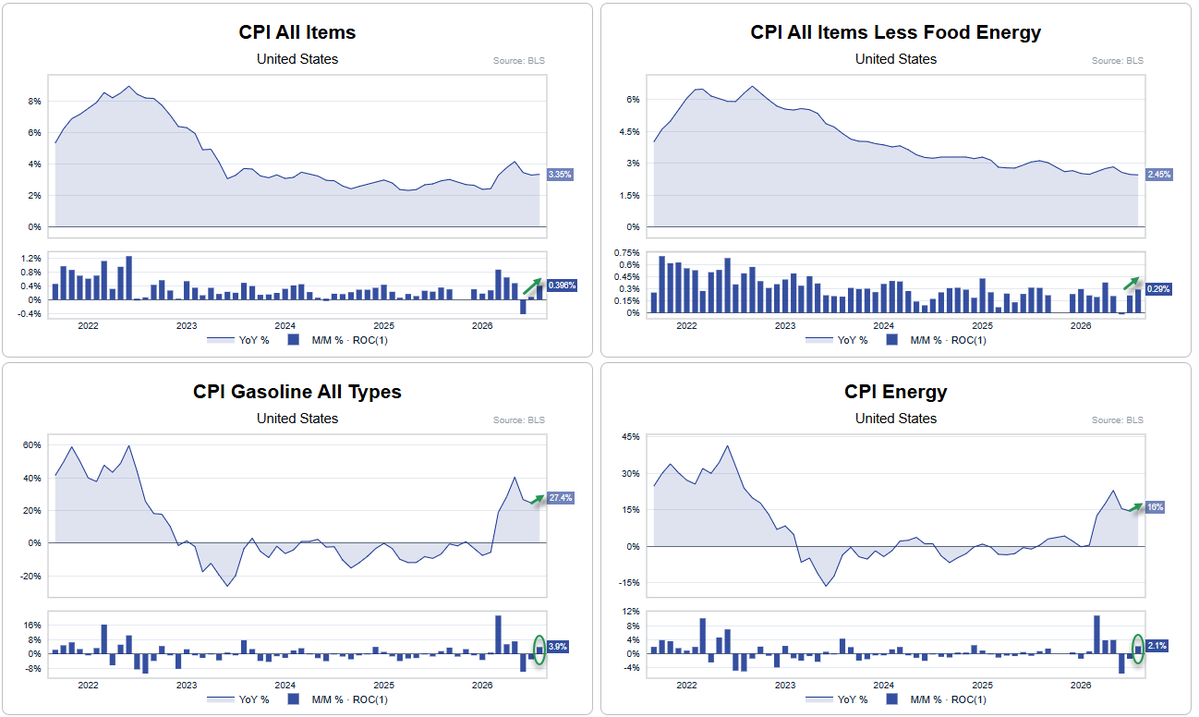
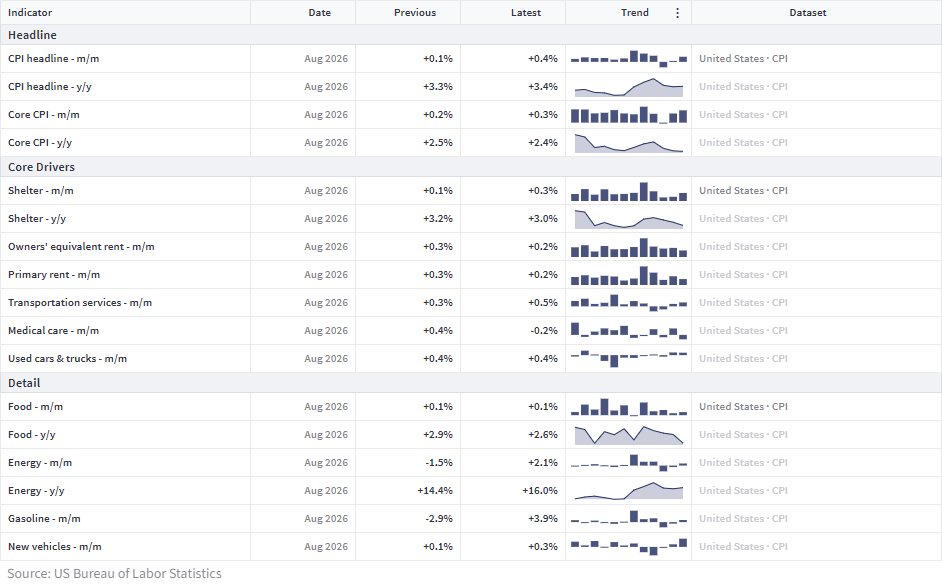
We know that energy is likely to be a driver behind hotter US inflation - the bigger question is whether it is showing up in other areas, and by how much.
In a few hours, we'll have the answer.
Recession-vibes on the rise in Brisbane.
We went to purchase a ceiling fan today, and saw a light shop and bed shop next to each other had permanently closed. The mattress shop to their left had a closing down sign.
Literally three in a row.
None of these were SMEs, all were homemaker chains.
Lots of sale signs among the other shops. That may be to compete with Amazon Prime week. But still... It doesn't paint a good picture for consumption.
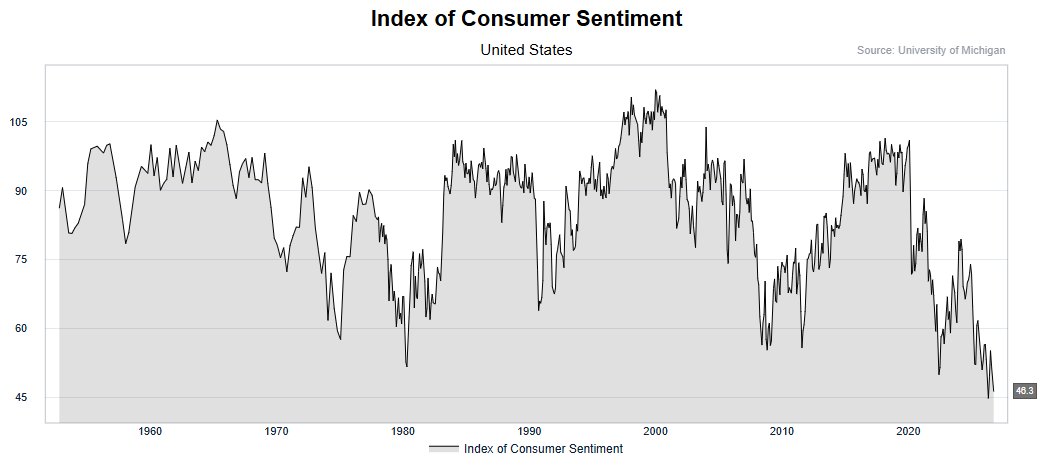
US consumer confidence is back near a record low according to the preliminary Michigan survey. A simialr trend is apparent on the CB report.
It's not too surprising to see inflation expectations tick higher, even if only marginally.
But it's difficult to see the Fed hike much from here. Retail sales this week will be interesting.