What is the Way Of Options? 💡
✅ Options strategies built around defined risk and disciplined positioning.
✅ Asymmetric bets targeting 2x+ reward-to-risk.
✅ Generate income by systematically selling puts & calls through the Wheel Strategy.
✅ Build long-term positions with LEAPS.
✅ Learn how to grow small accounts to $100K+.
➡️ I’ve spent 12+ years researching and trading global markets, with experience as an institutional trader & handled millions of dollars in book size.
No hype. Just disciplined process to manage risk and grow efficiently. All for FREE. No Paywall.
Join: https://t.co/eHVdyvonvB
30-day challenge, starting today.
I will publish one free option trade idea per day, built around high-probability and defined risk:
* Swing verticals at 30-45DTE
* Wheel strategy on quality underlyings
* LEAPS for the long-term view
You do not need a large account. Vertical spreads start from $50 of capital at risk.
Allocated $3000 for this small account challenge with full performance stats published weekly.
What you get:
* The trade structure and the reasoning behind it
* Breakevens, risk, entry & exit plan
* Honest updates on what worked and what did not
The aim is $5,000 by December.
Subscribe here to get each idea in your inbox 📥
https://t.co/eHVdyvonvB
Tell me which setup you want to see first.
I use @quantedOptions to monitor dealer positioning with real-time updates from CBOE's signed dealer feed, refreshed every 1 min. IMO, it is the best tool on the market for trading SPX options.
Get 20% off with the link below. 👇
https://t.co/PtIP845qvJ
SPX Options Update | 10/23
Regime: Negative gamma | Elevated volatility | Downside trend risk
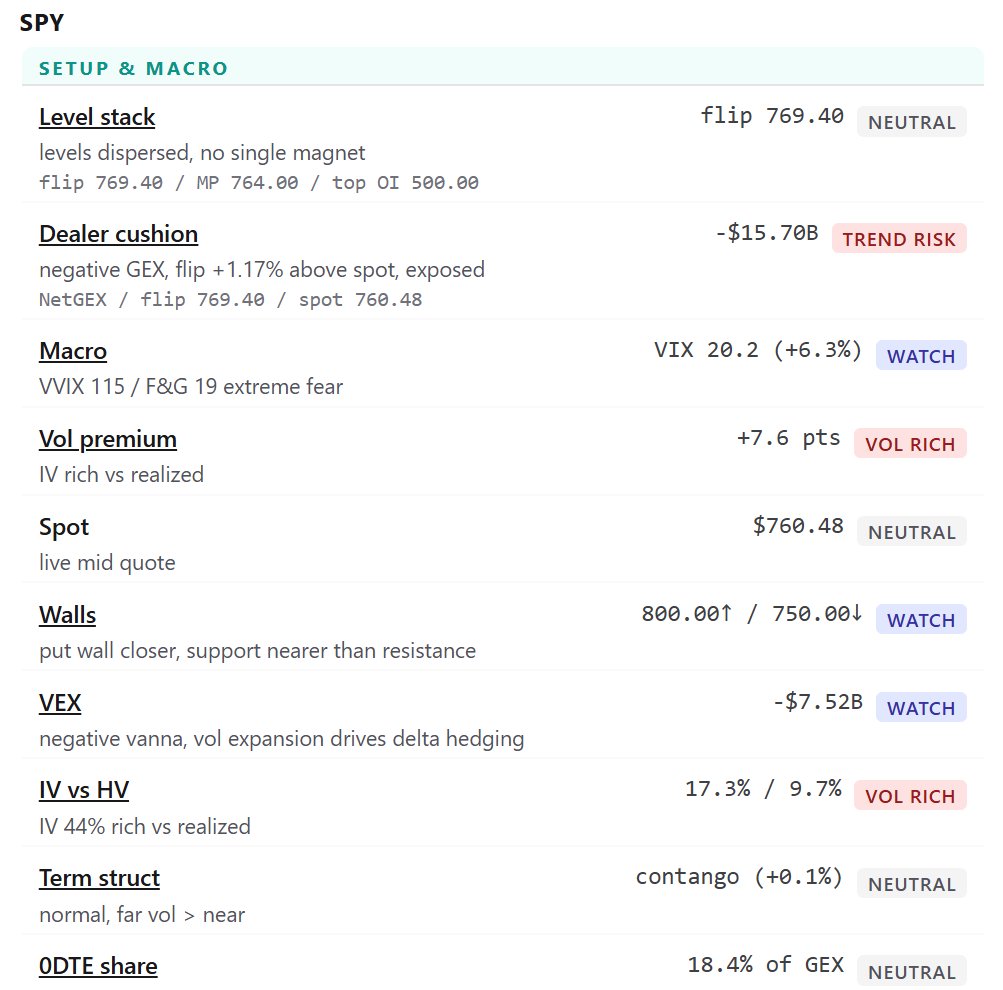
SPX is trading near 7,633, below the gamma flip at 7,694. Net GEX sits at roughly -$15.7B, so dealer hedging is likely to amplify moves rather than dampen them. VIX is at 20.2 (+6.3%), and implied volatility is running 7.6 points above realized, which favors wider intraday ranges.
Key levels:
- 7,650: positive 0DTE gamma and a charm reaction zone (7,640-7,650). It can act as a stabilizer, but it is not a guaranteed floor.
- 7,625 and 7,565: heavy negative strike-level exposure. If support fails here, the downside can accelerate.
- 7,600 and 7,540: additional liquidity concentrations below.
- 7,700-7,725: resistance and hedging zone. A sustained reclaim of 7,694 would weaken the bearish setup.
My framework while spot stays below the flip is conditional and downside-biased. A clean break of 7,625 with deteriorating delta opens a faster move lower. Stabilization at 7,650 with improving flows could produce a reflexive bounce.
One caution is that charm and GEX concentrations are model-dependent estimates, not price magnets. Actual dealer behavior depends on positioning, volatility changes, and time to expiry.
Given negative gamma and rich implied volatility, I would keep short-gamma exposure tight, wait for price confirmation, and avoid chasing extensions into high-interest strikes.
The key question today is whether 7,650 absorbs the selling or becomes a launch point for the next leg down. What are you watching?
Many options traders fixate on theta and vega.
A smaller group ventures into the second-order Greeks: gamma, charm and vanna.
Most simply map delta to probability of profit and call it a day.
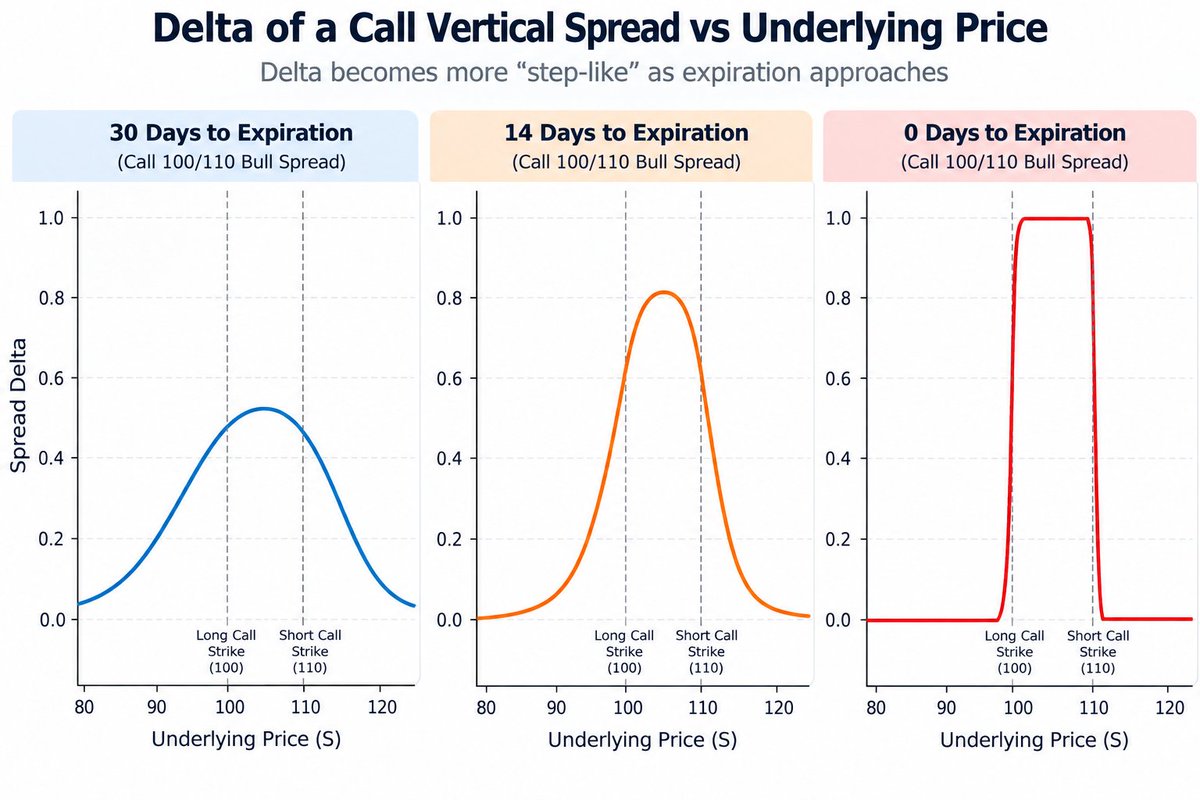
But delta also tells you how sensitive a position is to the underlying, and that sensitivity changes as the bell curve compresses into expiration.
Consider a vertical spread. Its delta profile changes materially as expiration approaches.
At 30 DTE, net delta is relatively smooth. At 14 DTE, it becomes more concentrated between the strikes. At expiration, it approaches a binary payoff profile.
The implications extend beyond delta:
- Gamma amplifies directional exposure
- Charm drives time-dependent delta shifts
- Vanna links volatility changes to delta
Near expiration, small moves in spot, time or implied volatility can materially alter the spread's risk and P&L. The closer to expiry, the more important strike location and gamma management become.
How do you manage your verticals as they approach expiration?
Friday's surge in VXX short-sale volume is a contrarian signal worth watching.
Historically, extreme activity has sometimes appeared near peaks in market fear, when the risk-reward for equities begins to improve.
Heading through Q4, post-midterm positioning shifts, Fed expectations and portfolio rebalancing could help volatility normalize. They also leave markets exposed to renewed geopolitical shocks.
The Middle East conflict becomes a real concern only if oil output is affected, and that has not happened so far. So, I expect markets to shrug off the Iran headlines, since Iran's leverage over the Strait of Hormuz is fading with time.
For options traders, the focus should be on confirmation:
- If equities stabilize and implied volatility retreats, defined-risk bullish spreads become more attractive
- Until then, keep selective downside protection in place
The objective is to capture volatility normalization without being exposed to another sharp expansion.
I still trade the SPX for most of my options positions. Over the next few days, I will research single stock names and initiate a few positions on a 30-45 DTE horizon. With VIX expiration today, expect increased volatility especially in the afternoon session. So, it’s better to define and keep risk to a comfortable level than chasing home-runs.
Market may behave erratically today and I won’t be surprised if it even breaches some key-levels established throughout this month.
Play defensive and protect your capital and don’t give away earlier gains.
Stay sharp! 🤝
SPX 0DTE Recap | 10/22
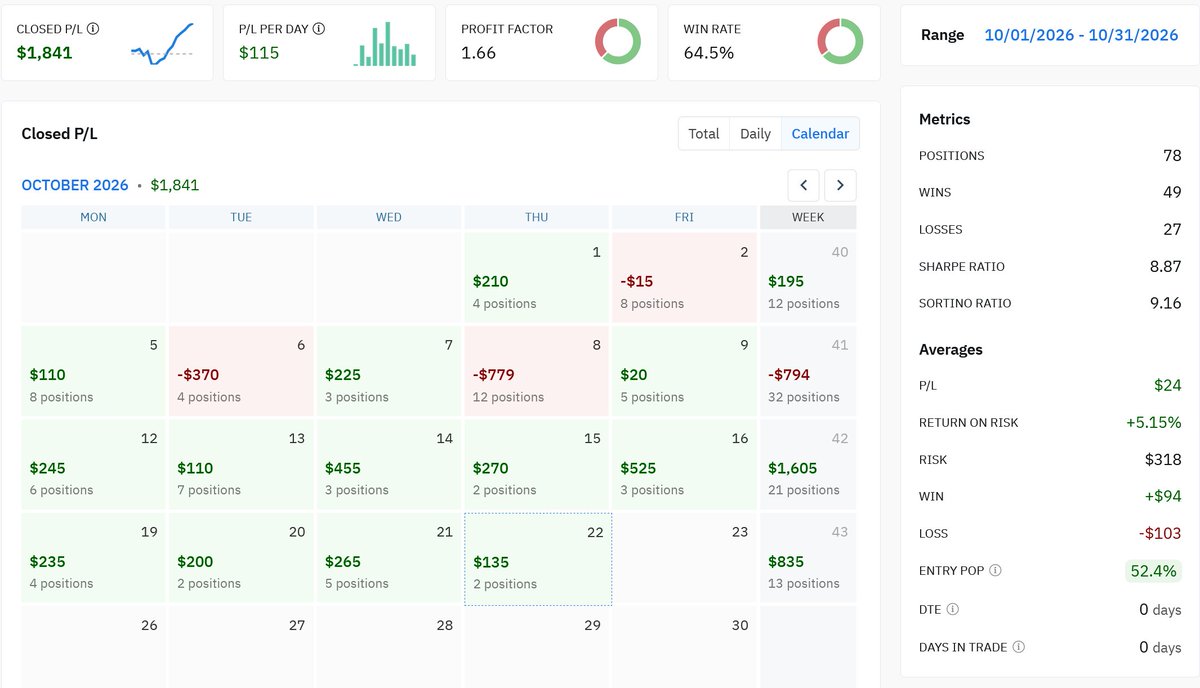
Session P/L $135 🟢
MTD P/L $1841 🟢
Another slow session, with a couple of trades late in the day. The market sold off overnight as the conflict in the Middle East reignited.
Oil remains elevated at north of $110/bbl. Volatility picked up after VIX expiration, and sellers stayed in control all day. The index opened in roughly $300bn of negative gamma, so dealers were shorting into the weakness and amplified the move. SPX hit a low of 7637 and closed at 7665, below the 7700 pivot.
I am playing defensive and booking small profits instead of swinging for home runs. There are 6 trading sessions left this month, and I will watch for better opportunities that could push the monthly P/L toward $3000.
The trade log for today is attached below.
30-day challenge, starting today.
I will publish one free option trade idea per day, built around high-probability and defined risk:
* Swing verticals at 30-45DTE
* Wheel strategy on quality underlyings
* LEAPS for the long-term view
You do not need a large account. Vertical spreads start from $50 of capital at risk.
Allocated $3000 for this small account challenge with full performance stats published weekly.
What you get:
* The trade structure and the reasoning behind it
* Breakevens, risk, entry & exit plan
* Honest updates on what worked and what did not
The aim is $5,000 by December.
Subscribe here to get each idea in your inbox 📥
https://t.co/eHVdyvonvB
Tell me which setup you want to see first.
@GammaGirlLab I don’t see any reason for the panic.
These are clean and also aligned with my earlier expectation of market bottom around Oct28.
That said, I’m thinking to tweak it a bit with put-broken-wing butterfly to increase profit potential.
@ZeeContrarian1 Trim your exposure. Hedge the downside selling call side. And wait for margin of safety for re-entry.
You should be fine by Q1’27.
A bear market trend out of the months long consolidation will start soon and is most likely imminent and sticky through Q1.
Just a view.
I use @quantedOptions to monitor dealer positioning with real-time updates from CBOE's signed dealer feed, refreshed every 1 min. IMO, it is the best tool on the market for trading SPX options.
Get 20% off with the link below. 👇
https://t.co/PtIP845qvJ
SPX 0DTE Recap | 10/22
Session P/L $135 🟢
MTD P/L $1841 🟢
Another slow session, with a couple of trades late in the day. The market sold off overnight as the conflict in the Middle East reignited.
Oil remains elevated at north of $110/bbl. Volatility picked up after VIX expiration, and sellers stayed in control all day. The index opened in roughly $300bn of negative gamma, so dealers were shorting into the weakness and amplified the move. SPX hit a low of 7637 and closed at 7665, below the 7700 pivot.
I am playing defensive and booking small profits instead of swinging for home runs. There are 6 trading sessions left this month, and I will watch for better opportunities that could push the monthly P/L toward $3000.
The trade log for today is attached below.
SPX 0DTE Recap | 10/21
Session P/L $265 🟢
MTD P/L $1706 🟢
Another good session. Today was a VIX expiration day, so I spent the morning observing before placing any trade.
Once SPX stabilized after forming the low and high of the day with strong bullish price action, I opened a $15 wide 7760 iron fly.
The index then dropped sharply to the low 7640s in the final 90 minutes. I expected support to hold, so I sold put spreads and collected a decent credit. As the index kept falling, I sold an in-the-money put spread, which improved the overall risk:reward of the book.
Once SPX recovered above 7750, I closed everything for a $265 profit on the day.
Had I left the put spreads to expire, the profit would have been north of $1300. That looks disappointing on paper, but I am comfortable taking clean wins day after day. VIX expiry flow and dealer hedging of the options exposure also added risk into the close, so I preferred not to carry it.
Overall, a decent day as the profits pass $1700 on this $5K small account dedicated to SPX.
The trade log and month-to-date stats are attached below.
Two sessions are left this week, and I am looking to close it higher. Let's see how it goes.
If you would like to copy our trades in your broker account, sign up below.
20% OFF launch offer for the first 50 spots only. Closing soon.
https://t.co/k8ceSrX8E5
SPX 0DTE Recap | 10/21
Session P/L $265 🟢
MTD P/L $1706 🟢
Another good session. Today was a VIX expiration day, so I spent the morning observing before placing any trade.
Once SPX stabilized after forming the low and high of the day with strong bullish price action, I opened a $15 wide 7760 iron fly.
The index then dropped sharply to the low 7640s in the final 90 minutes. I expected support to hold, so I sold put spreads and collected a decent credit. As the index kept falling, I sold an in-the-money put spread, which improved the overall risk:reward of the book.
Once SPX recovered above 7750, I closed everything for a $265 profit on the day.
Had I left the put spreads to expire, the profit would have been north of $1300. That looks disappointing on paper, but I am comfortable taking clean wins day after day. VIX expiry flow and dealer hedging of the options exposure also added risk into the close, so I preferred not to carry it.
Overall, a decent day as the profits pass $1700 on this $5K small account dedicated to SPX.
The trade log and month-to-date stats are attached below.
Two sessions are left this week, and I am looking to close it higher. Let's see how it goes.
I use @quantedOptions to monitor dealer positioning with real-time updates from CBOE's signed dealer feed, refreshed every 1 min. IMO, it is the best tool on the market for trading SPX options.
Get 20% off with the link below. 👇
https://t.co/PtIP845qvJ
SPX 0DTE Recap | 10/21
Session P/L $265 🟢
MTD P/L $1706 🟢
Another good session. Today was a VIX expiration day, so I spent the morning observing before placing any trade.
Once SPX stabilized after forming the low and high of the day with strong bullish price action, I opened a $15 wide 7760 iron fly.
The index then dropped sharply to the low 7640s in the final 90 minutes. I expected support to hold, so I sold put spreads and collected a decent credit. As the index kept falling, I sold an in-the-money put spread, which improved the overall risk:reward of the book.
Once SPX recovered above 7750, I closed everything for a $265 profit on the day.
Had I left the put spreads to expire, the profit would have been north of $1300. That looks disappointing on paper, but I am comfortable taking clean wins day after day. VIX expiry flow and dealer hedging of the options exposure also added risk into the close, so I preferred not to carry it.
Overall, a decent day as the profits pass $1700 on this $5K small account dedicated to SPX.
The trade log and month-to-date stats are attached below.
Two sessions are left this week, and I am looking to close it higher. Let's see how it goes.
SPX 0DTE Recap | 10/20
Session P/L $200 🟢
Another decent session. The morning was volatile after the index tested lows near 7768 and bounced to ~7748, close to the 21DMA resistance, on early rumors of a US-Iran deal.
The move faded into the afternoon once Iran denied that any deal was being made and said the talks were only progressing.
I sold a $10 wide put spread first, but closed it quickly and opened a $10 wide iron condor at the closest bounds instead.
The condor gave me a $330 profit from theta decay by the afternoon, which netted $200 for the day.
I am harvesting premium in elevated volatility, so I do not intend to carry these positions to expiry.
Tomorrow is VIX expiration, so I expect some volatility in the index.
I plan to keep building consistency and lift the equity curve in this small account.
The daily log of trades is attached below.
Institutional grade SPX strategies. Executed in your account.
⚡ Ultra-fast order fills
💰 Money stays in your account
🎛️ Full control. Manually override anytime
Copy trade in 3 seconds 👇
https://t.co/k8ceSrX8E5
Many options traders fixate on theta and vega.
A smaller group ventures into the second-order Greeks: gamma, charm and vanna.
Most simply map delta to probability of profit and call it a day.
But delta also tells you how sensitive a position is to the underlying, and that sensitivity changes as the bell curve compresses into expiration.
Consider a vertical spread. Its delta profile changes materially as expiration approaches.
At 30 DTE, net delta is relatively smooth. At 14 DTE, it becomes more concentrated between the strikes. At expiration, it approaches a binary payoff profile.
The implications extend beyond delta:
- Gamma amplifies directional exposure
- Charm drives time-dependent delta shifts
- Vanna links volatility changes to delta
Near expiration, small moves in spot, time or implied volatility can materially alter the spread's risk and P&L. The closer to expiry, the more important strike location and gamma management become.
How do you manage your verticals as they approach expiration?