Constraints drive markets.
AI growth doesn’t stop at GPUs.
Power, transformers, grid connections, cooling and critical metals can become the bottlenecks 2–3 levels upstream.
I look for the bottleneck the market hasn’t priced yet.
Process over narrative.
#SystemMargin
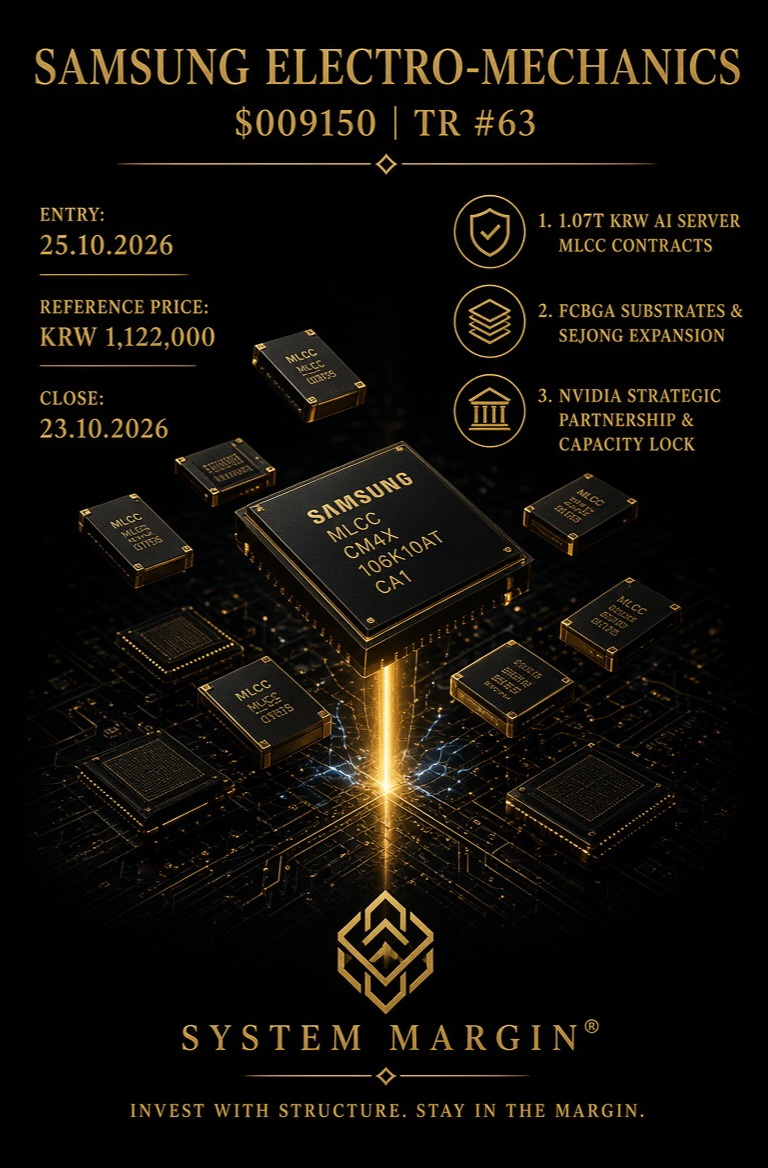
Samsung is investing 4.27T KRW in Sejong, backed by an Nvidia alliance & volume commitments. But volume doesn't equal automatic profitability. Ramping up capacity & yield is a different beast. I'm tracking the supplier economics to see if this truly shifts the power dynamic.
Samsung Electro-Mechanics ($009150). Everyone hypes Nvidia & HBM, but AI chips are expensive silicon paperweights without the electronic backbone. I’m shifting focus to the gritty supply chain where infrastructure is actually built. FCBGA substrates are the main story.
Germany has 80GW in data center connection requests, 13GW approved, and just 1–2GW actually connected. Quite a gap Not every project will happen, so I’m not taking those 80GW at face value. The question is how much real demand shows up, and what E.ON earns from building the grid
E.ON plans to spend €48B by 2030 with €40B going into grids. Sounds like a great business, right? But spending billions and actually making good money on them are two different things. I want to see what’s left after regulation, financing costs and all the headaches of building
My motto. This is where it all began.
“I look for what the market doesn’t yet know it will need.”
That idea is behind every analysis I do #SystemMargin
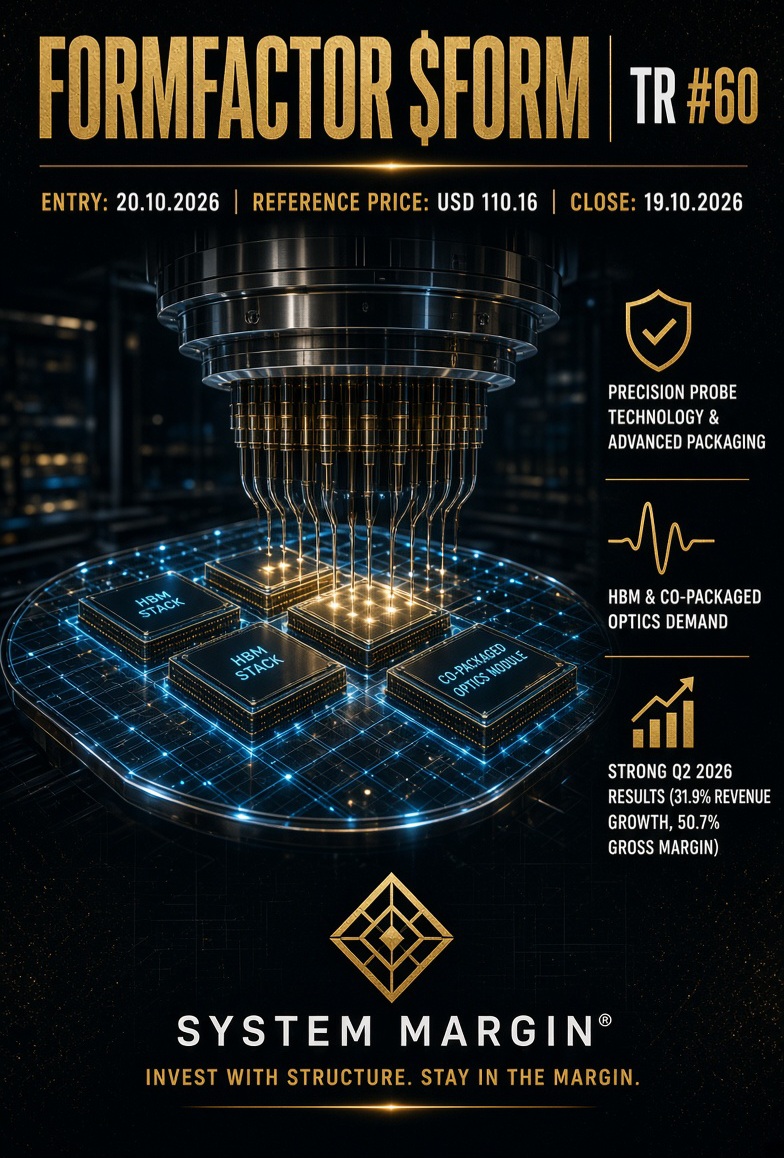
In Q2 2026, their revenue jumped 31.9% YoY, and GAAP gross margin topped 50% due to HBM demand. Can they defend these great margins long term in such a brutally competitive market? No final verdict yet, but the company enters my Track Record for strict verification.
When we think about chips, we usually picture AI giants. I am looking a step lower at #FormFactor $FORM. They don't design processors; they provide the testing gear. With advanced packaging and HBM memory, production simply falls apart without their tools.
What interests me is the installed base, spare parts, servicing and power systems for data centers.
But how much of that value can CAT actually defend? Cyclicality, tariffs and competition still matter. That’s what I want to test in System Margin.
#SystemMargin
Caterpillar $CAT | TR #59
I’m looking beyond the yellow machines. Caterpillar made $20.5B in revenue in Q2 2026, up 24% YoY, with a 20.9% operating margin.
#Caterpilar
Strong numbers. But good results alone don’t prove a durable moat. 🧵
What caught my eye? A 51.8% gross margin and €434m in FCF in 2025.
But I’m not ignoring the risks: cyclical capex, customer concentration and heavy exposure to Asia.
Good technology is one thing. Durable value capture is another.
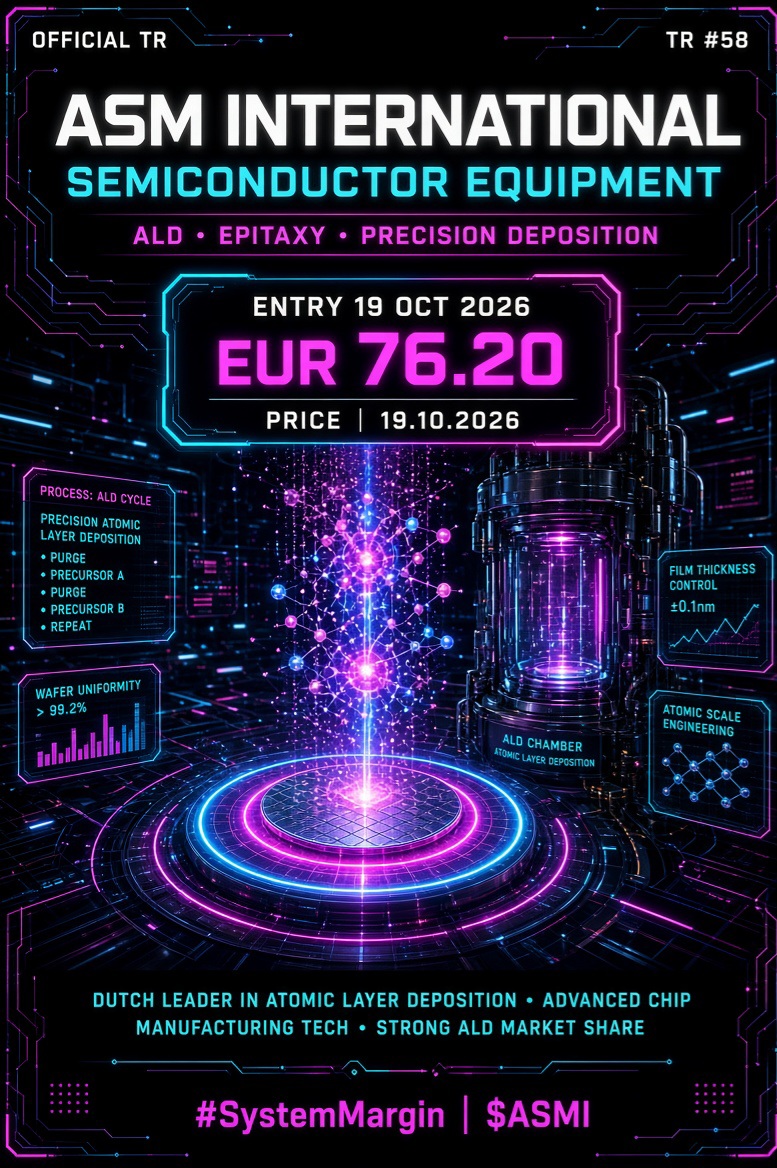
That’s what I’ll be tracking. #ASMI
I’ve added ASM International ($ASMI) to my Track Record.
It makes equipment used in chip manufacturing, with ALD technology at the core. Its edge isn’t just exposure to AI. It’s the ability to deposit ultra-thin material layers with extreme precision.
That’s worth watching. 🧵
But I'm not buying the growth story blindly. The top supplier accounts for 69% of purchases, while the top 5 customers bring in 45% of revenue.
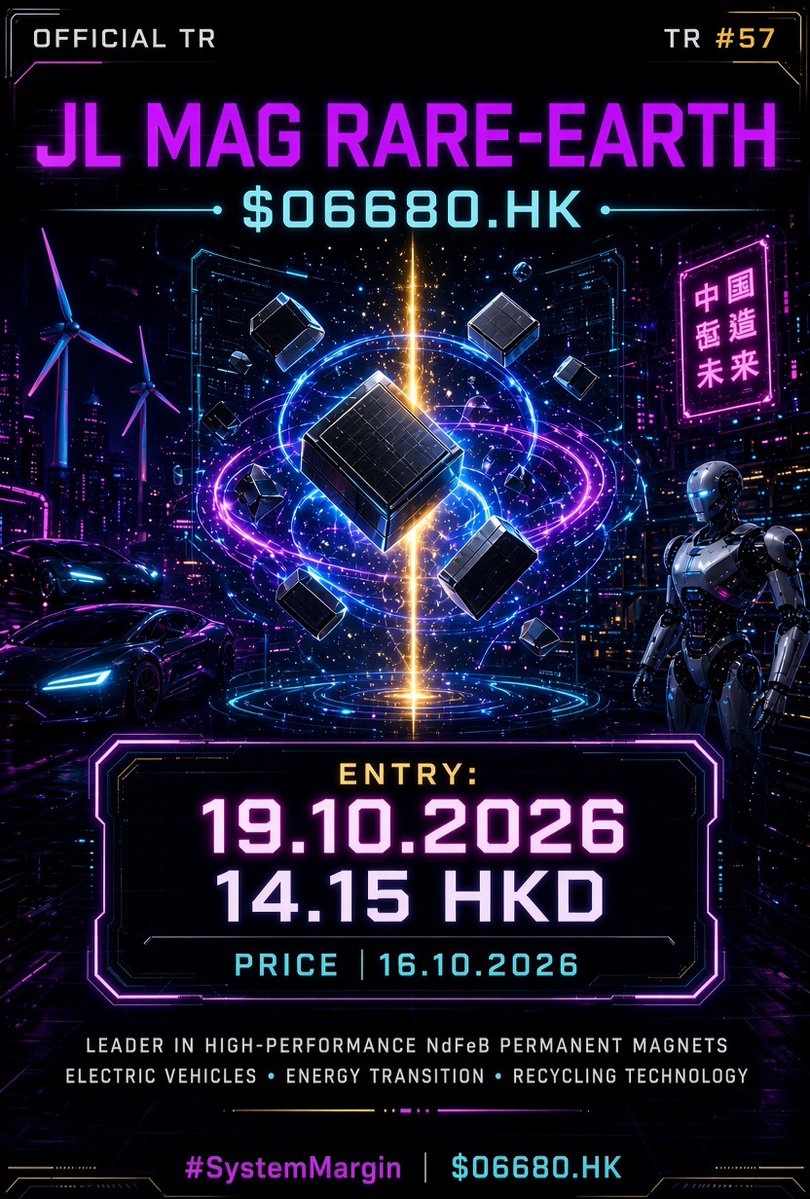
Big production scale is great. Now I want to see if JL MAG can turn it into durable economic rent. That's what matters to me.
JL MAG $06680.HK is my new TR #57 entry. In 2025, revenue grew 14% to RMB 7.72B, while profit jumped 142%.
They don't mine rare earths. They turn them into high performance magnets used in EVs, air conditioners and wind power. That's the part I want to watch.