What I post every day:
Pre-Market (before 9:30 ET)
• Key levels on the names I’m watching
• Overnight news + rate/ macro context that actually matters
• 2–4 setups I’m tracking into the open
Intraday
• Real-time notes on what’s confirming or failing
• Charts only when the structure is clean
• No constant posting — only when the tape is speaking
Post-Close
• What worked, what didn’t, and why
• Updated levels for the next session
• Short recap of quality names and rate action
Focus: quality businesses, the rate cycle, and what the tape actually confirms.
Charts + context.
Not financial advice.
Tech stocks got smoked today after Meta and Tesla earnings. Both beat, but Meta’s free cash flow went negative and Tesla cut its 2026 capex — markets didn’t like the “spend first, prove returns later” vibe.
Oil ripping higher on Middle East tensions just poured gas on the fire. Result: heavy AI/semiconductor selling and a clear rotation into defensives (staples, healthcare, utilities).
High valuations + shaky spending narrative = quick unwind. Not the end of AI, but the easy money phase looks done for now.
Called the defensive rotation early last week. Here’s how those 5 names have done since the post:
$LLY +6.7%
$JNJ +5.6%
$ABBV +6.6%
$MRK +5.0%
$GILD +4.7%
Nothing crazy, but all green while tech was getting sold. Classic “money hides in healthcare first” trade.
Still like the setup, or is the easy money already made?
Tech still getting crushed… but the money’s quietly rotating.
One hour in and the tape is clear: semis/AI keep getting sold while healthcare and staples are the only green on the screen. Classic defensive move.
5 healthcare names that actually look decent today:
$LL – still the highest-quality compounder in the group
$JNJ – boring, steady, and doing exactly what it’s supposed to
$ABBV – cleaner story + strong cash flow than most people realize
$MRK – oncology leader that doesn’t get the hype
$GILD – quietly outperforming while everyone watches chips
When growth gets shaky, this is usually where money hides first.
You in any of these? Or which one do you like most right now?
Drop it below — I’ll dig into whatever gets the most replies.
Follow for real-time sector rotation notes without the fluff.
BREAKING: Global technology equity funds recorded -$4.8 billion in outflows in the week ending October 14th, their largest weekly outflow in at least 5 weeks. US tech funds drove the withdrawals, with -$5.2 billion in outflows. Meanwhile, all global equity funds attracted +$20.0 billion in inflows over the same period, marking their 4th consecutive weekly inflow. This follows +$1.6 billion in inflows the previous week and +$35.4 billion 2 weeks earlier. US equity funds alone recorded +$13.0 billion in inflows. Investors sold tech and bought other parts of the market.
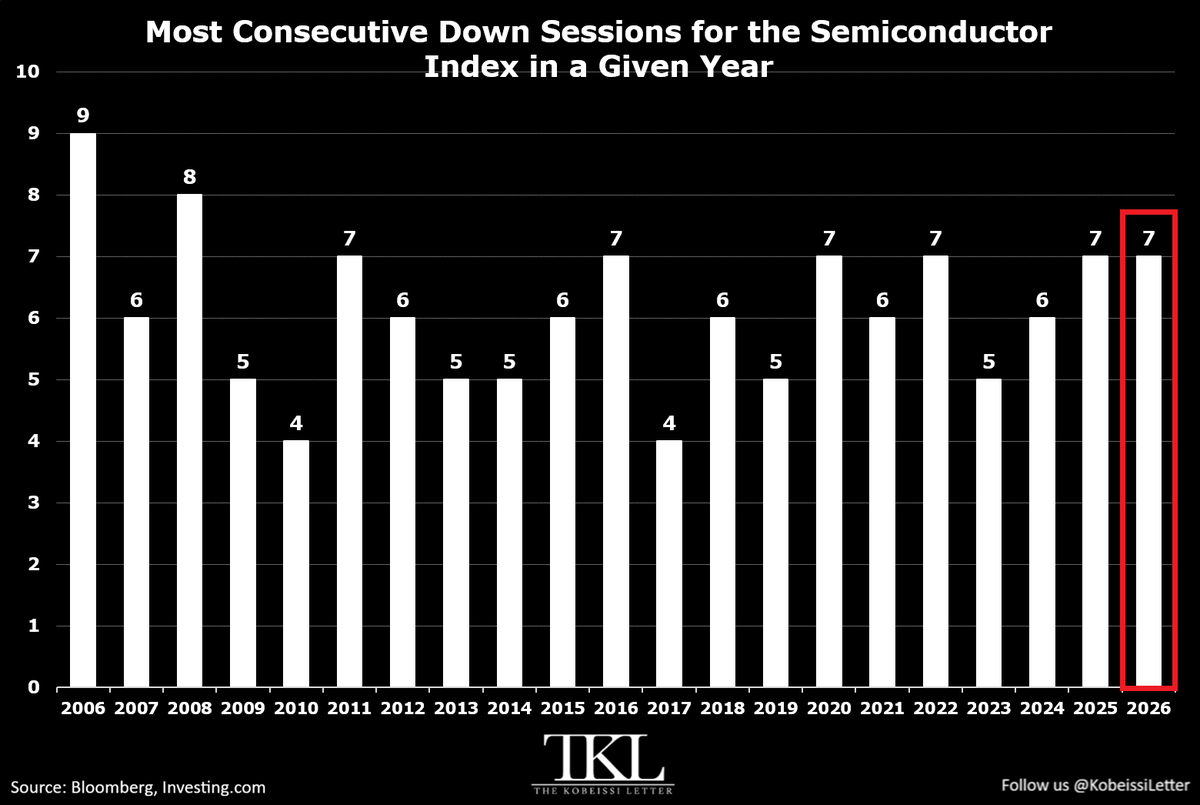
Semiconductors just matched their longest losing streak since the 2008 crisis. 7 straight down days, $2T wiped out.
AI names have been the market’s favorite for years… until they weren’t. When the biggest winners start swinging this hard, something’s usually shifting.
You still riding the semiconductor wave or rotating out?
Semiconductor stocks are experiencing a historic losing streak:
The Semiconductor Index, $SOX, has declined for 7 consecutive trading sessions, matching its longest streak since the 2008 Financial Crisis.
Over this span, the index has dropped -12.4% erasing -$2 trillion in market value.
This also marks its 5th correction of at least -10.0% this year.
Currently, more than 50% of SOX’s constituents are down at least -10% from their respective highs.
Over the last 20 years, there have only been 2 longer such streaks, in 2006 and 2008.
Semiconductor stocks are seeing massive swings.
Gold just flexed on the entire market. While everyone else was freaking out about AI debt and tech getting smoked, the gold & precious metals crew went nuclear. Biggest theme mover by a mile. When the yellow metal’s ripping over $4k, the good miners and streamers don’t just tag along—they usually go harder.
Here are 5 solid names that actually have real scale and room to run:
1. $NEM (Newmont) – Still the big dog. Massive production, strong free cash flow, and they’re finally cleaning up the ops. When gold stays elevated, these guys just print.
2. $AEM (Agnico Eagle) – One of the cleaner operators out there. Higher-grade assets, tight costs, and they’ve been delivering on the cash flow. Feels like the quality compounder of the group.
3. $B (Barrick) – Been a little overlooked, but valuation looks reasonable and operations are improving. Not pure gold anymore either, which adds some extra leverage.
4. $WPM (Wheaton Precious Metals) – Streaming model so they skip the mine drama. Gold and silver exposure with way less operational risk. Strong cash flow and they keep stacking more streams.
5. $FNV (Franco-Nevada) – The royalty king. Super diversified, no mine risk, and they sit on some of the best assets in the world. If you want gold exposure that lets you sleep at night, this is it.
Bottom line: gold still has a bid from geopolitics, inflation noise, and central bank buying. These five give you a mix of pure producers and lower-risk streamers/royalties so you’re not betting everything on one mine. Not advice—do your own work—but if this theme keeps running, these are the ones that usually show up. What are you guys watching?
Tech still getting crushed… but the money’s quietly rotating.
One hour in and the tape is clear: semis/AI keep getting sold while healthcare and staples are the only green on the screen. Classic defensive move.
5 healthcare names that actually look decent today:
$LL – still the highest-quality compounder in the group
$JNJ – boring, steady, and doing exactly what it’s supposed to
$ABBV – cleaner story + strong cash flow than most people realize
$MRK – oncology leader that doesn’t get the hype
$GILD – quietly outperforming while everyone watches chips
When growth gets shaky, this is usually where money hides first.
You in any of these? Or which one do you like most right now?
Drop it below — I’ll dig into whatever gets the most replies.
Follow for real-time sector rotation notes without the fluff.
Damn, Wall Street just got smoked today!
Hot CPI print hit like a truck and the market folded hard.
Here’s the damage from today’s close (Oct 14):
- Dow: basically flat-ish, down like 0.1–0.4%
- S&P 500: dropped around 1.1–1.3%
- Nasdaq: got wrecked, down almost 2%
September inflation came in hotter than expected — 3.7% year-over-year instead of the 3.6% people were hoping for. Core was sticky too. Instantly, rate-hike odds for later this month jumped and traders freaked out.
### What actually happened:
Tech and chips got absolutely crushed again. AI-related names were bleeding, CoreWeave got torched (down over 15% at one point), and the whole semiconductor space just kept sliding. Bank of America also took a big hit after that $1.2B fine news.
Healthcare and a few defensive names held up better, but overall it was a risk-off day. Yields spiked, the dollar popped, and that long streak of calm in the S&P finally broke.
Feels like the market just got a reality check after running hot for a while. Inflation ain’t gone yet and the Fed might still have more work to do.
You buying this dip or waiting for more pain? Drop your thoughts below.
Intraday Note |
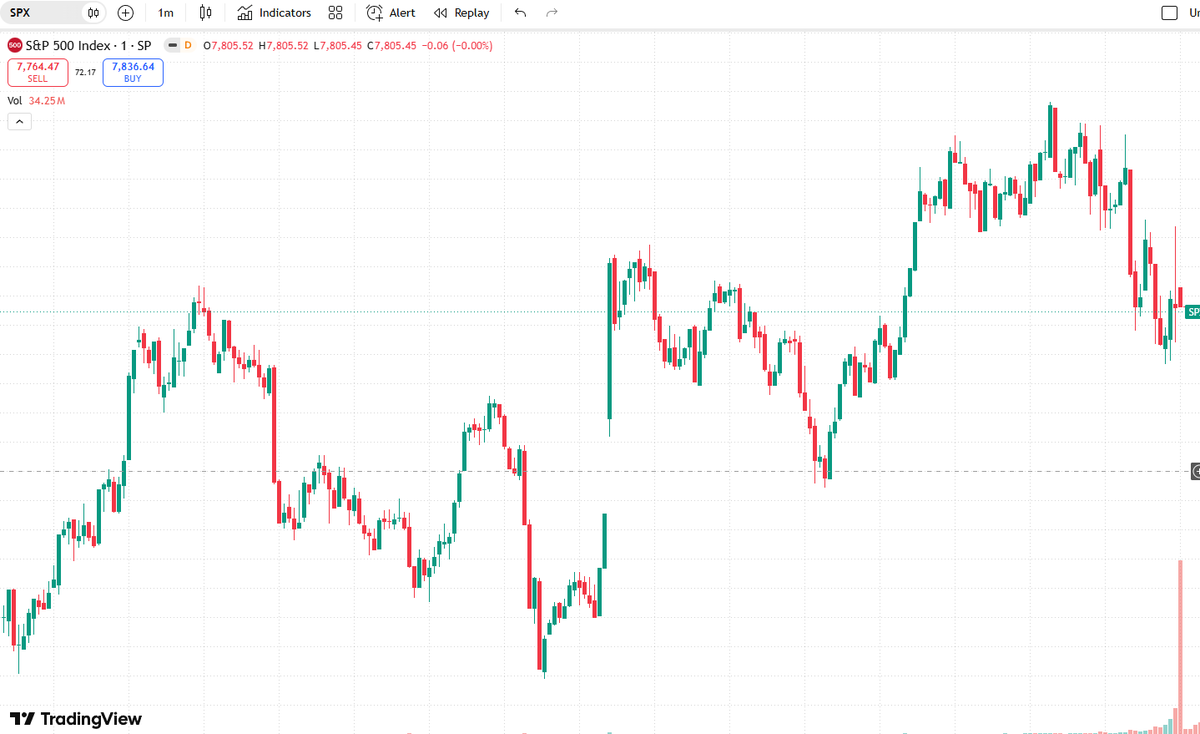
CPI just confirmed what the tape already knew.
Growth is still getting sold.
Structure so far:
• Yields confirming higher — 10Y pushing up after the hotter-than-expected print
• Growth and Nasdaq under pressure — rate-sensitive names continuing to struggle, with no real absorption yet
• Financials failing to hold — $BAC weakness after earnings and the fine is adding to the soft tone
• Energy still relatively better, but not enough to offset the broader pressure
Key level: $SPX 7800
Tape reading:** Selling remains more aggressive than the buying. Volume is confirming the CPI reaction rather than absorbing it.
Next decision point: Whether $SPX can hold the 7800 area into the afternoon, or if the weakness continues to drag on the tape.
Only updating when the tape is actually speaking.
Charts + Logic.
Not financial advice.
Pre-Market Focus |
30 minutes to CPI.
Nothing else matters right now.
Key names on watch:
• $BAC / $MS — Post-earnings reaction | Watching if $BAC’s fine-related weakness gets absorbed or spreads
• $SPX — 7800 area | Rate sensitivity still elevated into the print
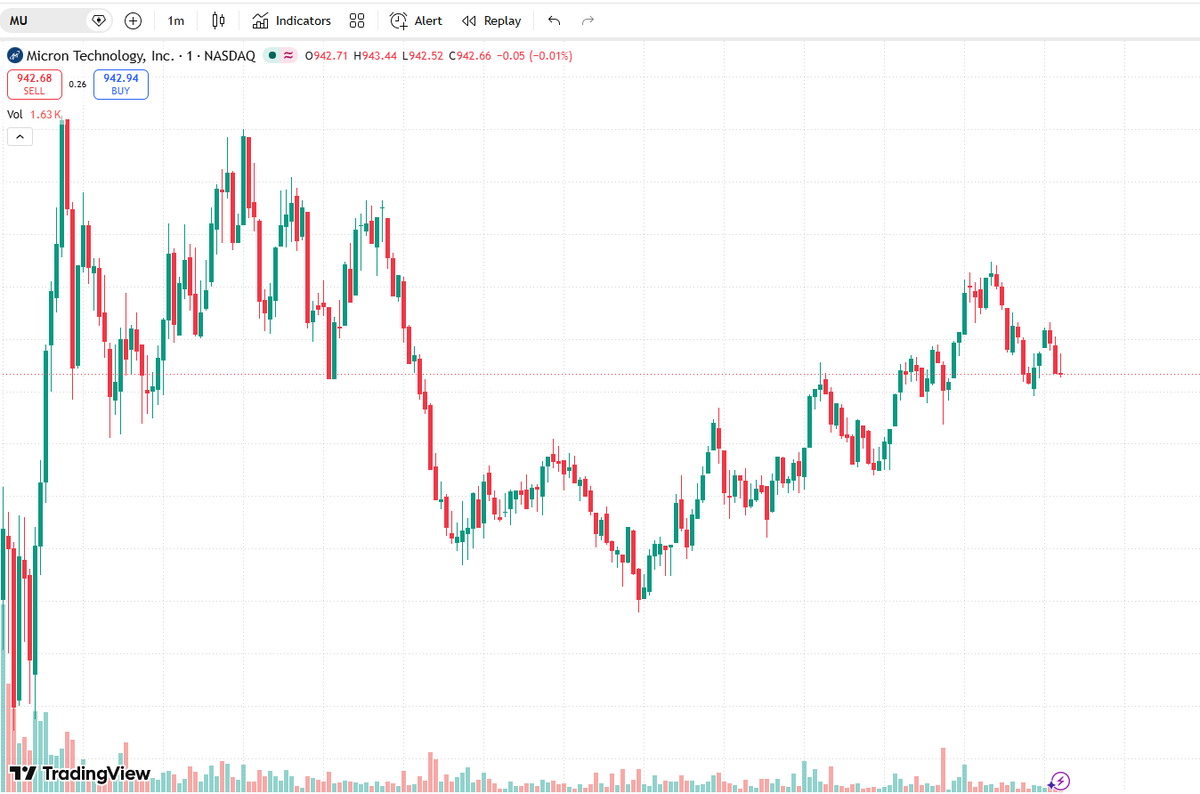
• $MU / Semiconductors — Watching for stabilization after recent selling | Needs to hold key lows
Macro/Rates context that matters:
Headline CPI is expected at +3.6% YoY. 10Y yield holding near 5.19–5.20% overnight. A hot print keeps pressure on growth names; a soft print can support the recent rotation attempt.
Setups into the open:
1. Financials — Watch $BAC reaction to the regulatory fine. Failure to hold premarket lows opens further downside into the cash session.
2. Indexes into CPI — $SPX needs to hold recent support. A hot inflation number invalidates early strength quickly.
3. Semiconductors — $MU and the group need to show absorption near recent lows. Continued selling keeps pressure on the Nasdaq.
Tape will decide. Charts + Logic.
Not financial advice.
Intraday Note |
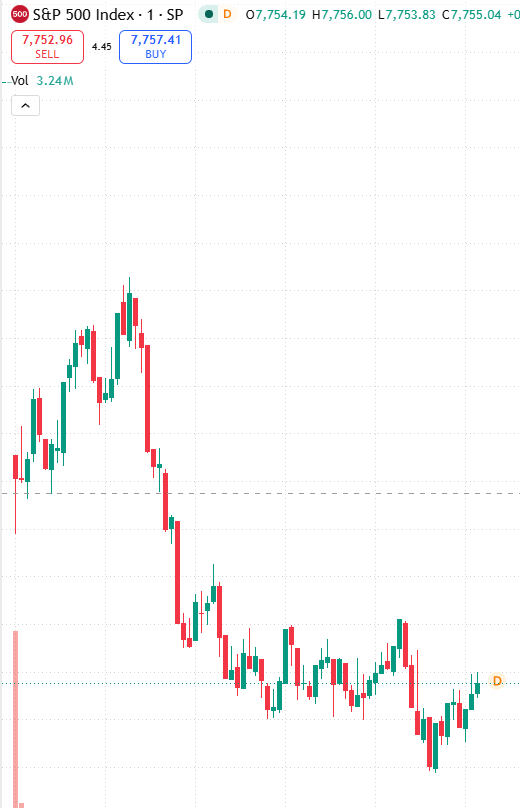
Chips are still getting sold.
Banks aren’t saving the tape.
Structure so far:
• Chip / memory names continuing lower — $MU and the broader semiconductor complex remain under pressure, no real absorption yet
• Financials mixed after earnings — initial strength faded and failed to provide a strong bid for the broader market
• Energy holding relatively better than tech, but not leading aggressively
Key level: $SPX 7800
Tape reading: Selling in semiconductors still looks more aggressive than the buying in value and energy. Volume is confirming the rotation, not fighting it.
Next decision point: Whether semiconductors can stabilize into the afternoon, or if the weakness continues to drag on the Nasdaq and broader indexes.
Still watching whether $MU can hold yesterday’s lows into the close.
Only updating when the tape is actually speaking.
Charts + Logic.
Not financial advice.
@KalebOstler Appreciate it. Rotation into value/energy held up well while chips got dumped on volume — classic risk-off. 7800 on SPX feels like the real test tomorrow.
Indexes were flat.
The tape wasn’t.
Value up. Chips down. Breadth weak.
Here’s what actually happened:
What worked:
• Value / Energy / Communication Services — Rotation held into the close as oil stayed firm and capital rotated out of high-multiple growth.
• $META — Relative strength in communication services provided a bid while semiconductors faded.
What didn’t:
• Semiconductors — $MU and the broader chip complex saw continued selling. Volume confirmed rejection, not absorption.
• Nasdaq breadth — New lows outnumbered new highs as growth names failed to reclaim key levels.
Rates context today:
Bond market closed (Columbus Day). 10Y holding ~5.24% — still high enough to pressure longer-duration growth while supporting the rotation into value.
Updated levels for tomorrow:
• $SPX — 7800 remains the near-term pivot. Hold = constructive; lose it and the prior range comes back into play.
• $QQQ / Nasdaq — Needs to reclaim today’s failed structure, or semiconductor weakness can spill further into the open.
• Quality names still on radar: $XOM, $CVX, $COP (energy bid held cleanly) + selective financials ahead of bank earnings.
Light volume, real rotation.
Now the question is whether it sticks through bank earnings and CPI.
I’ll be watching if quality names actually follow through — what’s your read?
Charts + Logic. Process over outcome.
Not financial advice.
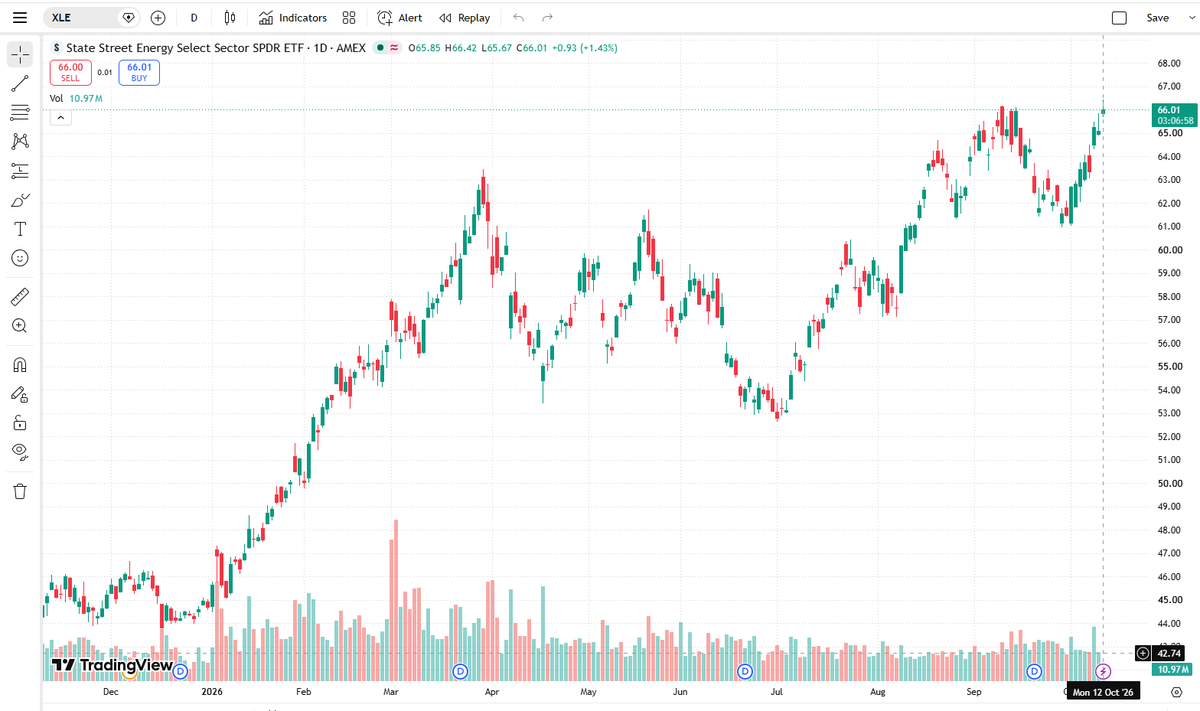
Energy’s the only group that actually showed up today 🔥
The rest of the tape is red. Oil isn’t. And the leaders aren’t the usual mega-cap drillers — they’re the refiners. $XLE is up about 1.3% as of early afternoon ET, and inside it the real movers are $MPC, $VLO, and $PSX.
Quality names still matter if you want to stay in the trade:
- $XOM — scale and assets still the cleanest way to own the theme
- $CVX — balance sheet and free cash flow look better than most
- $COP — pure-play torque without the integrated noise
- $EOG — still one of the better operators in the shale patch
- $MPC — refining strength is real right now, not just a one-day pop
As long as oil holds and the geopolitics stay supportive, this is the tape that matters. Everything else is just noise until it proves otherwise.
NFA. What are you watching inside energy?
Pre-Market Focus |
Earnings are out.
The chip selloff isn’t.
Key names on watch:
• $JPM / $GS — Post-earnings reaction | Watching whether the initial dip gets absorbed or turns into sustained selling
• $UNH — Relative strength after raised guidance | Still sensitive to rates
• $XOM / $CVX — Oil bid cooling slightly | Watching if energy can hold yesterday’s rotation
Macro/Rates context that matters:
10Y yield eased to ~5.19% overnight as the global bond selloff lost some momentum. Still high enough to pressure longer-duration growth. Memory and chip names remain under pressure on Chinese competition headlines (CXMT).
Setups into the open:
1. Financials — Watch if $JPM/$GS can reclaim premarket lows. Failure to hold opens further downside into the cash session.
2. Semiconductors — Continued weakness in $MU and the broader group. Only interested if we see real absorption near yesterday’s lows; otherwise stay defensive.
3. Energy — $XOM/$CVX holding the prior day’s bid despite oil pulling back. Invalidation on a clean break of yesterday’s lows.
Tape will decide. Charts + Logic.
Not financial advice.
@lilmays29 Agreed. 10Y easing helps a little, but it’s still high enough to keep duration under pressure. Memory names are feeling that China heat the most right now.