Example (Real Case):
In the Apple–Ireland case, the European Commission found that Apple’s internal prices were not set according to the Arm’s Length Principle, allowing profits to shift to low-tax jurisdictions. This principle ensures that multinational companies trade with their subsidiaries as if they were unrelated. #ArmsLengthPrinciple #TransferPricing #TaxLaw #InternationalTax #OECD #TaxTreaty @elonmusk
Example (Real Case):
In 2016, the European Commission ruled that Apple’s tax arrangements in Ireland involved improper transfer pricing, allowing the company to shift profits artificially and avoid paying billions in taxes. #TransferPricing#TaxLaw#InternationalTax#TaxTreaty #OECD #ArmLengthPrinciple @elonmusk
Example (Real Case):
In 2020, an American company and the German tax authorities disagreed on transfer pricing adjustments. The case was resolved through the Mutual Agreement Procedure under the US–Germany tax treaty, eliminating double taxation. #MutualAgreementProcedure#MAP #TaxTreaty #DoubleTaxation #InternationalTax #TaxLaw @elonmusk
Example (Real Case):
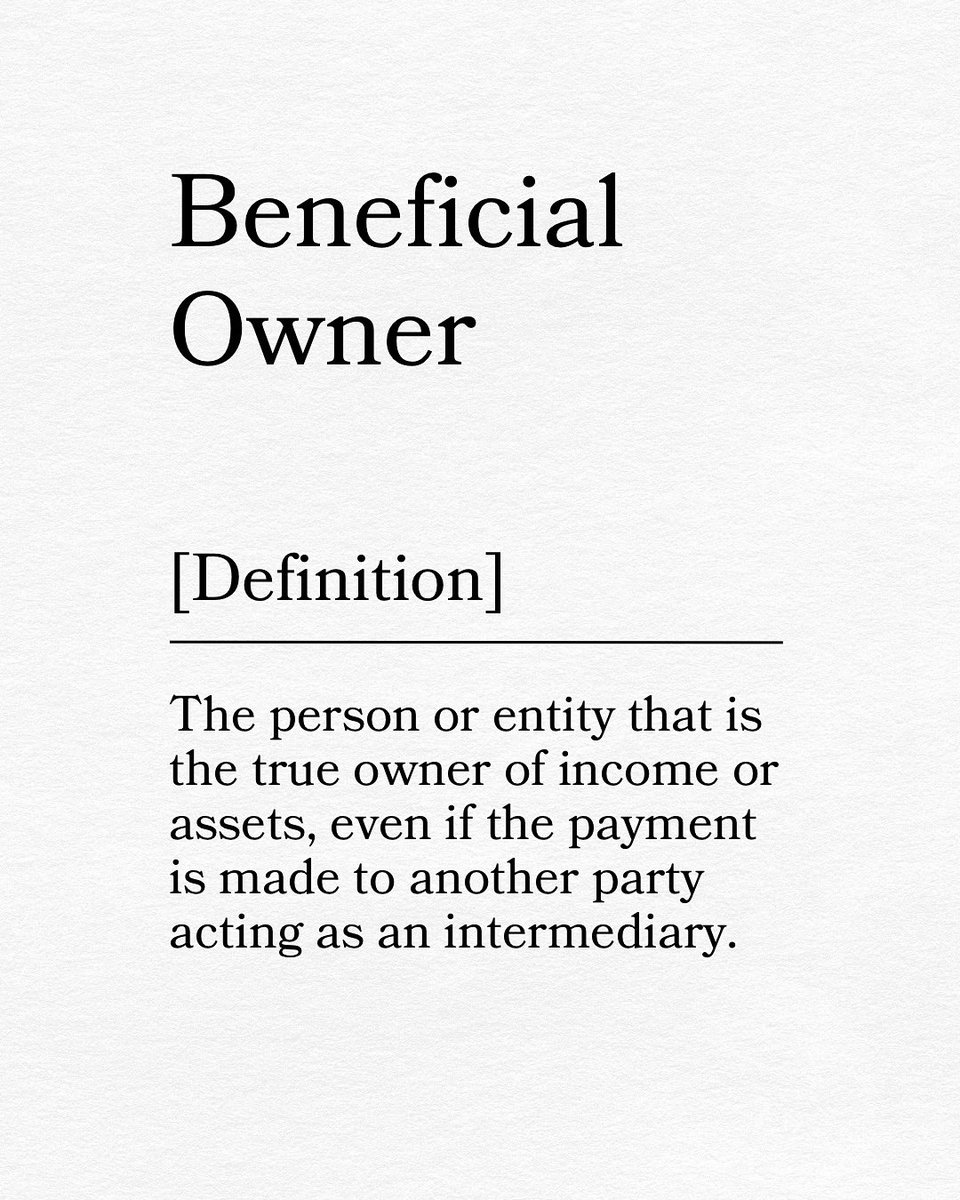
In 2017, the Danish Supreme Court denied treaty benefits to companies in Luxembourg because they were not the beneficial owners of dividends received from Danish subsidiaries. The real control and benefit went to parent companies in third countries. #BeneficialOwner #TaxLaw #InternationalTax #TaxTreaty #OECD @elonmusk
Example (Real Case):
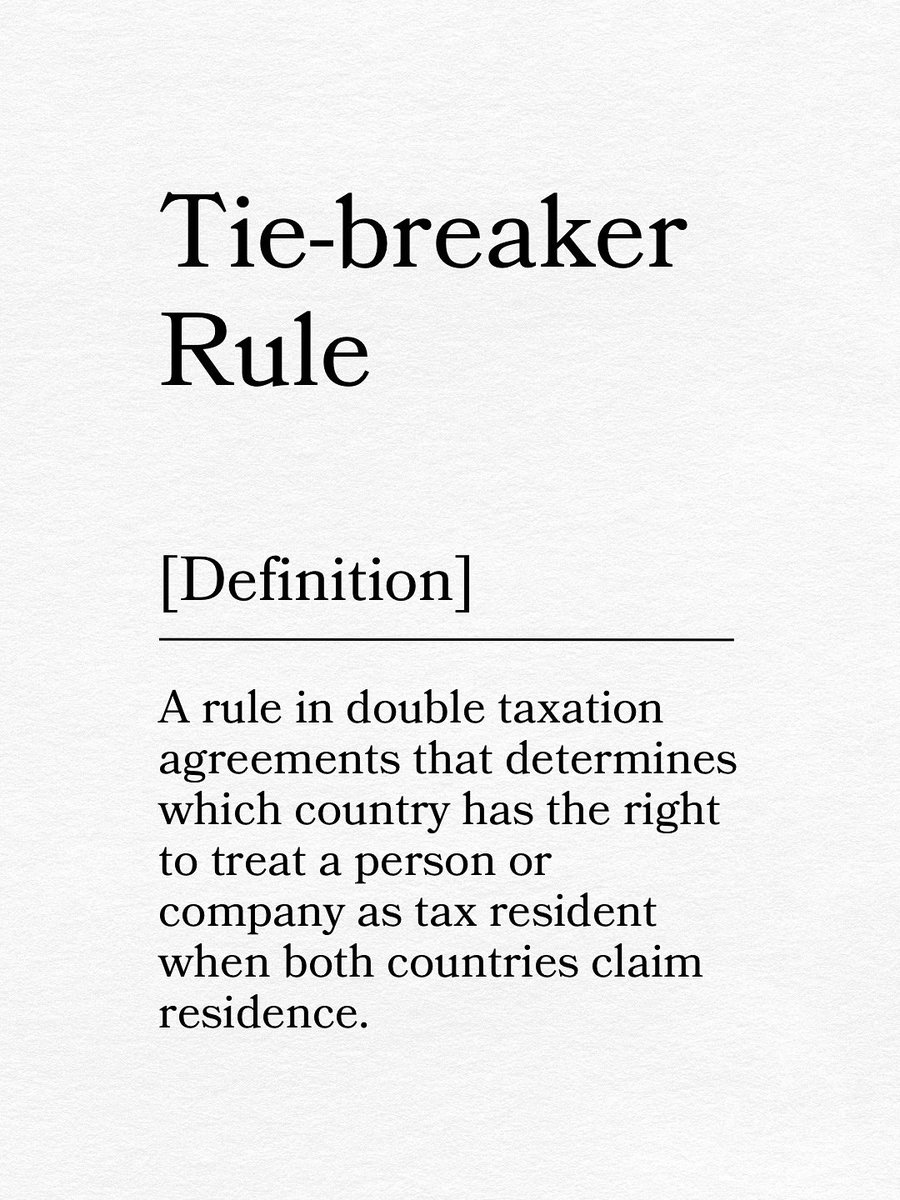
In 2019, a French engineer working in both France and Switzerland was considered a tax resident in both states. The tie-breaker rule in the France–Switzerland tax treaty resolved the issue by assigning residency to Switzerland based on his permanent home and closer personal ties.
#TieBreakerRule #TaxTreaty #DoubleTaxation #InternationalTax #TaxLaw @elonmusk
Example (Real Case):
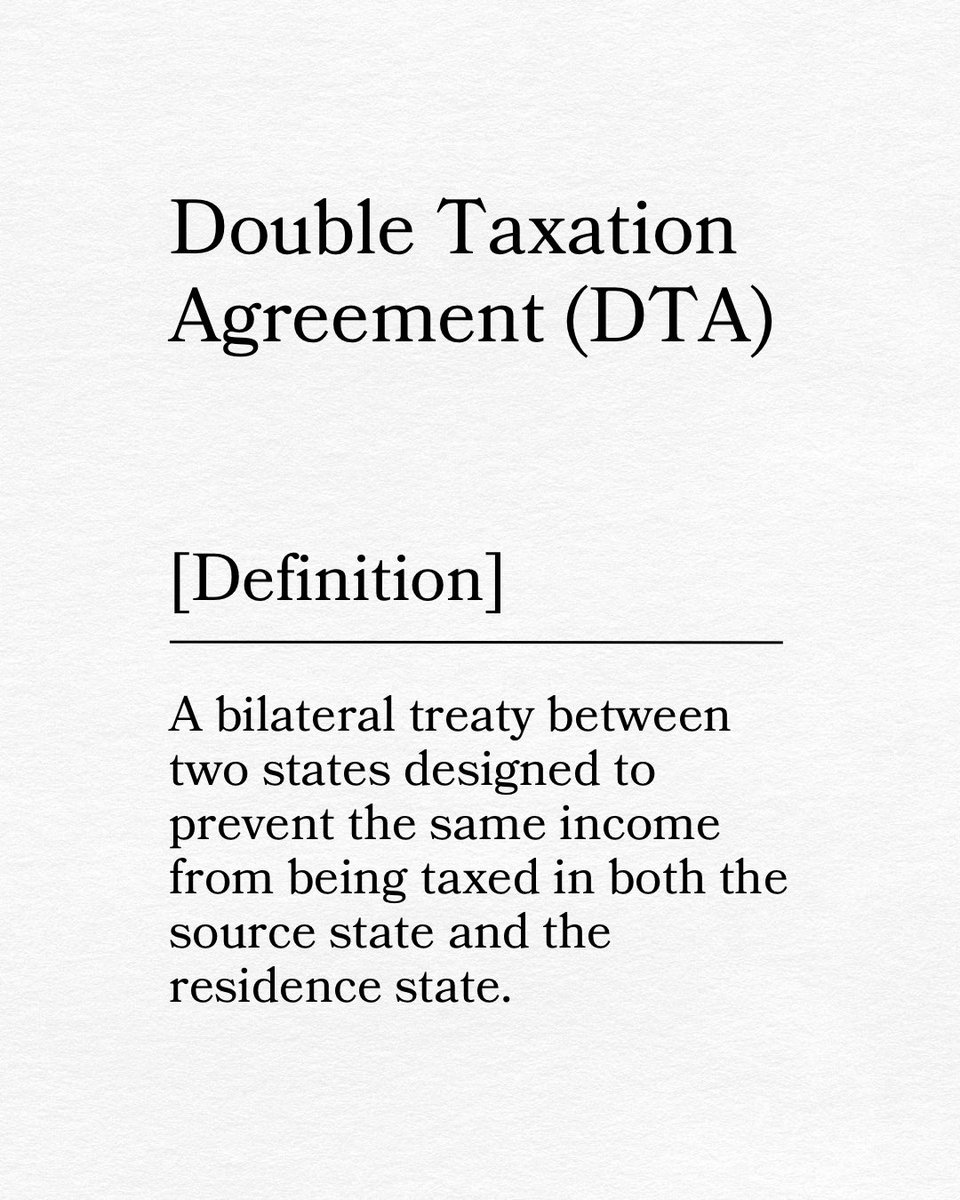
In 2021, India and the United States amended their Double Taxation Agreement to address issues of digital taxation, ensuring that tech companies like Microsoft and Amazon would not be taxed twice on the same income in both countries.
#DoubleTaxation #TaxTreaty #InternationalTax #TaxLaw #OECD @elonmusk
Example (Real Case):
In 2021, the French tax authorities applied a withholding tax on dividends paid by a French company to a shareholder in Luxembourg. The dispute was later brought before the Court of Justice of the European Union (CJEU) for breach of EU non-discrimination rules.
#WithholdingTax #TaxLaw #InternationalTax #TaxTreaty #OECD #WordOfTheDay @elonmusk
Example (Real Case):
In 2023, the Indian tax authorities argued that Google Ireland had a permanent establishment in India because it earned advertising revenue through local offices, even though the contracts were signed abroad. #TaxLaw#InternationalTax#TaxTreaty #PermanentEstablishment #OECD #WordOfTheDay
🚨🇺🇸🇨🇦 CANADA HITS BACK: TRUDEAU ANNOUNCES RETALITORY TARIFFS TO START TOMORROW
Canadian Prime Minister Justin Trudeau slammed the Trump administration’s 25% tariffs on Canadian exports and 10% tariffs on energy, calling them “unjustified”.
In retaliation, Canada will impose its own 25% tariffs on $155 billion worth of U.S. goods, with $30 billion taking effect immediately.
Trudeau warned tariffs will increase prices for Americans and violate Trump’s own trade deal.
Source: @BRICSinfo