🇺🇸 NFP beat forecasts: 165K vs 65K. But can we trust the headline?
Unemployment fell to 4.1%, wages rose 0.4%.
Strong jobs revive December hike bets, just as the Nasdaq's AI sell-off raises growth concerns. A tricky mix for the Fed.
🇺🇸 A divided Congress could limit major fiscal expansion.
Less government borrowing pressure may ease concerns around Treasury supply and long-term yields.
That's an important part of the USD story. Watch the bond market, not just the headlines.
🇬🇧 BoE hiked to 4.00%, but the interesting detail was the 8–1 vote. One member wanted 50bps.
With UK inflation still at 3.5%, markets are looking beyond this hike and pricing the next move.
How much more tightening can GBP sustain?
₿ Bitcoin is increasingly behaving like a risk asset, not just digital gold.
A weaker USD and lower yields may help, but sustained upside needs liquidity and fresh institutional demand.
Will BTC benefit if risk appetite returns?
🇬🇧 Sterling is gaining ahead of the BoE decision.
Markets are looking at a potential UK rate hike while US rate expectations are being reassessed.
That's the FX equation: it's not just where rates are, but where they're expected to go relative to each other.
🇺🇸 The midterm result is changing more than political headlines.
Markets are reassessing future government spending and Treasury supply. Less fiscal expansion could mean less pressure on yields.
That's one reason the USD is losing ground.
The bond market is telling the story.
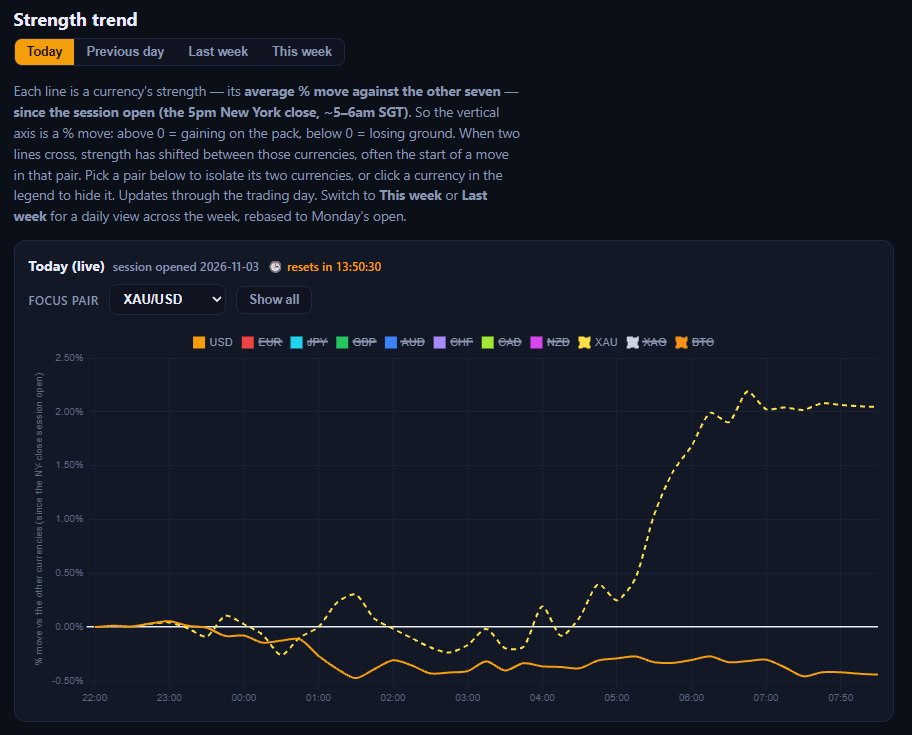
🥇 Gold is back above $3,950 after Friday's flush to $3,875.
Dip-buyers have stepped in, but US yields near 5.15% are still a headwind.
Next test: $3,980–$4,000. Can gold reclaim it?
🇦🇺 RBA hiked 25bps, exactly as expected. So why is AUD falling?
Because markets trade future expectations, not yesterday's decision.
The hike was priced in. Now traders are questioning how much further the RBA can go.
Good news isn't always bullish for a currency.
US midterms are underway.
For USD, the real question is whether it changes expectations for fiscal policy, Treasury yields and the Fed's rate path.
Watch DXY and US 10Y yields closely.
If yields don't confirm the dollar's move, I'd be cautious about chasing it.
Germany's Q3 GDP grew just 0.1%, missing the 0.3% forecast.
Another reminder that the Eurozone's growth problem hasn't gone away. With the ECB holding rates, weak growth could limit how much support EUR gets from monetary policy.
Is the market underpricing Europe's growth risk?
🇨🇦🇳🇿 Two central banks, two very different messages.
The BoC hiked to 2.50%. The RBNZ held at 2.75% in a tight 4–3 vote.
That divergence matters for CAD and NZD: markets are repricing very different rate paths.
Would you still buy NZD against CAD?
🥇 Gold is bouncing, but don't mistake relief for recovery.
It's still below $3,920–$3,950 resistance. Friday's sell-off exposed how quickly higher rate expectations can hurt non-yielding assets.
The December Fed hike is still ~84% priced in.
Can gold reclaim $3,950?
Last week, The RBNZ surprised markets by holding at 2.75% when a hike to 3.00% was expected.
NZD took a sharp hit as rate expectations were repriced.
A reminder: currencies move on the gap between what markets expect and what central banks deliver.
🇺🇸 The Fed held rates, but 2 officials wanted a hike.
With December hike bets still elevated, the dollar remains sensitive to inflation data.
Warsh is offering less forward guidance. Markets must read the data for themselves.
https://t.co/9g647oc442
🥇 Gold fell 3.6% as the tech sell-off triggered forced selling and margin calls. Even safe havens aren't immune when funds need cash.
Now the question is where buyers step back in. I'm watching $3,850.
https://t.co/WPSNx2dEgF
🇺🇸 Fed hike bets sit around 78–85%, while a December ECB hike is also firmly in play.
That sets up a potential EUR/USD tug-of-war. What matters isn't just who hikes, but whose expected rate path shifts more.
Which central bank will surprise markets?
🇪🇺 Germany's inflation is expected to ease from 3.3% to 3.0%.
But softer CPI doesn't automatically mean a weaker euro. Markets are still weighing a possible December ECB hike.
Will inflation data change the rate outlook—or keep EUR supported?
🇦🇺🇳🇿 The RBNZ hold just sent NZD tumbling.
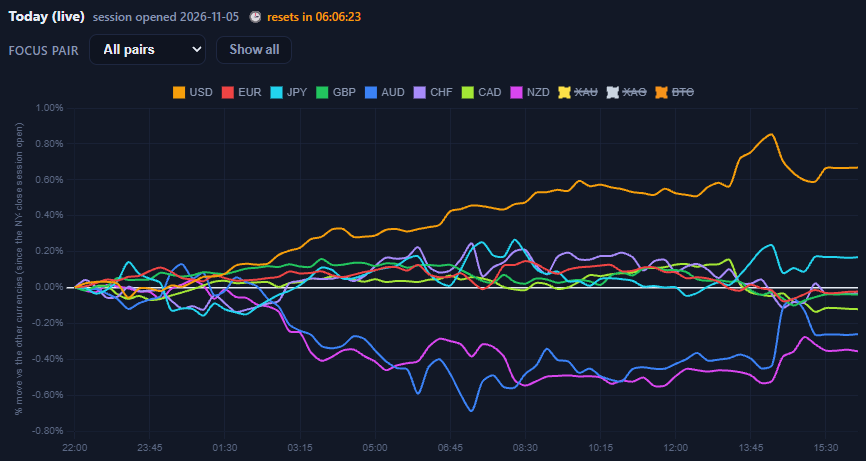
FXStrength's live meter shows AUD up ~0.4% while NZD drops ~1.35% against the session open.
The surprise wasn't just the decision. It was what markets expected versus what they got.
Did you catch the shift?
🇦🇺 Aussie CPI surprised higher: 4.3% y/y vs 4.2% expected.
🇳🇿 But the bigger surprise? The RBNZ held at 2.75%, against expectations of 3.00%.
With inflation still a concern, what did the RBNZ see that markets missed? NZD traders, the statement matters now.
🛡️ DXY is holding near 102, but a firm USD doesn't tell the whole safe-haven story.
USD, JPY and SGD react differently to risk, rates and capital flows. In a sell-off, they don't necessarily move together.
Know which kind of safety the market wants.
https://t.co/tb0OM4D3zB