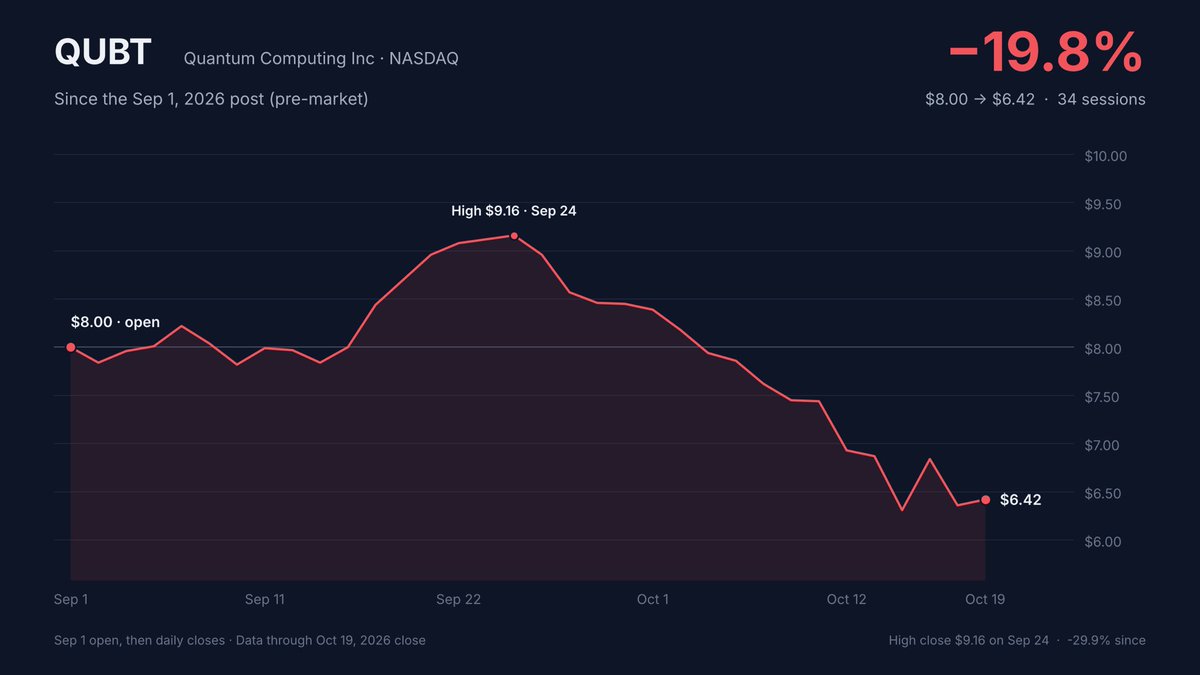
$QUBT is $6.42 today. It was $8 when I posted, so down 20%, and it got to $9.16 in late September before rolling over, which is the usual order of events.
The part I keep coming back to: $1.3B of the market cap was just cash from selling shares. That number doesn't move. Everything the market was paying on top of it did, from roughly $600M to roughly $200M, if the share count's about where it was.
So the quantum premium is mostly gone. The cash is still there.
qubt is a $1.9B 'quantum' company where the revenue growth came from buying a chip fab and ~$1.3B of the cap is cash from stock sales. also a securities fraud class action is pending in NJ federal court over its NASA + foundry claims. what exactly are you buying here. $QUBT
Seven weeks ago I said $OKLO was a skyscraper price for a blueprint. $7.5B for $1.2M of revenue.
Since then it's gone $39 to $27. Down 31% from the post, 37% from the Sep 8 high. Same blueprint, lower price. Call it ~$5B now, if the share count hasn't moved.
The AI-needs-nuclear story is still true. It was never the problem. The price was.
the market says $OKLO is worth $7.5 billion. its revenue over the past year: about $1.2 million. its losses: $153 million. it has never switched on a reactor. the AI-needs-nuclear story is doing all the lifting here. that's a skyscraper price for a blueprint.
Well. I said the $GPRO squeeze was a rescue plan and they'd sell stock into it. Turns out they sold the whole company into it instead. $1.14 cash and a sliver of whatever Starman turns out to be, announced the same morning I posted this.
Then a week later, a $20M Yorkville convertible priced off the pump. So fine, they did sell stock into it. Just with a lawyer in the room.
Stock's at $1.04 now, below the cash in the deal, after a restatement and some loan covenant defaults last week. Right about the ending, wrong about how they'd get there.
$GPRO went from 61 cents to $1.60 in two days because a YouTuber bought shares. The company has $27M in the bank, $86M of debt, and lost $162M in the past year. The CEO lent it $20M in July. Management's rational move? Sell stock into the pump. The squeeze is the rescue plan.
$RGTI is a $5.2 billion company. it makes $5.1 million a quarter and loses $52 million a quarter. it loses about $10 for every $1 coming in. at today's sales rate the valuation equals 250+ years of revenue. and the CEO says error-corrected quantum is still ~4 years away.
$ARQQ, 31 trading days after the entry.
20.30 → 14.02 at Monday's close.
It squeezed to 24.64 on Sep 28 first, then gave back 43% from there.
−31% from entry.
$CBRS short watch: ~49x EV/FY26 guided non-GAAP core revenue, with lockup releases Sept 16 and 30. Potential supply could test the valuation over 2-4 weeks. I’d wait for a failed rally: shares becoming sellable doesn’t mean holders will sell.
@r_nvmber@niccruzpatane There is so much that you have assumed in order to make this straw man argument, you’re arguing against points that haven’t been made.
@Stano251@niccruzpatane No one is saying it’s not innovation but these cars will not be used on public roads, and they are absolutely louder than the legal requirements for cars.
@famigami@niccruzpatane Ear muffs can also be used for sound, but you’re right in this case it was earplugs.
However, I’m not sure you understand just how loud the thrusters are. There are already laws related to how loud car engines can be, and the thrusters would far exceed these laws.
I said he’s still 100% correct.
I’m not saying he always will be, or that we will NEVER see any flying car on the road.
I’m just saying the roadster event didn’t prove him wrong. Every complaint he has about flying cars is still true, and we’re not gonna see flying roadsters driving around public streets.
@niccruzpatane He’s still 100% correct. The crowd was given ear muffs because this car is loud. The rocket version of the roadster is invite only, we aren’t going to see these on the road.
$CBRS short watch: ~49x EV/FY26 guided non-GAAP core revenue, with lockup releases Sept 16 and 30. Potential supply could test the valuation over 2-4 weeks. I’d wait for a failed rally: shares becoming sellable doesn’t mean holders will sell.
$ADBE long watch: Sept 4’s 6.7% drop after CEO succession news left shares at ~15x FY26 GAAP EPS guidance. Sept 10 earnings are the test. If recurring-revenue growth holds up, the headline discount could unwind over 2-4 weeks.
@xwdlm35478999 "On sale" at 60x trailing sales? $IONQ: ~$15.5B market cap, $246M TTM revenue. Q2: $80M revenue, -$120M adj. EBITDA, -$1.87B GAAP (mostly non-cash). Share count +50% in a year. Analysts see a $900M loss in 2028. Down 54% from $84 is a markdown, not a bargain.
Arqit ($ARQQ) is a $330M company that generated $623,000 of revenue in its latest half year.
Eleven contracts, averaging $57K each. About 300x trailing sales. It’s my current short, and the calendar matters this week.
Disclosure up front: I am short.
Thread.