Muse saved me a big headache by waiting in line and chatting with a Booking customer service agent today. Prompted it to not make any changes/cancelation + provide a summary, which it did well
Still learning how to best use Muse in my investment process, though
@FinanceJack44 Some of us are talking about it!
I think most people understand that long term it could be a new, very profitable business segment. But prediction is hard and there’s a lot of competition. Also the short-term sacrifice is zero/negative FCF which impacts sentiment
Zuck: “Muse is very compute-intensive to run, but we expect to improve its cost efficiency by more than 10x in the next year, which will enable it to be profitable once the revenue lines are at scale.“
$META
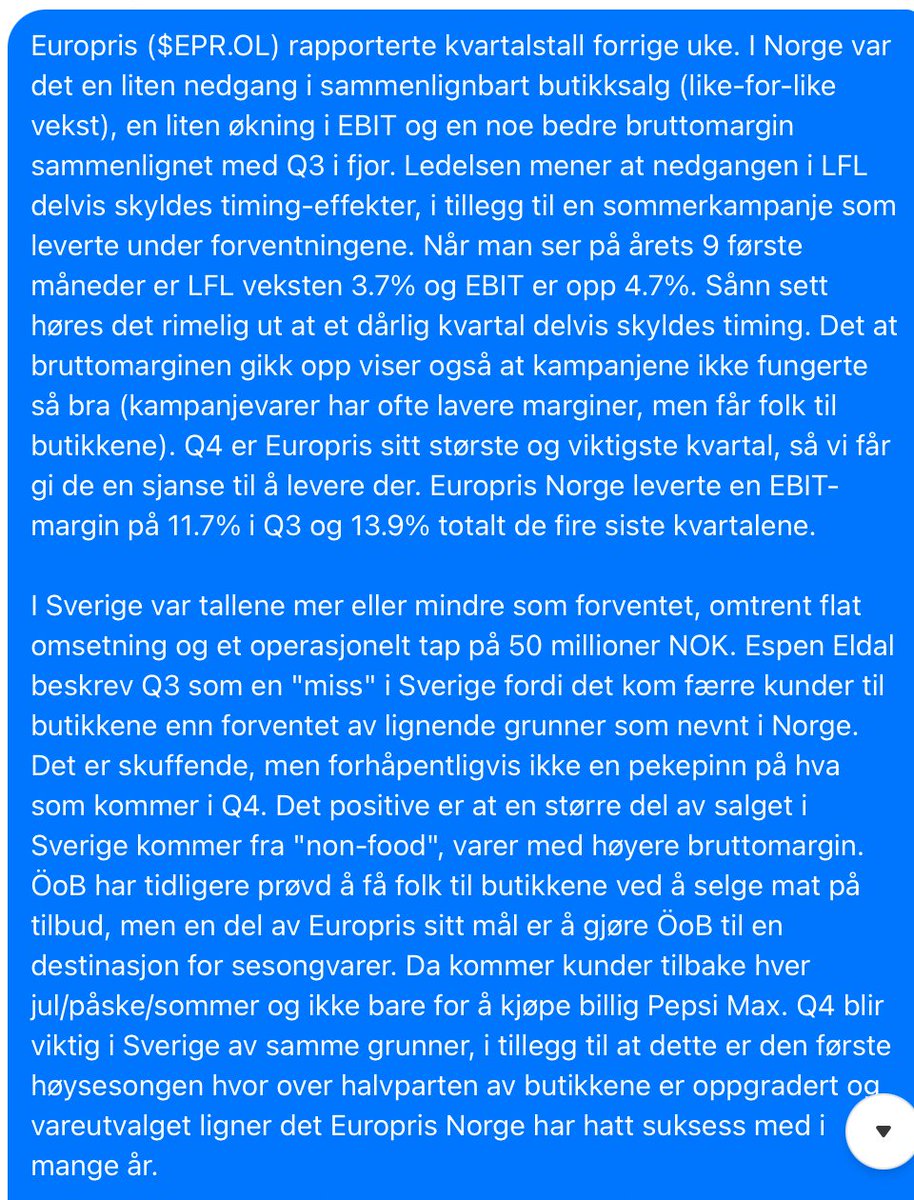
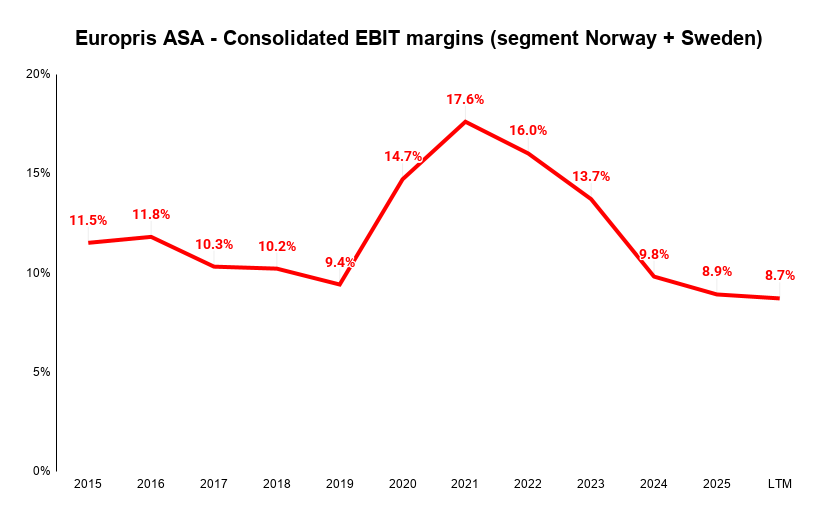
@CoalemusGuy Enig og er glad ledelsen var såpass ærlig på kvartalspresentasjonen også. Q4 er historisk over dobbelt så stort (EBIT i Q3 i fjor var 293 mill, Q4 var 648 mill), så håper en god julesesong gjør opp for det!
$EPR.OL Europris rapporterte Q3 forrige uke:
-0.1% sammenlignbar vekst i Norge
+0.5% EBIT
Første 9M av 2026 var bedre
+3.7% sammenlignbar vekst
+4.7% EBIT
Dårlig Q3 delvis pga timing, men også en kampanje som leverte under pari
Q4 er mye viktigere, håper de får ordna opp 🤷♂️
I Sverige var mye som forventet, mer eller mindre flat omsetning og et negativt driftsresultat
Espen Eldal beskrev det som en "miss", noe som er litt bekymringsverdig før julesesongen. Positivt at "non-food" salg er opp og at vareutvalget er oppgradert før jula
@LeonineT4 I pretty much just drink black coffee. And I enjoy the opportunity to get free refills and a mug when sitting down at a Starbucks. Definitely agree that you can get better flavored coffee elsewhere, though
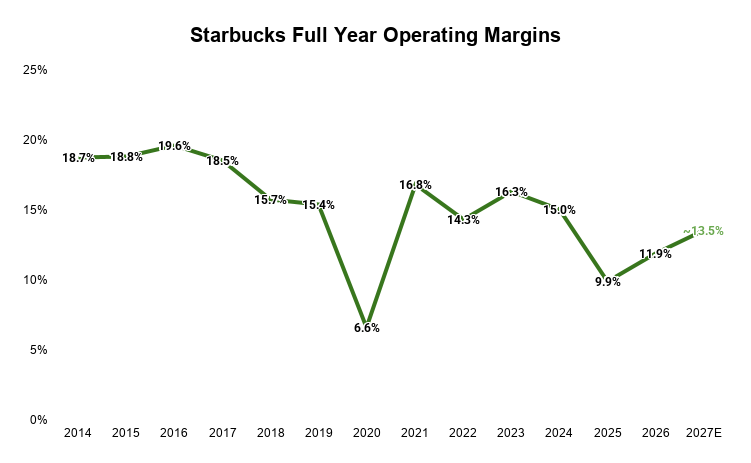
"Back to Starbucks" is starting to show up in the numbers
Full-year operating margin increased 2 percentage points to 11.9% and management is guiding for 13.5–14.0% in FY27
$SBUX
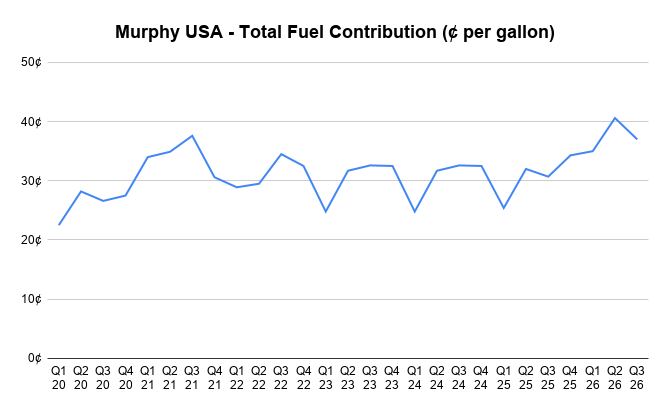
$MUSA CEO: "What our third quarter results tell us is that we took share on both a total gallon basis, but also a same-store basis as we were plus 6% versus OPIS [retail fuel market data]"
In hindsight, I feel like a genius for trimming 1/3 of my $GOOG shares at $401 in May
In hindsight, I feel like an idiot for keeping 2/3s of my $GOOG shares
"For the full year 2026, Amphenol expects sales to be in the range of $36.9 billion-$37.1 billion, representing an approximately 60% increase [YoY], while Adjusted Diluted EPS is expected to be in the range of $2.82-$2.84, representing an approximately 70% increase.."
$APH
Moody's anticipates >$1 trillion in hyperscaler capex in 2027:
"They [ratings analysts] expect that to grow to somewhere $1 trillion or more. What that tells you is we expect that there will be continued growth in the hyperscaler issuance and AI infrastructure build-out"
$MCO
New CEO started at the beginning of this quarter which will hopefully reduce some of the noise.
In hindsight I sized the position wrong (~9% of portfolio), but I feel pretty good about the stock here. Happy to listen to other perspectives
My $ABG.OL shares are ~flat since I first bought around 2 years ago, excluding a 7.5% dividend yield
The stock hasn't worked even though corporate financing + M&A ⬆️ since the '22-'24 downcycle
2-yr revenue growth +32.6%
2-yr EPS growth +37.7%
Stock trades at 9.7x trailing EPS