$VKTX - it could be a change of plan: the board may be leaning toward a partner or a sale, which makes a launch-building executive unnecessary. That would be good for the buyout scenarios for $VKTX.
or there could have been a disagreement or a poor fit: he and $VKTX CEO may have differed on the launch plan or its budget.
@BluntForceOpt $ARVN - the revenue is really capped because of the choices they’ve made please review their prospectus and do proper due diligence before investing into it. There is not much upside left and it’s not me saying it’s the company itself has made it clear on their prospectus.
$VKTX - Look at the pattern below. The obesity challengers are down 3-6%. The obesity leaders are flat. Broad biotech is down 1%.
Today's performance:
$VKTX -5.50%
$GPCR (Structure) -6.20%
$ALT (Altimmune) -3.10%
$XBI (biotech) -1.20%
$MDGL -0.30%
$NVO -0.60%
$LLY -0.20%
This isn't risk-off or a biotech selloff. The market is specifically repricing the companies trying to become the third player in obesity.
What's driving it? - Retatrutide.
$LLY published full TRIUMPH data in NEJM and The Lancet on September 29 - 28.3% weight loss at 80 weeks, 30.3% in the severe-obesity subset at 104 weeks, with 65% of patients dropping below a BMI of 30. Those papers reach the full physician and investor audience, not just people who read the press release.
Two days later, every obesity challenger is selling off together. That's the market digesting what a 28–30% benchmark means for everyone trying to enter with a 20–22% drug.
When the whole challenger cohort sells off on a leader's data, the market isn't questioning $VKTX's execution. It's questioning whether a third entrant has a business at all.
$VKTX - Look at the pattern below. The obesity challengers are down 3-6%. The obesity leaders are flat. Broad biotech is down 1%.
Today's performance:
$VKTX -5.50%
$GPCR (Structure) -6.20%
$ALT (Altimmune) -3.10%
$XBI (biotech) -1.20%
$MDGL -0.30%
$NVO -0.60%
$LLY -0.20%
This isn't risk-off or a biotech selloff. The market is specifically repricing the companies trying to become the third player in obesity.
What's driving it?
Retatrutide. $LLY published full TRIUMPH data in NEJM and The Lancet on September 29 - 28.3% weight loss at 80 weeks, 30.3% in the severe-obesity subset at 104 weeks, with 65% of patients dropping below a BMI of 30. Those papers reach the full physician and investor audience, not just people who read the press release.
Two days later, every obesity challenger is selling off together. That's the market digesting what a 28–30% benchmark means for everyone trying to enter with a 20–22% drug.
When the whole challenger cohort sells off on a leader's data, the market isn't questioning $VKTX's execution. It's questioning whether a third entrant has a business at all.
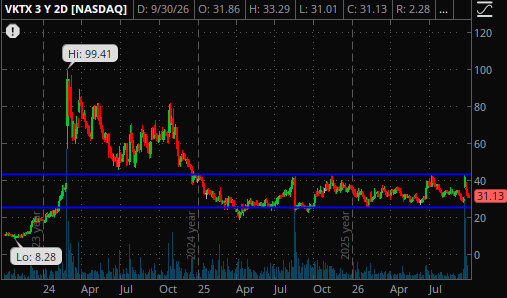
@ACInvestorBlog $VKTX - the price's breaking down with sellers outpacing buyers by a wide margin. I think next support is at the lower end of the 3-yr channel ~$25-$27
$LEGN - You are right on point. That's the plus on Carvykti's side versus anito-cel which does not have long-term follow-up data so far.
Also, anito-cel, though I think it will get the approval on Dec 23rd --> it is still 4th line+ and TAM is extremely small, not to mention 4th line is a very small fraction of $LEGN's current revenue mix and $LEGN is already moving more and more into earlier lines.
Anito-cel's earlier lines are going to hit the market probably late 2028 or early 2029. Hopefully, by then Carvykti's frontline data lands and $LEGN moves aggressively into frontline, which is where the biggest commercial opportunity is. $LEGN needs to win-out the catch-up game!
$LEGN - Legend Biotech's 3-yr slide isn't management competence or being unaware - it's two stories running in parallel. Operationally they delivered: capacity doubled (2023), doubled again (2024), 2L approval landed, revenue scaled to $1.27B TTM at 52% growth, first profitable Q just hit. What
$LEGN haven't out-executed is the safety narrative. Parkinsonism → CNP → IEC-EC added to the boxed warning one quarter at a time, while the public defense (the "0.5%" framing, pulling the ASH head-to-head vs anito-cel) read more like managing the message than contesting it.
The $LEGN CEO exit is the tell - abrupt resignation, no explanation, 7-week vacancy, at the exact moment the company needed a steady hand on the single biggest open question (competitive safety positioning ahead of Dec 23), and a successor pulled from Novartis commercial rather than R&D or medical affairs - that's a board signaling "defend the launch and the market," not "win the scientific argument." Reasonable boards can make that choice. But it's a 'tell' about what they think the fight actually is, right when the scientific argument is what Dec 23 turns on.
$LEGN stock price is down not because Revenue failed. The safety story is doing the real damage.
$LEGN - Your math is right on paper: $LEGN appears inexpensive on both headline and cash-adjusted metrics: its market capitalization is roughly 2.8x trailing sales, while its enterprise value is about 2.3x sales after accounting for $3.71 per share of net cash. Those multiples are low for a newly profitable company growing around 50%, for example: $IOVA, which trades near 14x sales despite operating from a smaller, earlier-stage base- although it currently faces no approved competitor in its indication.
The valuation gap appears to reflect the uncertainty surrounding anito-cel’s Dec. 23 PDUFA and its potential challenge to Carvykti. Anito-cel claims zero delayed neurotoxicity, while Carvykti carries boxed-warning language for parkinsonism, enterocolitis, and increased early mortality in CARTITUDE-4; a recent EMA safety study also reported a 14.2% rate of cranial nerve palsy in routine care, above the clinical-trial rate though most of the cases resolved eventually through proper intervention and secondary care.
The investment case therefore turns on the competitive picture after Dec. 23: if anito-cel’s launch falters or Carvykti’s safety profile remains competitive, LEGN could re-rate sharply; otherwise, even a 2.3x multiple may not be cheap.
$LEGN - I hear you but all that you said has gotten only a big yawn from the market so far. Uncomfortable truth is that it's been sliding that way since mid-2023 other than a few quick pops which fizzled in quick tandem! hopefully $LEGN finds its footing and turns for good...after all these years!
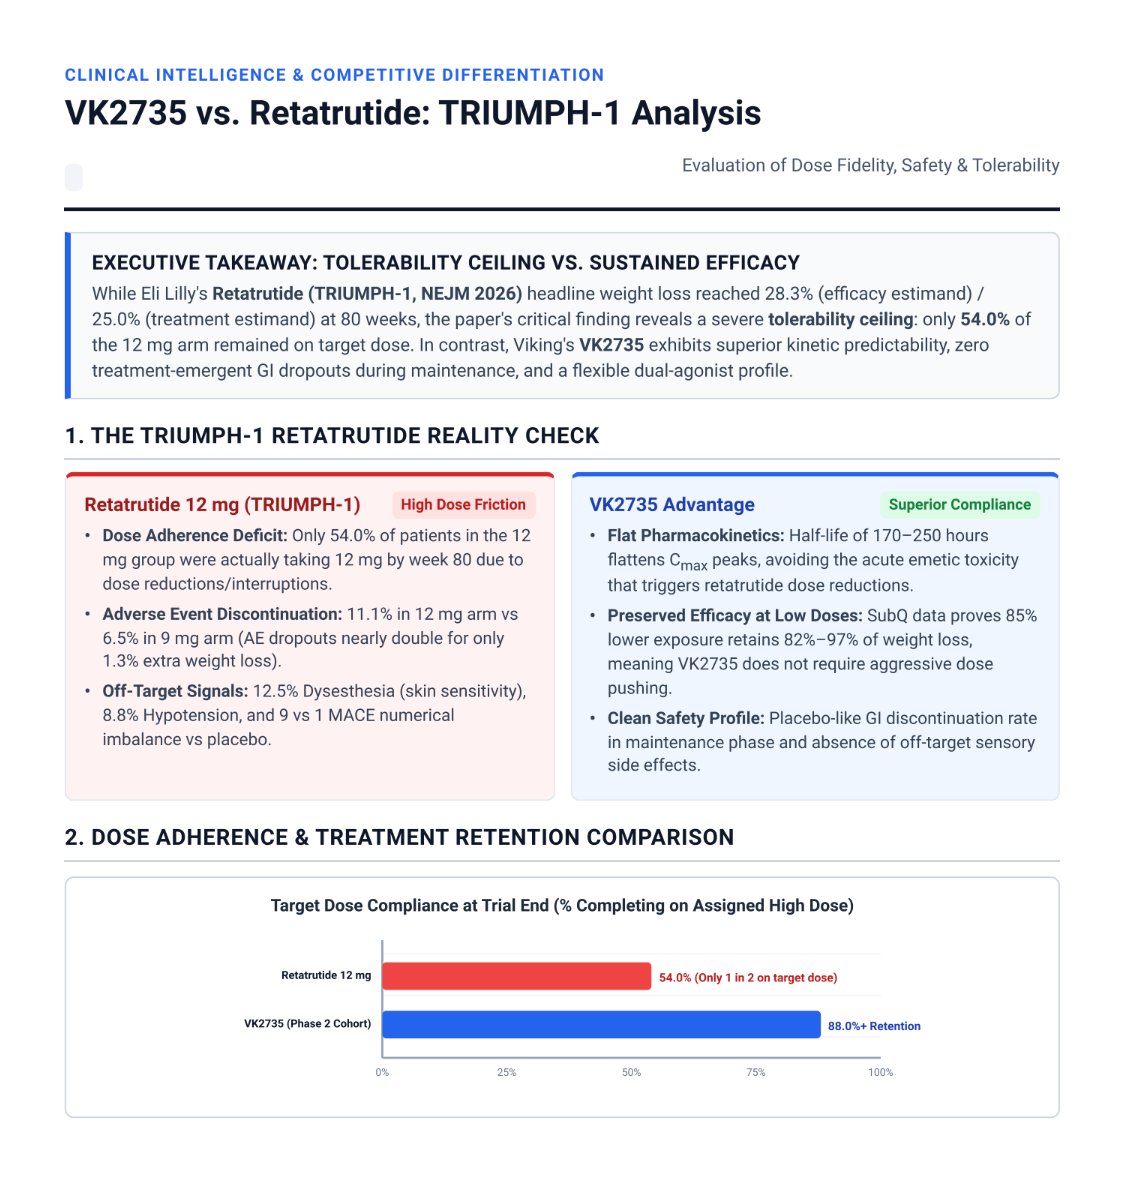
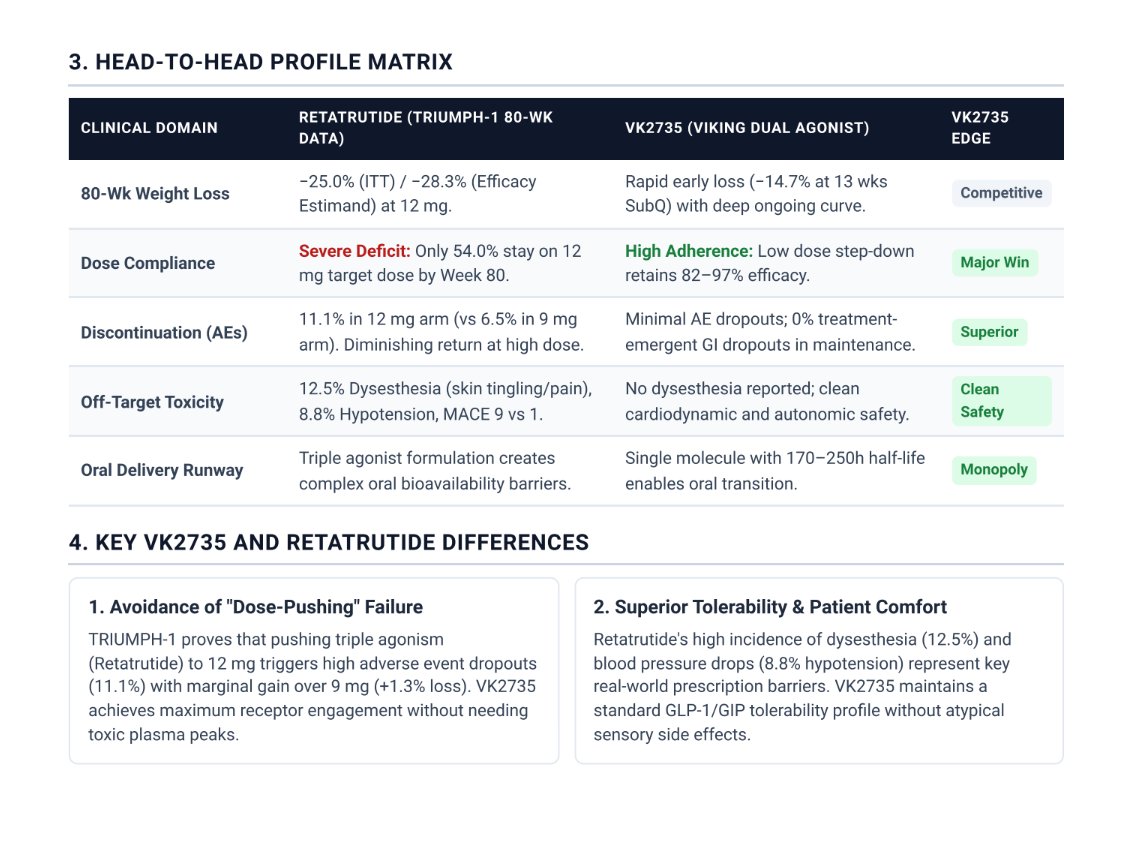
$VKTX @Doctor_Salomon put together a comparison between $LLY's Reta and $VKTX's VK2735.
Sharing for those who don't want to click through to Google Drive links.
$NVO
$VKTX - Morgan Stanley and J.P. Morgan are flagged on the chart as joint bookrunners. Canaccord and H.C. Wainwright were co-managers. Cantor has a long-standing relationship.
Goldman and Stifel are the two firms with no banking relationship to $VKTX. They're also the two rating it Hold and Neutral. That split is not a coincidence, and it's how sell-side coverage works everywhere!
The uncomfortable part: the excluded analysts have been the accurate ones. Goldman at $38 and Stifel near $35 are closest to where it trades. The $100+ crowd has been wrong for two years!
Good - that's Ortex, which changes my earlier point. short interest runs on a two-week FINRA lag; Ortex models it daily from securities-lending data, so this is post-data and post-close. Correction accepted on the timing.
The catch nobody will notice: the float denominator hasn't updated.
It's the same number all three days. But 9,035,714 new shares settled on September 25. Ortex is still using the pre-deal float.
Once the denominator catches up to roughly 122.7M, the same 23.96M short becomes about 19.5%, not 21.07%. So the headline figure is overstated by roughly a point and a half, and the apparent increase in percentage is partly an artifact of a stale denominator.
The share count is the real signal, and it's smaller than expected.
Shorts rose only ~720K shares from September 24 to 28. I'd estimate convert-arb hedging alone would add 2.5–3M shares on a $258.75M note deal.
$VKTX - When it lands it'll likely be higher, and here's the catch: the $258.75M convert brought arb funds who short stock to hedge delta. Call it 2.5 - 3M shares of new short interest that's a hedge, not a bear. Meanwhile the float grew 7.7% on the 9.04M new shares.
So, I expect the short Interest in $VKTX to go up unless the earlier shorts covered in panic when the maint. data was released.
The percentage gets distorted both ways, and everyone reads it as conviction shorting. 26M shares at ~3.5M ADV is ~7.5 days to cover - real fuel, but it needs a catalyst and there isn't one until Oct 28!
$VKTX - 21% short interest - Is that from the Sep' 15 settlement date?
Short interest isn't live. FINRA and the exchanges collect it on settlement dates twice a month and publish about eight business days later.
The data hit on September 22. The offering closed September 25.
Post data and secondary short info should be updated on or after Oct 8th imo.
@ChillBanking old news. $VKTX announced this trial's initiation on June 24, 2026 - three months ago. The press release described the same study, a randomized double-blind placebo-controlled SAD trial in healthy adults with BMI ≥30, following FDA clearance of the IND.