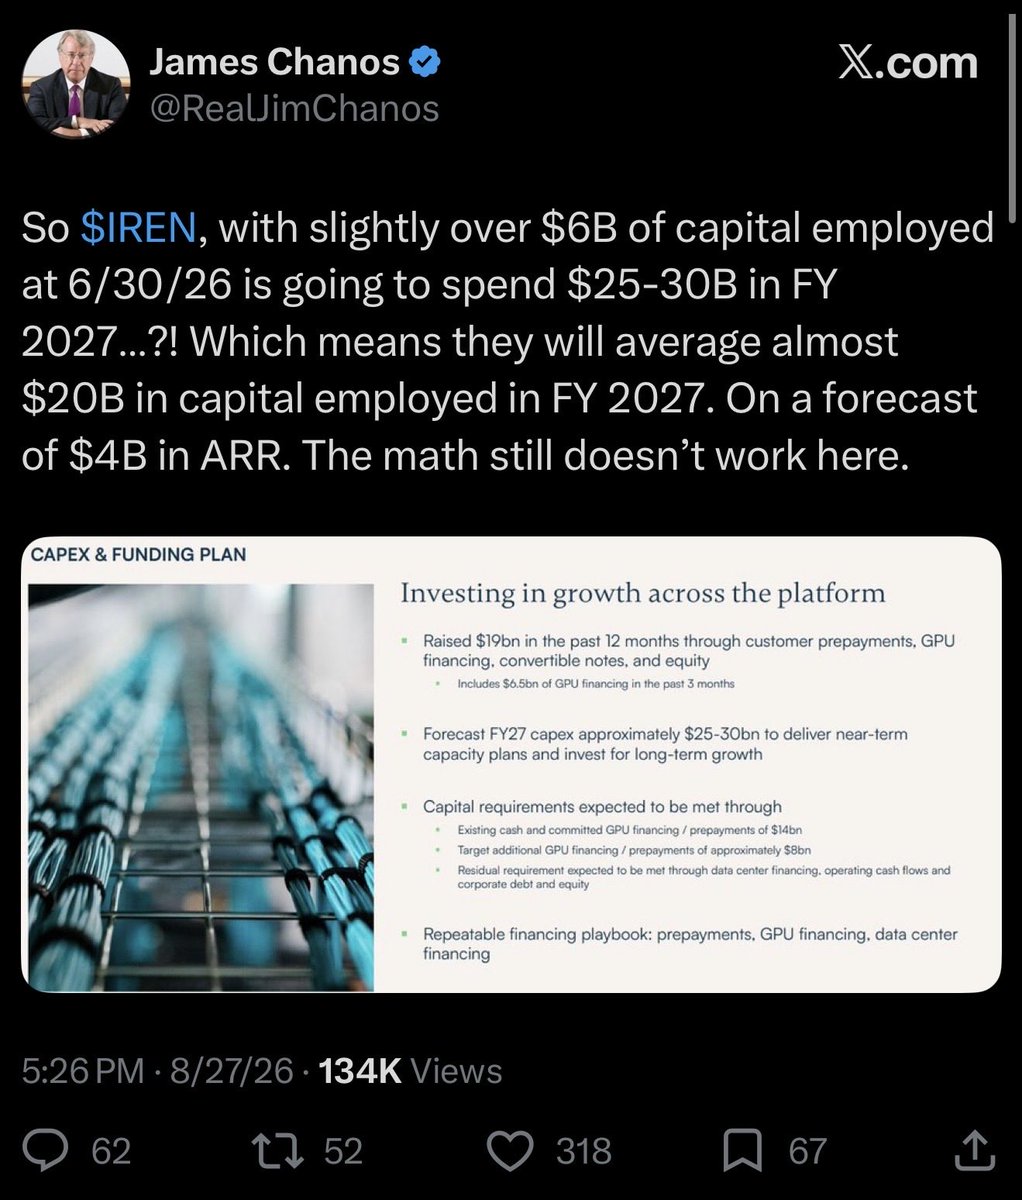
@RealJimChanos says $IREN bulls should stop leaning on ARR, $/MW and prepayments and look at the actual accounting.
So I did.
It got more bullish.
At June 30, IREN disclosed ~$5.1B of ASC 606 remaining performance obligations plus ~$11.4B of contracted arrangements under ASC 842.
That’s ~$16.6B of contractual obligations in the financial statements.
Then ~$2.8B of new contracts were signed in July.
Before assigning anything to the unnamed frontier AI lab announced in August, I can identify >$19.4B of contracted obligations.
I’m intentionally not calling all of that “backlog.” Different accounting, different durations.
That’s the point: you don’t need the ARR slide to find the demand.
The contracts are in the filings.
IREN also ended June with $1.84B of deferred revenue. Roughly $1.62B was advance payments on lease-accounted tranches that hadn’t even commenced.
Not profit.
Customer cash arriving BEFORE the asset starts producing revenue.
And this is where I think the dilution argument starts to break.
For Microsoft/Horizons:
~$3.6B of investment-grade GPU financing + ~$1.9B of Microsoft prepayments against a ~$5.8B GPU purchase agreement.
~95–96% of associated GPU capex funded.
For Mackenzie, the $2.4B financing alone funds ~90% of associated GPU capex.
Customer prepayments sit on top, pushing total GPU-linked funding above GPU cost and helping fund data-center capex.
Now FY27:
$25–30B capex.
~$14B existing cash + committed GPU financing/prepayments.
~$8B additional GPU financing/prepayments targeted.
That leaves a $3–8B gross residual BEFORE data-center financing and operating cash flow.
Meanwhile management says 100% of its data-center portfolio remains unencumbered — including Horizons 1–4, the 300MW gross / ~200MW IT Childress build supporting a $9.7B Microsoft contract.
Think about that structure.
The Microsoft compute layer is already ~95–96% funded.
The data-center layer is still available to finance.
So the first DC financing doesn’t have to solve a $30B problem.
It attacks the remaining $3–8B residual.
In the favorable end of my funding bridge, DC financing + ex-prepayment operating cash flow can take that residual close to zero before incremental common equity.
I’m not making that my base case yet.
But it’s a very different setup from “IREN needs to issue $30B of stock.”
Customer prepay → GPU debt → operating asset → DC financing/refi → recycle capital.
That’s the flywheel.
The point isn’t zero dilution.
It’s that common equity can become the residual funding rail instead of the primary one.
Now Chanos’ ARR/revenue point.
How can IREN target >$4B of operational ARR at Dec. 31 while sell-side FY27 revenue is only ~$2.5B?
FY27 runs July through June.
Dec. 31 is halfway through it.
The >$4B is the annualized rate of the operating fleet at that point. The first half is the ramp.
Different clocks. No contradiction.
His capex comparison has the same issue.
FY27 capex funds multiple vintages: finishing CY26, CY27 air-cooled deployments, major DC construction for H2-CY27 Childress/Sweetwater, plus early CY28+ work.
The GPUs for those new H2-CY27 liquid-cooled facilities aren’t even in the FY27 guide.
A multi-vintage construction budget divided by one earlier vintage of ARR will obviously make returns look bad.
The numerator and denominator aren’t the same assets.
One Chanos point I’ll give him (cont.)
$IREN @jimcramer I hate companies that are “losing so much money” into extremely valuable income producing assets with short payback periods and near infinite long term demand…. 🤡
Jim Cramer on $IREN Iren: “Iren is one of those stocks that is just really hard to own right now, particularly in light of the fact that it is a company that was blessed by Nvidia. And even though I did agree with you that the quarter wasn’t that bad, they are losing way too much money for me to endorse.”
Good for you on short but it has nothing to do with the company’s ability to execute. Their needs for atm to fund entire next year of plans is minimal. They have GPU debt to pull on credit worthy contracts like NVDA and they will soon be able to pull 2-3B from infra for Microsoft which is again credit worthy. They are also close to gettting 100% GPU capex prepays from clients. The demand for compute is still so strong they can pass along the “cost” of providing however they best need to. AND if times ever got really tough they have very valuable sites in pipeline they could sell or do more simple Colo to mitigate funding needs. They have many options available. All macro noise.
For anyone that needs a mindset shift after the worst PA imaginable for $IREN only lesson here for me was to always have more cash on sidelines for a worst case scenario.
The thesis for IREN has only strengthened overall. Markets can stay irrational for quite a time. Plenty of signs this a temporary setback. I can promise you buying $IREN today will be much better than hiding out in expensive “safe” stocks like Staples. Invest in the future and be patient. The rewards will come in time.
@Bonek2801 Selling at peak fear just makes you dumb. I did the research and know what I own. Does it suck right now? Absolutely. But it’s at least 3-4x undervalued so I still buy more when I can. Added this morning and last night.
Sentiment in $IREN is lower than I've ever seen. Price targets falling everywhere to match. One year ago, sentiment was at all time highs - it can change fast (in both directions). $IREN is pacing to ~10x+ operating ARR from ~$1B today to ~$10B+ by end of 2027 - either you think that will flip sentiment and drive multiples higher or you don't. The biggest question: will they get the money? Every channel check suggests customers are stepping in to fill the gap when lenders don't. Will they dilute to oblivion? The most recent earnings showed they have a path to not do that - either you believe @danroberts0101 or you don't. Do they have a moat / can they sustain a high multiple if we get high multiples again? 5+ GW of secured power with a ~35 GW development pipeline beyond is more than any hyperscaler has. Let it play out. NFA / DYOR.
https://t.co/TuN0ZQ87KN
@Bonek2801 Selling at peak fear just makes you dumb. I did the research and know what I own. Does it suck right now? Absolutely. But it’s at least 3-4x undervalued so I still buy more when I can. Added this morning and last night.
$IREN
I thought Kent made some very revealing comments on this interview that are very bullish and completely refutes the "nO MoRe cApiTal!" sentiment in the markets right now. Two in particular were key take-aways for myself.
1. Kent was very confident about the GPU debt markets remaining open to IREN
Quote:
"Similarly, on the GPU debt financing side, where we've raised over $6 billion in the last number of months, that market very much remains open. And by June 30 next year, we'll have a very significant amount of unencumbered GPUs that we can arrange debt financing against."
2. The increased scrutiny of hyperscalers' balance sheets and why that is already benefitting IREN
Quote:
“What we're actually seeing from the largest users, whether hyperscalers or the large foundational AI labs, is a continued increase in demand. If you look at hyperscalers, for example, who have increased scrutiny on their balance sheet positions, I think it's actually becoming more attractive for them to contract with players like ourselves. Instead of taking capex onto the balance sheet, they can secure compute as an opex line item. So that's actually driving an increase in demand on our side, contrary to some of those very specific examples, which I think are more tied to the underlying assets themselves.”
These two comments don’t guarantee anything, but they give me greater confidence that GPU debt financing will remain available to IREN - even for deployments backed by non-investment-grade customer cash flows.
They may also offer clues about who could become the anchor tenants at SW1 and Horizon 5–6.
Could we see a bidding war among hyperscalers and frontier labs for that capacity?
Here’s hoping. 😀
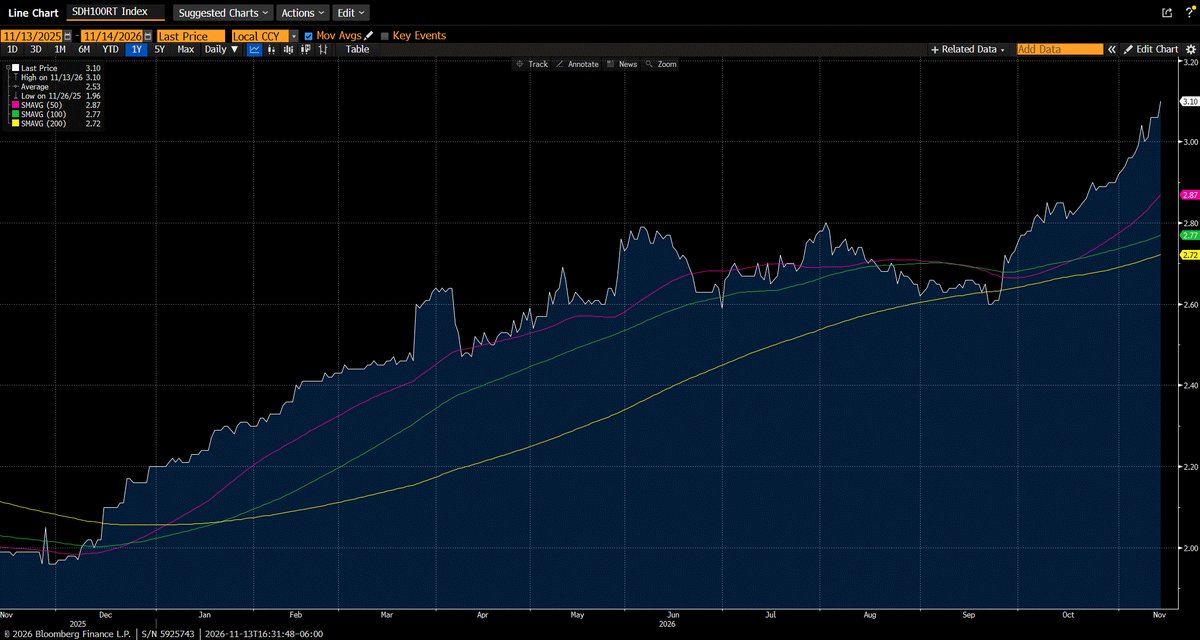
We started shipping the Nvidia H100 in 2022.
A year ago it rented for $1.96/hour.
Today: $3.10.
+58%, on a chip that was supposed to be obsolete by now.
So much for GPU depreciation.
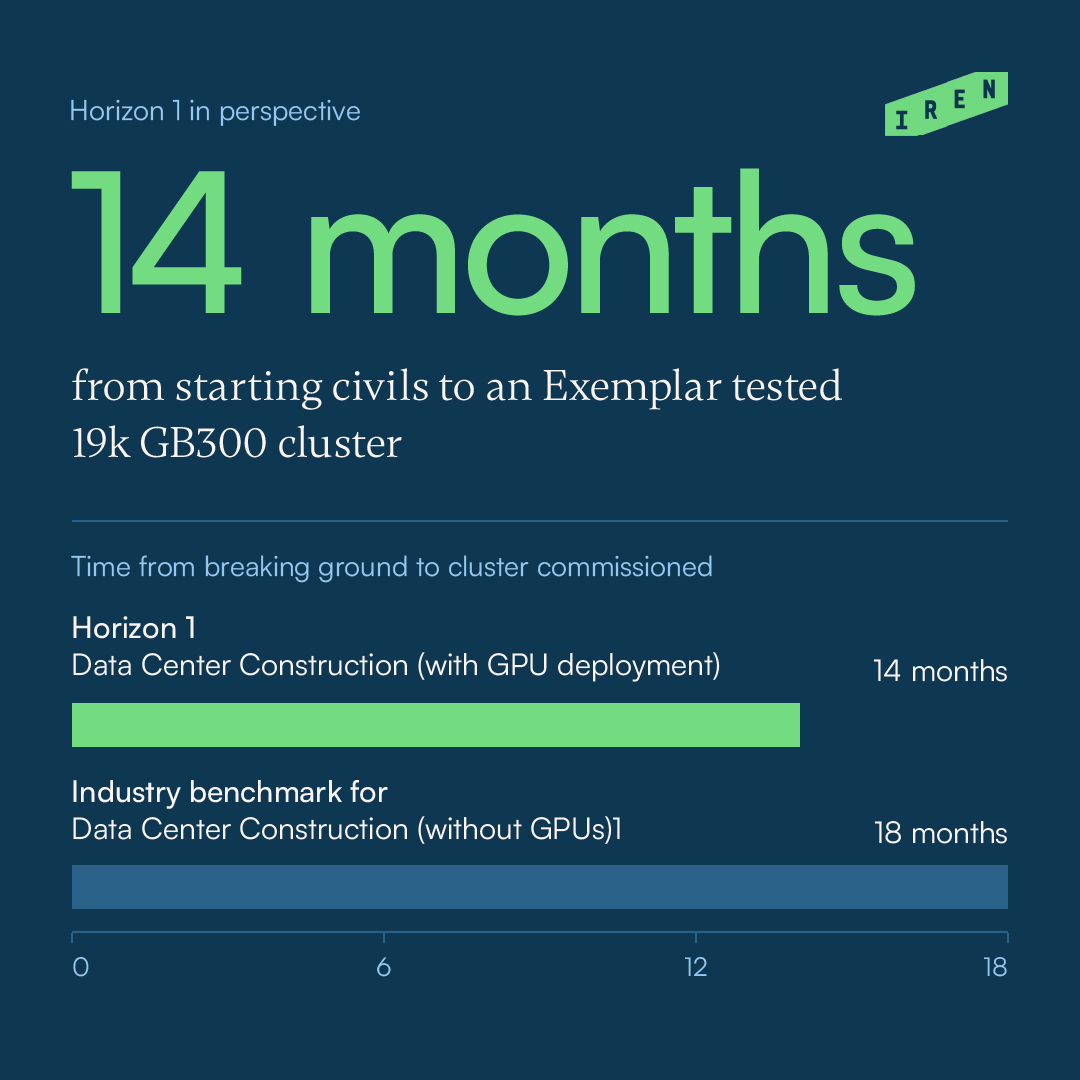
22% faster delivery than the industry benchmark.
Horizon 1, the first of four 50MW (IT) AI Cloud deployments for Microsoft, went from starting civils to an NVIDIA Exemplar Cloud-tested GB300 cluster in 14 months.
IREN's vertical integration delivers end-to-end control across design, engineering and construction, so contracted capacity reaches customers sooner.
Reasons not to hike rates at all, let alone 50bps:
1. Oil just crashed 20%
2. CPI is backward-looking
3. Inflation is at the average of the last 40 years
4. Stocks crashed last week
5. It's one print. An ugly print, but one print, and the Fed shouldn't be making decisions based on one data point
6. Inflation was a lot higher in 2021 and there was no urgency then, why, I wonder, does everyone have religion about this all of a sudden?
7. You never hike into a supply shock
8. Everyone knows this is about politics
9. Everyone knows Warsh is strongly disliked
10. And Warsh is a proxy for Trump
11. Copper just broke the uptrend
12. A 50bp move is for emergencies. Nothing here constitutes an emergency.
13. See my previous tweet
Don’t Strangle the Supply-Side Recovery
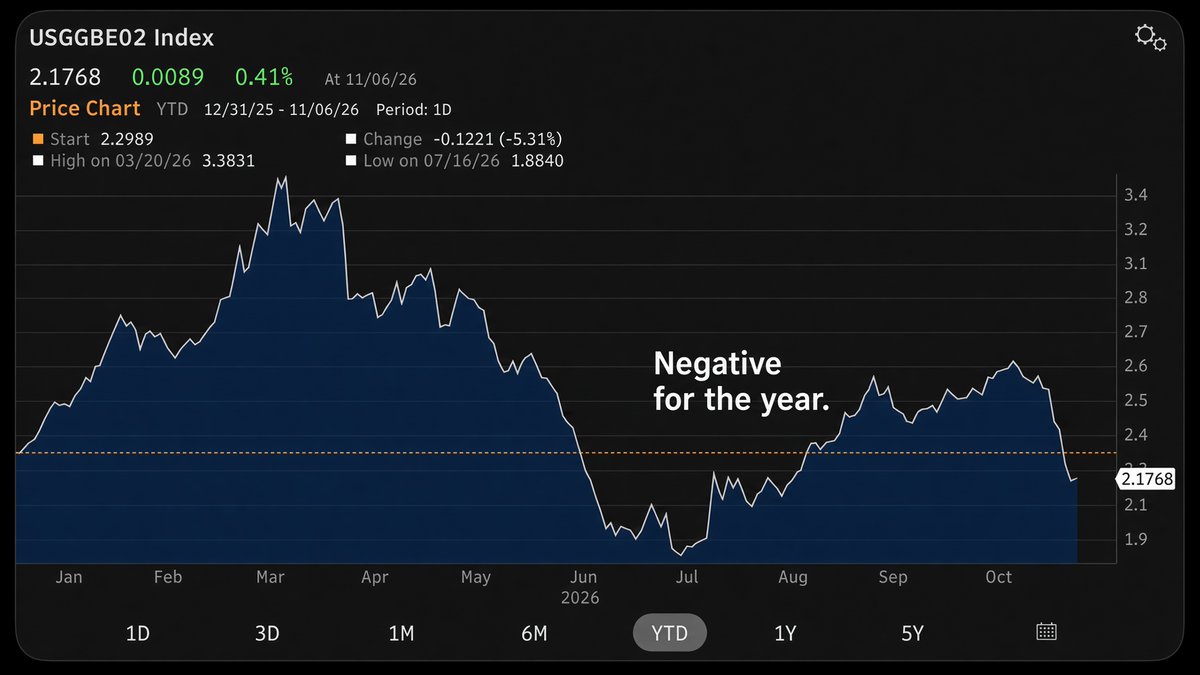
The case for another Federal Reserve rate increase is crumbling. Gasoline prices are falling. Some DRAM spot prices are retreating. Two-year inflation breakevens have dropped 20 basis points in three days to 2.18%. Yet the tightening debate remains trapped in yesterday’s inflation.
That is how policy mistakes happen.
Tariffs and chip shortages raise the price level. They do not automatically create permanently higher inflation. Once those increases enter the comparison base, their contribution to annual inflation fades.
A product that rises from $100 to $110 records ten percent inflation. If it stays at $110 a year later, inflation is zero. No rate increase is needed to make that arithmetic work.
As 2026’s price spikes roll out of the annual comparison in 2027, base effects will pull inflation lower, without another Fed hike.
Now add actual price declines. Gasoline and parts of the memory market are reversing earlier increases. Disinflation is not merely approaching. It is underway.
The bigger story is productivity. Strong productivity growth, falling unit labour costs and a strong jobs market describe an economy expanding its capacity, not simply overheating. Businesses can produce more, support higher wages and contain costs simultaneously.
These are the green shoots Trump’s supply-side agenda is designed to cultivate: stronger investment, greater productive capacity and non-inflationary growth. The test of that agenda is sustained improvement in output and costs, not whether every strong jobs report triggers another inflation scare.
Employment growth is not the enemy of price stability. Weak productivity is. Treating every sign of economic strength as excessive demand risks strangling the supply expansion that makes growth sustainable.
The bond market is delivering its own warning. Two-year breakevens approaching 2% undermine the argument that inflation expectations are becoming unmoored. In fact they’re negative for the year.
The Fed must explain what another hike would fix. Higher borrowing costs cannot repeal tariffs or manufacture chips. They can crush investment just as productive capacity begins delivering results.
Those demanding tighter policy carry the burden of proof.
Do not punish stronger supply for looking like stronger demand.
@AndyLauxxx I believe they only said that the YE target is pushed back 1-2 months bc of Microsoft request. I’m just assuming H3/H4 can’t be fully delivered without H2
$IREN Say what you want about dilution for IREN but they ran it very well in the last year and the financing flywheel is almost in full force now. Yes, they will still need to mix in equity/convert issuance but at a very small proportion relative to debt. Their relationships strengthen with every closed debt package. Onwards and UPWARDS.
$IREN: The Days of Endless Dilution Are Coming to an End
Against the roughly $6B of CapEx $IREN has yet to fund for FY2027, the company has access to $12B-$15B of NON-DILUTIVE funding sources.
Personally, I think the vast majority of that CapEx will ultimately be funded through customer prepayments and GPU financing.
GPU-backed debt in particular is one of the more lender-friendly forms of financing, since it is supported by both the cash flows from the underlying customer contracts and the GPUs themselves.
So even in a more challenging financing environment, I don’t believe securing GPU-backed debt should pose a major challenge for $IREN. And if it does, the company has plenty of other non-dilutive sources of capital at its disposal.
In any case, Thursday’s earnings call made it clear that $IREN is better capitalized than ever and no longer has to rely almost entirely on equity-related sources of capital to fund its growth.
It’s also worth taking a moment to appreciate what all that dilution, which caused plenty of investor grief over the years, actually bought shareholders.
By the end of FY27 in June, management is guiding for the business to own roughly $10B of data center assets.
Those assets can now be borrowed against to help fund the next stage of growth, creating a much more capital-efficient financing flywheel as the infrastructure base expands.
The days of heavy dilution are truly coming to an end.
I wouldn’t be surprised to see $IREN begin buying back shares as early as the early 2030s.
So old capacity isn’t as appealing with new workloads and models?? Bullish for $IREN and newer DCs. DSX design also mitigates this greatly moving into future. Bullish.
$MSFT WINDS DOWN AI CLOUD DEAL WITH $ORCL
Microsoft has reportedly declined to renew its 2023 agreement to rent AI computing capacity from Oracle and has been gradually shutting down that capacity in recent months, Bloomberg reports.
The deal was originally intended to power an AI-enhanced version of Bing.
However, the Oracle servers used older-generation Nvidia GPUs that no longer met Microsoft's computing specifications.
Oracle says demand for its AI infrastructure remains strong, including for older-generation GPUs.
@coffaro_tony@SemiAnalysis_ Incredibly bullish. Bought 500 shares in last week. Have been buying weekly for two years now. From $6 to highest buys of $60. This company will be worth hundreds of dollars in 2-3 years. It’s just a matter of when the market wakes up and realizes it.
I’m fully aware that no serious investor takes @SemiAnalysis_ seriously these days, but just to add insult to injury:
Let me get this straight...
Semi gloated about the leak that $IREN was facing delays with $MSFT and immediately used it as another opportunity to throw shade at the company.
Except they apparently failed to realize that it was $MSFT that requested networking / topology changes from what had originally been agreed, which is what pushed part of the deployment into early next year.
$IREN Co-CEO @danroberts0101 was very explicit about this on yesterday’s call.
He also explained that accommodating a change of this magnitude so deep into construction would be much harder for most other neoclouds, because they rely heavily on third-party data center providers and therefore have another party in the middle whenever something needs to be changed.
$IREN, on the other hand, owns and operates the entire infrastructure stack itself.
That vertical integration gave the company the flexibility to accommodate $MSFT's last-minute request, and Dan made clear that the relationship between the two companies remains “fantastic.”
In other words, $IREN was flexible and agile enough to accommodate a major last-minute change in $MSFT's requirements, even this deep into the deployment process.
And somehow @SemiAnalysis_ found a way to spin that into a negative for $IREN?
This really shows how disingenuous this “publication” has become....
How were independent retail analysts with a near-zero budget in @jiahanjimliu and @FransBakker9812 able to figure this out WEEKS ago, while one of the largest AI-focused “research companies” failed to understand what was actually happening?
Don’t they have sources at $MSFT?
Apparently they aren’t quite as well connected as they like to appear...
Who in their right mind is paying these clowns for their coverage? 😂
$IREN One month customer requested delay = SP cut in half while economics only got better 😂
More customers will gravitate to an ai provider willing to work with customers like this. It’s good business.
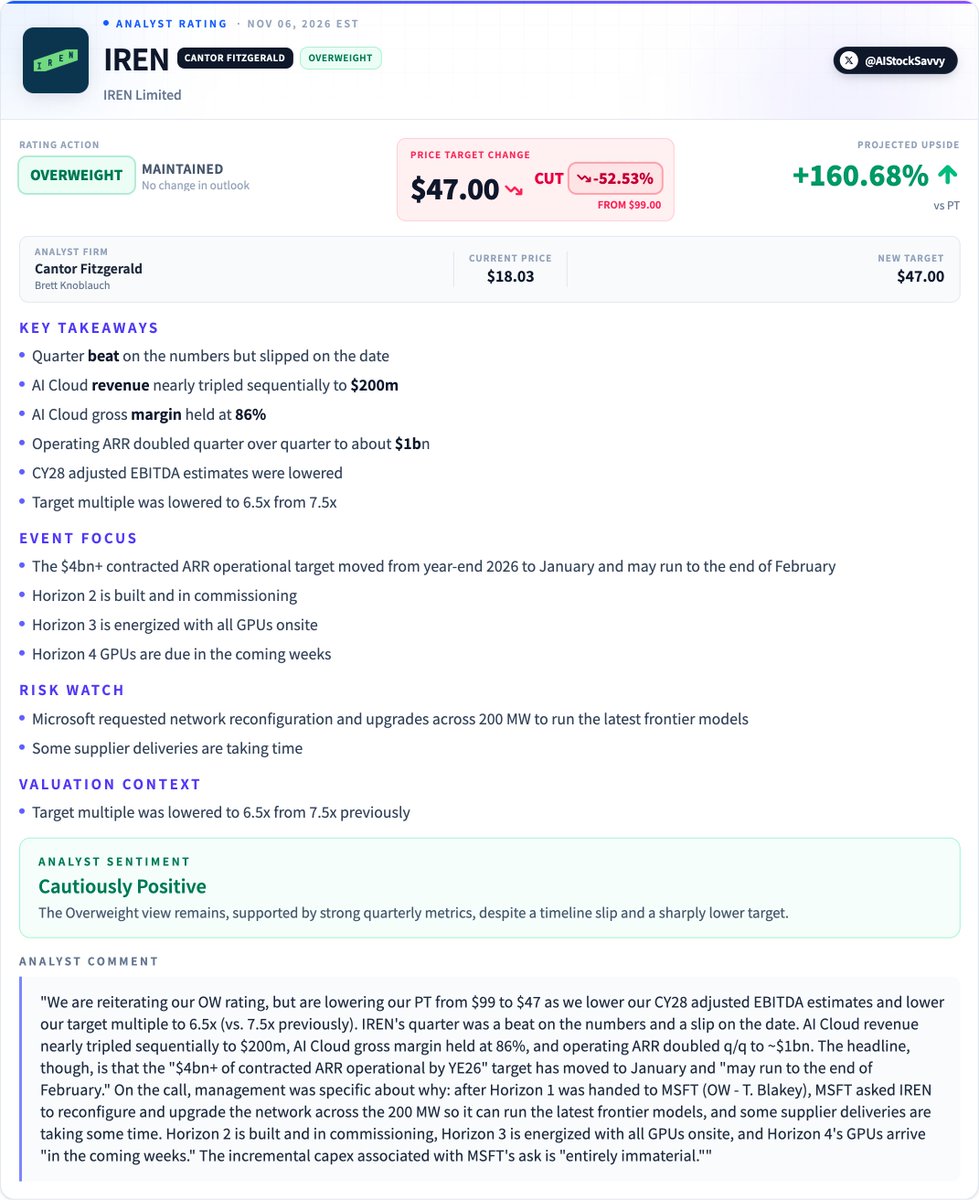
$IREN | Cantor Fitzgerald 𝗺𝗮𝗶𝗻𝘁𝗮𝗶𝗻𝘀 𝗢𝘃𝗲𝗿𝘄𝗲𝗶𝗴𝗵𝘁 on 𝗜𝗥𝗘�� 𝗟𝗶𝗺𝗶𝘁𝗲𝗱, cuts PT to $𝟰𝟳 from $𝟵𝟵
Analyst sees strong quarterly metrics but cuts estimates and the target multiple as the contracted ARR timeline slips.
@RealJimChanos Is this serious? I’m a CRE developer and I can tell you one thing. If i could collect prepayments from future apartment renters that cover 30%+ construction costs of that community, id be in heaven. You talk about it like it’s nothing important whatsoever. Yes it’s a capital intensive business. Yes there are risks. And therefore YES there is immense upside. The paybacks are so quick now and they are designing for future GPU generations in mind. DSX will give their LPS all sorts of upside options in the future. AI is not going away. $IREN