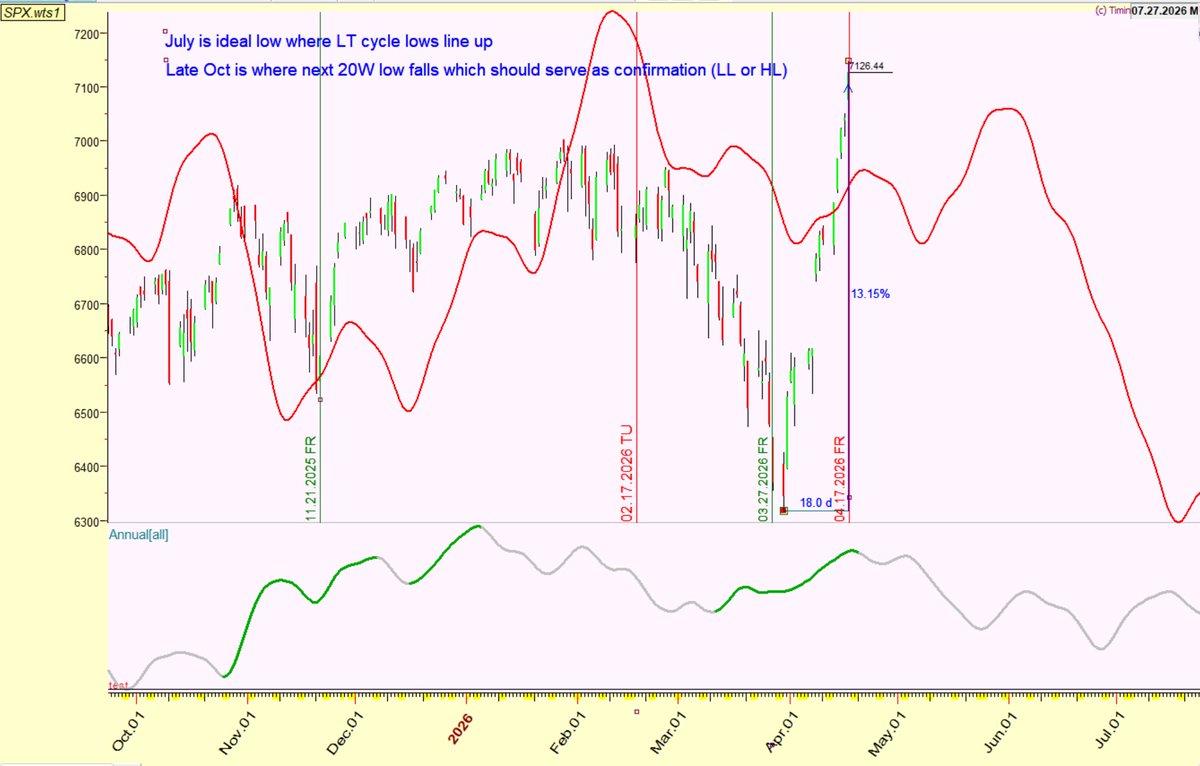
$SPX upd:
-Big picture remains unchanged: I am expecting a bear market with a buyable 3.5Y cycle low around Q3
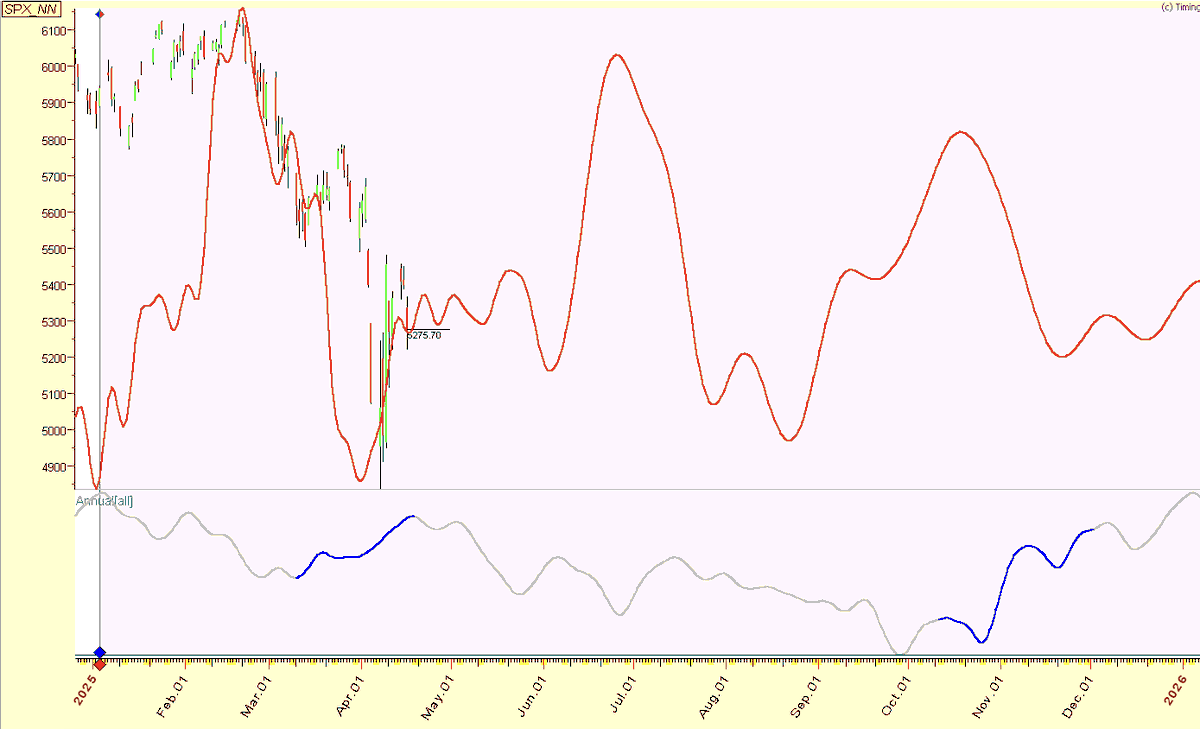
-See below Dec 2024 projection with updated price
-20W cycle low came on time (1 day after ideal date of Mar 27 in pinned post)
-I didn’t expect new ATH: I thought we’d reject around golden pocket retracement. Between CTA mechanical bid and Trump playing the market like violin we have the blow off top I was expecting in Feb, market always finds a way to laugh at you
-The new 40d cycle is 1/2 way through and next week should tell us whether this rally has more upside or terminates here
-For my base bear case I had Apr 17 as turn date, but so far no signs of a slowdown in buying yet. Opex often provides a pivot in the cycle - or a few days after it.
-Based on Hurst method we still have potential several % more upside in $SPX which I’m not chasing as just like in Feb when I exited the market RR for a trader like me who likes holding positions for several months is not great and we have weekend headline risk.
-Timing wise next 40d low is due ~May 7 which should give us more info on the structure (depth of a pullback and strength of a bounce into late May) which then sets up bigger decline into a higher degree summer low.
-Leading indicators showing bigger decline is still ahead in a few weeks so staying cash heavy.
-If you want more updates - like and retweet
I keep getting asked about $CSU.
50 things every Constellation Software investor should know to get up to speed.
The basics. The numbers. The structure. The model. The compensation. Mark Leonard. Mark Miller. The moat. The hidden assets. The risks.
All of it. Bookmark this.
THE BASICS
1. Founded in 1995 by Mark Leonard in Toronto. He spent 11 years as a venture capitalist before starting CSU.
2. Listed on the TSX. Ticker: https://t.co/6YiDsxMYKc. One of the 60 largest companies in Canada.
3. CSU acquires, manages, and permanently holds vertical market software businesses. Software built for one specific industry. Courts. Cemeteries. Utilities. Transit.
4. Why VMS? Individual market niches are tiny. Often under $5M. Venture capital and big tech ignore them. But the software is mission critical, has high switching costs, and generates recurring revenue. Nobody else wants it. Incredible economics once you own it. That's the arbitrage.
5. 125,000+ customers. 100+ countries. 1,000+ acquired businesses. 64,000+ employees.
THE NUMBERS
6. Revenue: ~$11B USD (TTM). Up from $3.5B in 2019. More than tripled in five years. No down years. Ever.
7. ~75% of revenue is recurring. Subscriptions and maintenance contracts. The foundation of everything.
8. Customer retention: 96-98% annually. Without long-term contracts.
9. IPO in 2006 at ~$18 CAD/share. Now ~$2,377 at today's beaten-down price. A 130x return. $10K at IPO = $1.3M today. At the 52-week high of $5,300 it was nearly 300x.
10. Free cash flow to shareholders (FCFA2S): $1.47B in 2024, growing 27% year over year. This is Leonard's custom metric. Brutally honest. Deducts the IRGA liability on purpose, making numbers look worse than reality.
THE STRUCTURE
11. Six operating groups, each large enough to be its own public company.
12. Volaris. Largest group. 240+ businesses across 40+ verticals. Transportation, financial services, communications. Miller's home base before becoming President.
13. Harris. Oldest group. Public sector roots. Utilities, healthcare, government, schools. 100+ businesses.
14. Jonas. Started in club management software. Now fitness, hospitality, construction, foodservice. 140+ businesses.
15. Perseus. Healthcare, government, homebuilding. Smaller, closer to HQ.
16. Vela. Industrial. Oil and gas, manufacturing. 8 divisions.
17. TSS / Topicus. European operations. Spun out in 2021. Lumine Group spun out from Volaris. Both separate public companies where CSU retains significant interest.
18. Each business operates autonomously. HQ provides capital allocation and benchmarking, not operating directives. The culture is often described as "delegation to the point of abdication."
19. CSU is structured like Berkshire Hathaway but owns vertical market software instead of railroads and insurance. Decentralized. Permanent ownership. Zero stock-based compensation. Founder-led for 30 years.
THE MODEL
20. Buy and hold forever. Unlike private equity, CSU never sells an acquisition. This attracts better sellers. Founders who care about their employees and customers choose CSU over PE because the business stays intact.
21. The capital allocation cycle: buy sticky businesses, collect recurring cash flow, deploy into more acquisitions, compound. Repeat for 30 years.
22. CSU has identified tens of thousands of VMS businesses globally. They've acquired roughly 1,000 so far. The runway is measured in decades.
23. Typical deal: under $5M. Largest ever: Allscripts hospital business for ~$700M. Volume of small deals is the strategy.
24. $1.8B deployed into acquisitions in 2024 alone.
THE COMPENSATION
25. Zero stock-based compensation. $0. Ever. In 30 years. Executives buy shares at market price with their own cash. Same price as you and me.
26. Executives must invest up to 75% of their after-tax bonus in CSU shares with a 4-year lockup. Skin in the game is not optional. It is policy.
27. Leonard waived all salary and bonus in 2014. "I'm your partner in CSI, not your employee." His compensation from that point forward was stock appreciation only.
28. Many CSU employees are now millionaires through their shareholdings. No options. No RSUs. Open market purchases with their own money.
MARK LEONARD
29. Published annual shareholder letters that developed a cult following. Disclosed ROIC, organic growth breakdown, capital allocation philosophy in detail. If you own this stock and haven't read them, start there.
30. In 2018, wrote his last annual letter. Drew an analogy between VMS and the newspaper industry lifecycle: growth, consolidation, eventual decline. "I anticipate that the VMS industry will evolve similarly."
31. Same letter: "I am already casting about for such opportunities" outside VMS. He was looking beyond VMS seven years before stepping down.
32. Broke his silence in 2021 with one letter. The only topic important enough to make him write again: lowering hurdle rates and redirecting ALL free cash flow into bigger acquisitions and new asset classes. "I have converted, and with the fervour of the newly converted, I am busy demonstrating my new-found faith."
33. Named Mark Miller in that 2018 letter with "10,000 hours of relevant experience." Seven years before he needed a successor.
34. Resigned as President in September 2025 for health reasons. Stock crashed 17% that week.
35. Almost no photos of him exist online. No earnings calls since 2018. Cancelled them to protect acquisition intelligence from competitors.
MARK MILLER
36. Joined CSU in 2001 through Trapeze, CSU's very first acquisition from 1995. A CSU lifer.
37. Led Volaris, the largest operating group. The board called him "the most experienced, knowledgeable, and capable person" to lead.
38. The majority of acquisitions in the last decade were made by people who are not Mark Leonard. The machine was built to outlast any one person. Whether it does is the open question.
THE MOAT
39. Switching cost layer 1. Cost irrelevance. Software costs less than 1% of a customer's revenue. Even if a competitor offered it free, the migration risk wouldn't justify switching.
40. Switching cost layer 2. Decision maker incentives. The buyer is often a government employee who faces career risk if a switch fails and zero upside if it succeeds. Rational choice: don't touch it.
41. Switching cost layer 3. Regulated data. Court records have chain of custody. Utility billing has compliance audit trails. Government permits have public records obligations. Legal barrier, not technical.
42. The majority of CSU's revenue comes from government and regulated customers. Government headcount has grown almost every decade for 70+ years. The IRS still runs COBOL from the 1960s. These customers don't switch.
HIDDEN ASSETS
43. The IRGA: CSU's interest in Topicus shows as a ~$1B liability on the balance sheet. It's arguably worth ~$3B+. One of the most misunderstood line items in CSU's financials.
44. Topicus and Lumine spinouts decentralize capital allocation further and create more acquisition capacity across the system.
45. VMS Ventures: $200M fund launched in 2021 to acquire distressed startups that can't turn profitable after raising venture dollars. Buying distressed SaaS at a discount.
THE RISKS (HONEST)
46. Leonard's health and reduced involvement. Miller is unproven at enterprise-scale capital allocation outside VMS. This is the biggest open question.
47. Competition for acquisitions increasing. PE and other serial acquirers bidding up VMS valuations. Leonard acknowledged this himself.
48. AI risk: not that someone builds better VMS. The real risk is the intelligence layer moving above it. If AI agents become the customer interface, whoever builds them captures the relationship.
49. ISS gives CSU a 9/10 governance risk score. Same structural penalties as Berkshire. Concentrated ownership, limited board independence. Understand what you own.
THE BOTTOM LINE
50. Three fear events priced in simultaneously: AI disruption + Leonard resignation + SaaSpocalypse. Down 55% from the 52-week high.
The moat isn't the software. It's the capital allocation machine and the people who run it. A thousand autonomous businesses compounding capital into a thousand more.
Every other serial acquirer copies the model. None of them copy the discipline.
I'm long $CSU. What did I miss?
Bonus: Mark Leonard once built a flamethrower.
My 4-year Bitcoin cycle calculation (at the end of 2024). It is a gem, study carefully.
If you retweet, I'll DM you amy preferred bullish count for BTC (must follow).
---------------------
Get your Free eBook "1-Year US Stock Market Outlook” with over 70 charts. Download 👇
https://t.co/IgSRysWe1k
---------------------
Interested in Bitcoin? Watch this video for long-term cycle and Elliott Wave analysis of Bitcoin.
If you are interested please retweet, and I'll DM you a 6-month cycle projections outlook for Bitcoin (must follow).
https://t.co/RexJMqQjNq
🔮 $SPX projection from Jan 2025 with price updated. if Apr 7 low holds, it's as close call as I can possible make (Mar 28 was "ideal" low for 10%+ correction). No change - staying the course, it's never easy. I understand most cycles guys now think we are in early stages of a secular bear market. I get daily questions on this, this is NOT my view. If something changes I will make sure to provide an update. You can't trade someone else's conviction, especially when volatility is at multi year highs. I am just trying to post how I am trading it and navigating last phase of the big cycle.
PS Ignore minor variation in squiggles on the chart vs Jan forecast, I changed some secondary settings like sample size or number of overtones but it's de minimus/mostly noise. If you found this helpful and want to continue receiving updates - please retweet.