$sofi
I hate to keep giving away strategy, but if you ask ai the right questions....
Yes, SoFi is playing a masterful dual-network strategy that highlights exactly how a tech-forward bank can exploit the fierce competition between Visa and Mastercard.
Just this week, SoFi went completely live with a massive $25 billion card migration exclusively onto Mastercard's rails. Yet, behind the scenes, they still retain the tech infrastructure to route through Visa. [1, 2, 3]
SoFi is capturing the "best of both worlds" by executing this strategy across three distinct areas:
## 🚀 1. The Mastercard Play: Live Stablecoin Production
While Visa has been doing high volume with non-bank stablecoins like USDC, Mastercard wanted a win with a regulated bank. SoFi used this leverage to extract a massive deal. [4]
*
* The Launch: On September 22, 2026, SoFi Bank migrated its entire $25 billion debit and credit card program onto Mastercard rails using its own proprietary stablecoin, SoFiUSD. [2, 3]
* How it benefits SoFi: Because SoFi Bank issues SoFiUSD (under strict OCC national bank regulations), they completely bypass traditional, slow settlement windows. When a user swipes their Mastercard, SoFi settles the back-end instantly on public blockchain rails (primarily Solana). [5, 6]
* The Monetization Strategy: SoFi isn't just a consumer app anymore. By building this with Mastercard, SoFi is pitching "SoFiUSD settlement" to large multinational retailers as a B2B infrastructure provider, aiming to capture massive institutional payment processing revenue. [3, 7]
*
------------------------------
## 🛡️ 2. The Visa Play: Tech Stack Redundancy (Galileo)
Even though SoFi’s primary consumer cards run on Mastercard, SoFi owns Galileo Financial Technologies (the actual processing engine under SoFi Tech Solutions). [7]
*
* Multi-Network Rails: Galileo maintains active, native integrations with both Visa and Mastercard networks.
* The Advantage: If Mastercard’s network ever experiences a localized outage or changes contract terms unfavorably, SoFi can flip a switch on the Galileo backend. They can route transaction messaging or issue alternative corporate card programs directly over Visa rails. Visa has been aggressively scaling stablecoin programs via Bridge, meaning Visa's plug-and-play architecture is always sitting there as a viable threat to Mastercard's dominance over SoFi's volume. [1, 8]
*
------------------------------
## 🥊 3. Forcing the Networks to Compete
In the payments industry, the network contract is a massive revenue driver. When an issuer like SoFi scales to over $25 billion in volume, Visa and Mastercard enter aggressive bidding wars, throwing in "contract sweeteners," higher marketing reimbursements, and lowered fee tiers to win the business. [9]
By keeping a foot in both tech camps, SoFi ensures that neither Visa nor Mastercard can ever take their volume for granted. They get the absolute highest-tier support from Mastercard to prove out their new stablecoin rails, while keeping Visa as the ultimate infrastructure backup and strategic hedge. [1, 2]
Would you like to look at how SoFi Bank manages to settle transactions instantly for merchants at zero cost using SoFiUSD, or examine how Galileo's dual-network APIs actually work behind the scenes? [1, 10]
[1] [https://t.co/6epYv39ifu](https://t.co/GLwEZTrEh6)
[2] [https://t.co/AdQiqma6no](https://t.co/O4hAfbImF0)
[3] [https://t.co/gPejAZJrSi](https://t.co/ewLT5XXi8Q)
[4] [https://t.co/kLCLcAubQ3](https://t.co/Puwrjkrr4C)
[5] [https://t.co/JzE2f50ZsJ](https://t.co/Tr48hDqlsO)
[6] [https://t.co/8Ejfv9TZ75](https://t.co/OZYb2JDXA1)
[7] [https://t.co/hvhQE5fLzP](https://t.co/v80HDnnNBU)
[8] [https://t.co/6Il3LsGI3v](https://t.co/LKzEfCfeVn)
[9] [https://t.co/ZZ71plFx2m](https://t.co/7Wg2MSF10k)
[10] [https://t.co/ezlfjZRYyL](https://t.co/Qmg7WRAvHi)
$sofi
They have an exclusive deal with MasterCard to use sofi usd (as well as others) for settlement.
The potential partnership with Visa who uses OpenUSD through Coinbase and Circle stablecoins which are already embedded not only with Visa but in Latin America.
That's the Trojan Horse concept again. The partnership with visa isn't using sofi as primary settlement but they are discussions regarding setting up Galileo architecture so Sofi usd works seemlesy with the existing primary stablecoins used by Visa with over $20 billion of transactions.
That's a sneaky way of having consistent architecture leading to further adoption of Sofi USD by visa not through visa direct demand but by visa partner retailers demand which will occur as a result of their use of Sofi USD with Mastercard.
As explained by grok 85% accurately
Anthony Noto’s discussions with Visa focus on backend software integration and network interoperability rather than pushing Visa to adopt SoFi USD as a primary settlement asset. While Mastercard remains the exclusive live settlement partner for SoFi USD, SoFi is actively negotiating with Visa to ensure its B2B banking software arm, Galileo, can seamlessly issue stablecoins across both major credit networks. Additionally, the partnership talks aim to bridge the gap between competing ecosystems through the industry's broader Open USD (OUSD) initiative. By collaborating with Visa on shared technological standards, SoFi ensures that its bank-grade token can interact with Visa’s infrastructure, allowing merchants on both networks to process transactions without friction.
Crucially, Visa’s hesitation to natively adopt SoFi USD stems from its existing multi-billion dollar allegiance to alternative digital currencies. Visa has built its entire $20 billion stablecoin settlement engine around non-bank stablecoins, heavily relying on Coinbase and Circle's USD Coin (USDC) over high-speed networks like Solana. Because Visa has already anchored its institutional validation and 160+ card programs to the deep liquidity of Circle's ecosystem, Noto's forward-looking Visa discussions focus on establishing bridge protocols that allow bank-issued tokens like SoFi USD to peacefully co-exist and trade with Coinbase and Circle's dominant market assets.
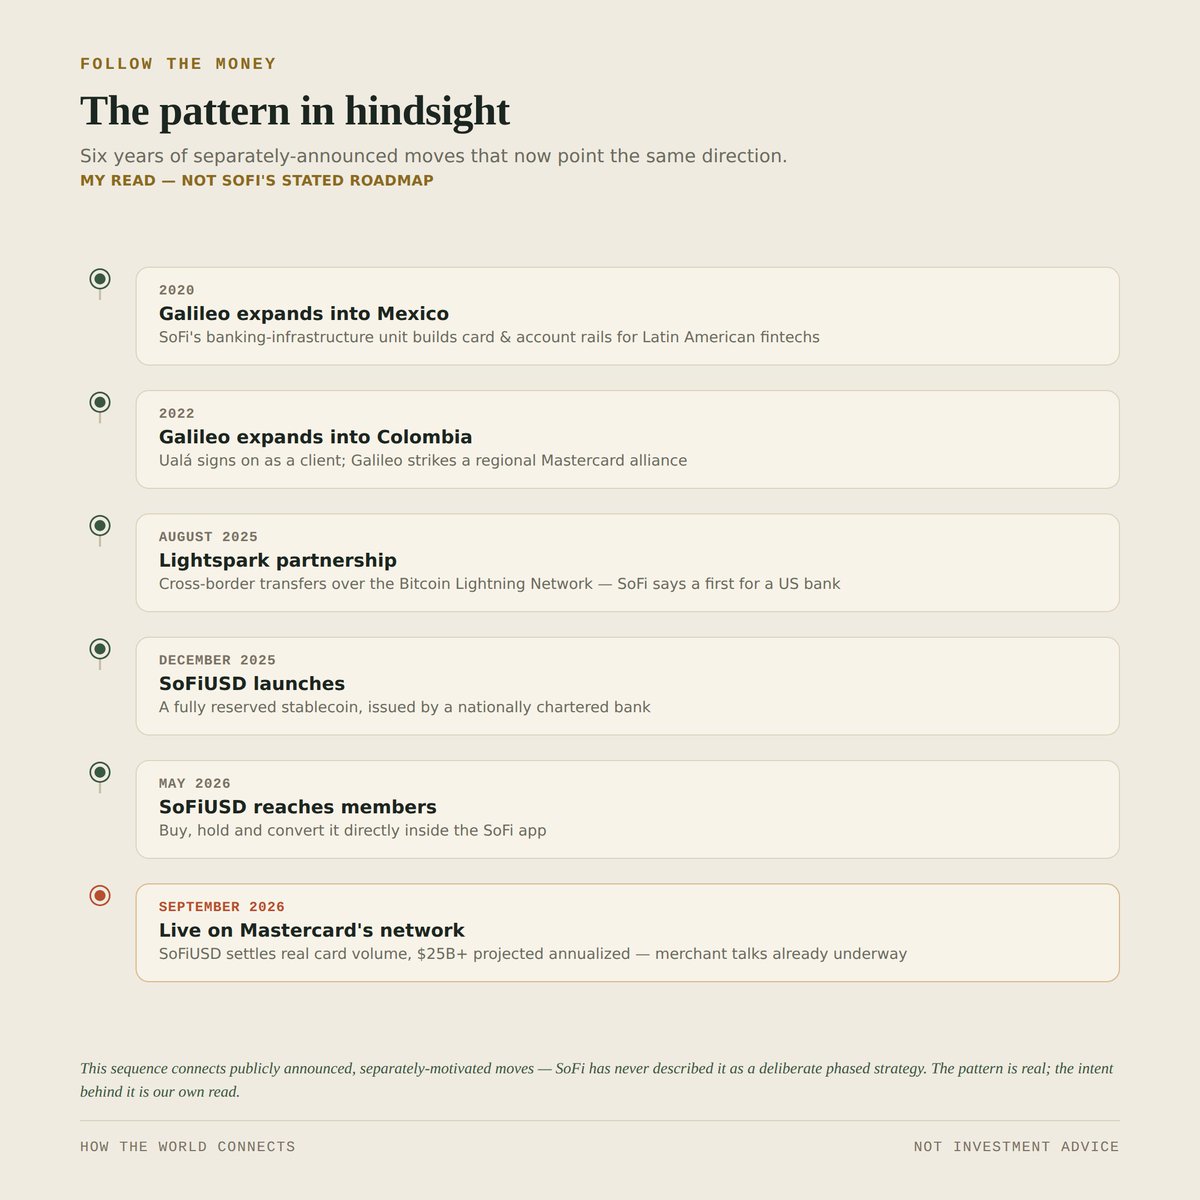
The open question isn't whether banks adopt stablecoins — that's already happening. It's who owns the rail merchants and consumers actually touch. $SOFI's bet: move fast like a fintech, carry the trust of a nationally chartered bank. Here's the six-year pattern behind that bet:
Everyone is focused on $SOFI moving $25B+ of card volume onto SoFiUSD settlement rails with $MA.
But this might only be phase one.
Back in March, Mastercard said Galileo would be among the first to offer its clients and their issuing banks the choice to settle transactions using SoFiUSD.
Now SoFi has actually taken the system live with its own card volume.
That makes the next step a lot more interesting.
If SoFi can expand these same rails across Galileo clients and other financial institutions, SoFiUSD becomes a much bigger opportunity than just settling SoFi transactions.
I haven’t seen many people talking about this part yet.
Global uncertainty continues to push energy prices higher, and that’s putting more pressure on Albertans’ wallets.
Today I announced that relief is on the way. Starting Oct. 1, Alberta will suspend the full provincial fuel tax, saving Albertans 13 cents per litre on gasoline and diesel every time they fill up until the end of the year. This is practical relief that helps families, workers and businesses keep more money in their pockets.
Albertans already pay the lowest overall taxes in Canada, and this cut adds to our unmatched tax advantage.
@NotA_Bull I think when are able to control one thing and it’s your business. And the business is excelling why does the stock matter when you have no control of the stock market makers.
We're the first national bank to bring stablecoin settlement live across @Mastercard's global payments network. @SoFi is migrating its entire $25B+ card program to blockchain-based settlement.
The speed of blockchain, with the safeguards of a bank. Let’s go‼️
https://t.co/e9RJuyQm6E